


EN
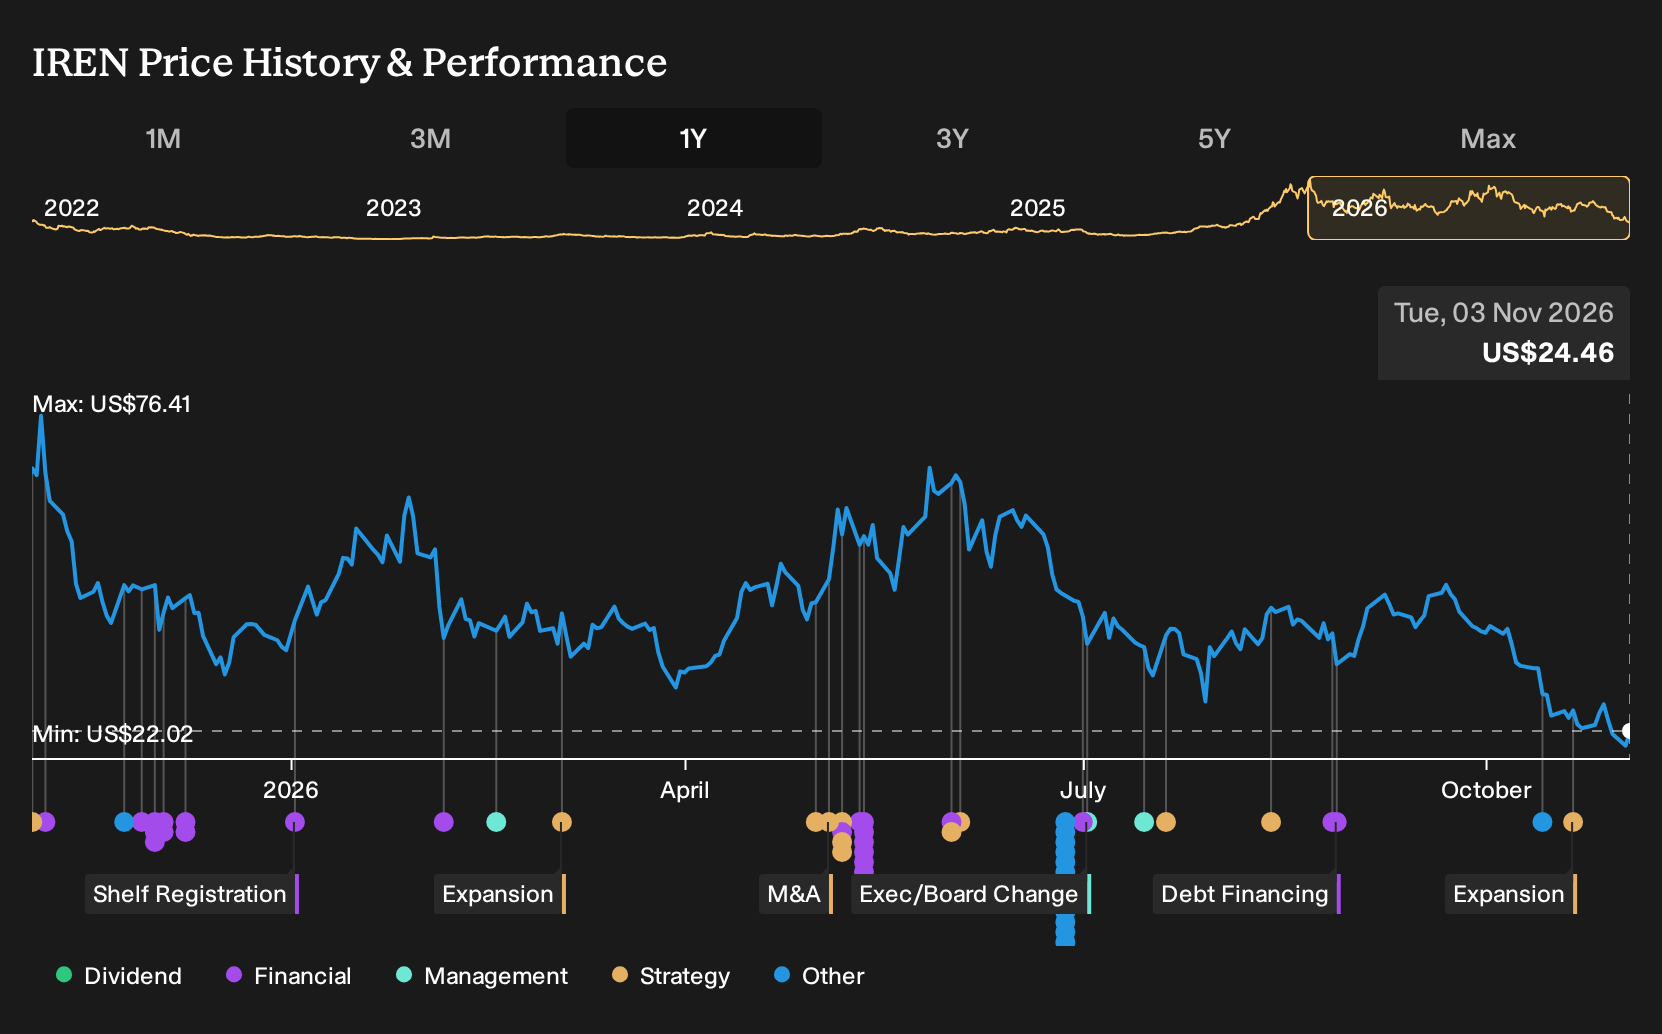
IREN Stock In Focus Ahead Of Earnings And AI Data Center Expansion
- IREN has set up IREN Europe and secured a civil works license for a planned 300MW AI data center campus in Badajoz, Spain. The campus is designed around closed-loop liquid cooling and compatibility with the NVIDIA DSX AI Factory Platform, with initial operations targeted for 2028.
- The planned Badajoz hub, backed by secured grid power and Mirantis-derived k0rdent AI software for workload isolation and data governance, reflects IREN’s effort to serve European AI customers that need tighter control over where data sits and how infrastructure is managed.
- This article examines how IREN’s investment narrative is being shaped by its Badajoz AI data center plan as earnings scrutiny builds.
Review how IREN’s Badajoz build fits into the broader AI infrastructure race by comparing it with other data center players screened in our curated list of 53 AI infrastructure stocks.
IREN Investment Narrative Recap
To own IREN, you need to believe the pivot from mostly Bitcoin mining to a vertically integrated AI infrastructure platform can scale fast enough to justify heavy build costs and a short cash runway. The Badajoz project supports that long-term story, but with first capacity only targeted for 2028 it does little for near-term earnings pressure.
Right now, the key near-term catalyst is customer traction on existing AI leases and the November 5 results, where investors are watching contract progress against high cash burn. The biggest risk is that debt-funded expansion and volatile crypto revenue stretch liquidity before AI cloud services contribute enough steady cash flow.
The most relevant recent thread for this Badajoz announcement is the broader stress across neocloud operators that Elon Musk highlighted, including concerns over access to credit for infrastructure-heavy players with limited non-data-center revenue. IREN has more cash against debt than some peers, but the business still faces tight financing conditions.
That context makes execution on Badajoz and other power sites less about ambition and more about staged delivery, contract visibility, and funding discipline. The campus license and secured grid power help the long-dated growth pipeline, while the near-term catalyst remains whether IREN can sign and ramp AI tenants fast enough to support that build plan.
IREN's narrative projects US$15.0b revenue and US$1.8b earnings by 2029. That profile is built on analysts' assumption of 177.0% yearly revenue growth and an earnings swing of roughly US$2.5b from a loss of US$702.6m today to forecast consensus earnings of US$1.8b.
Uncover why IREN's fair value indicates a 214% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the lowest IREN analysts lean hard into funding risk. They were only modeling about $5.1b of revenue and $628.9m of earnings by 2029 before this Badajoz update, far below the $15.0b and $1.8b consensus profile. Use that gap as a prompt to explore how sharply views on IREN can differ.
Explore 16 other IREN fair value estimates, including one that suggests it could be worth just $41.50!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your IREN research is our analysis highlighting 2 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for IREN. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate IREN's overall financial health at a glance.
Looking For More Investment Ideas Beyond IREN?
If the IREN story has you thinking about position sizing and diversification, it can help to line it up against other opportunities that match your risk profile and income needs. The Simply Wall St Screener gives you a way to filter for specific traits, then scan through individual companies one by one.
- If capital preservation matters most to you, start with a basket of companies that score well on balance sheet strength using our 30 resilient stocks with low risk scores as a first pass.
- For readers hunting for quality at a sensible price, the 34 high quality undervalued stocks can highlight businesses where fundamentals and valuation appear more aligned.
- If you prefer durable cash flows and regular income, the 4 dividend fortresses can be a useful starting universe to investigate potential yield ideas in more detail.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com