


EN
DTS (TSE:9682) Q2 Results Highlight Profit Growth Despite Softer Revenue
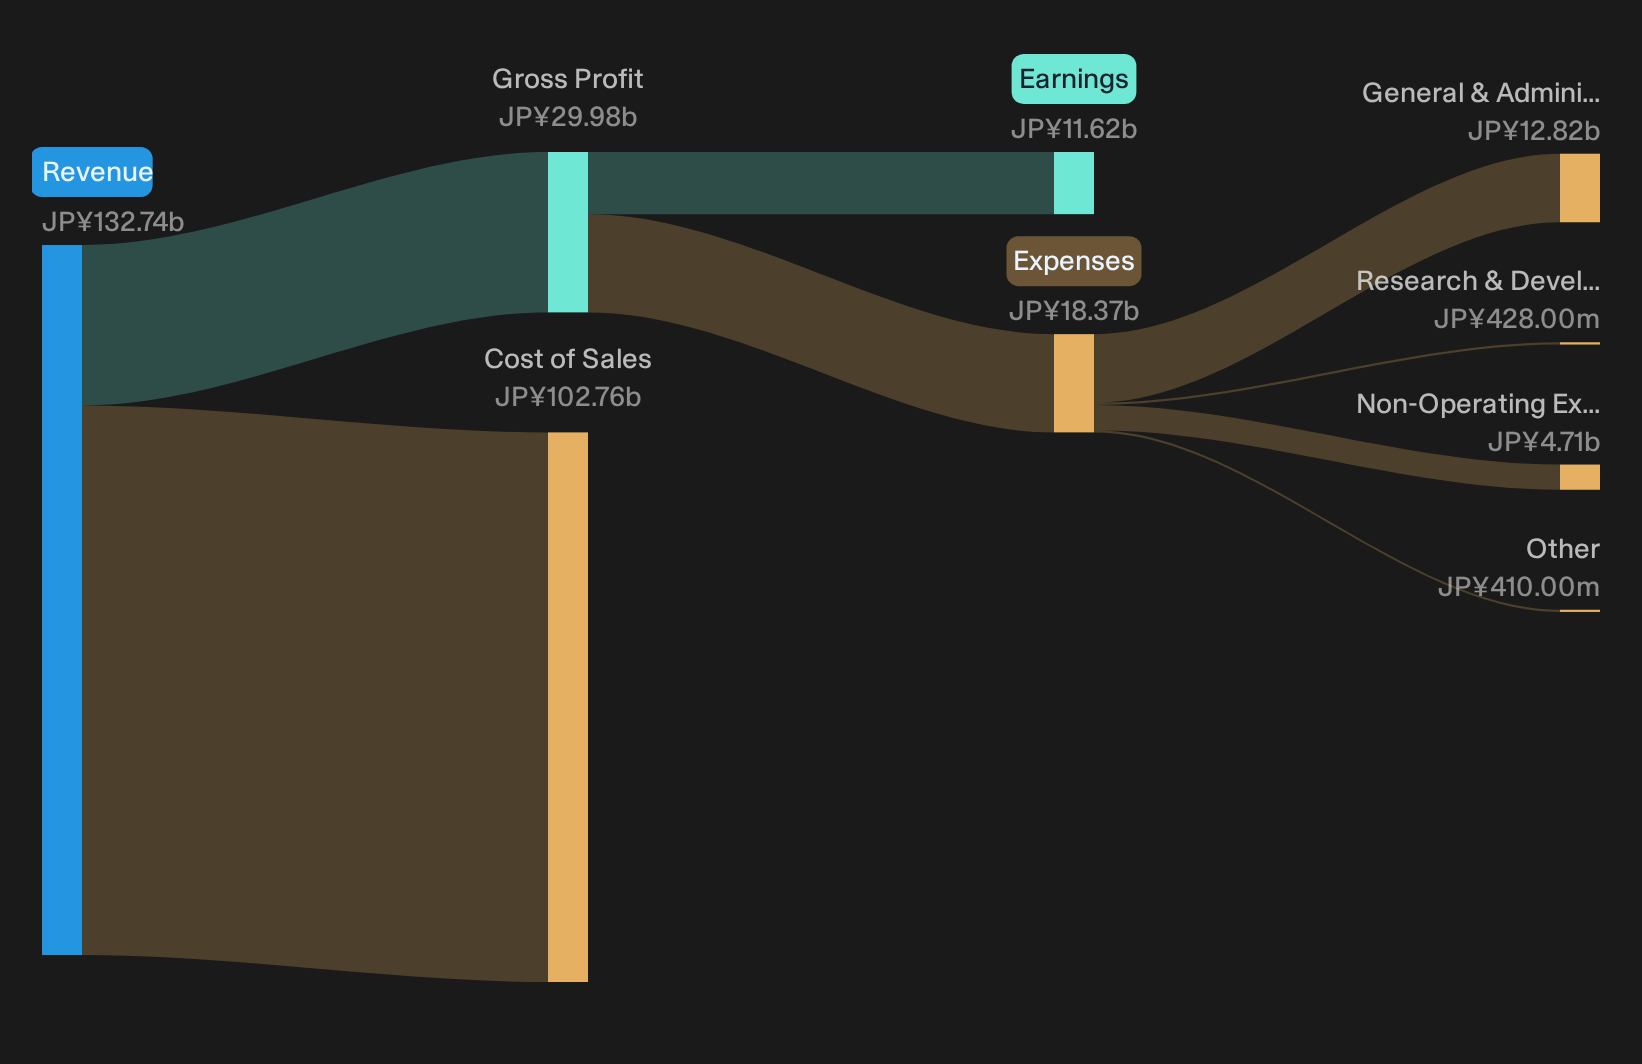
DTS stock came into the Q2 2027 earnings release on 2 November at ¥1,134, slightly weaker over the past week but still positive over three months. The headline result was solid profit generation, with Basic EPS at ¥20.10 and net income at ¥3,130 million, sitting on top of a trailing twelve month P/E of 15.2x that is lower than both peer and broader IT sector averages.
The near term price wobble contrasts with a longer view. In that context the valuation looks restrained, and earnings power over several years, while recently softer, still underpins the core DTS equity story.
Like the earnings strength at DTS but uneasy about paying up for a sector where multiples are often richer? Check out the 17 high quality undervalued stocks as a reference point for other profitable stocks with more restrained valuations.
Q2 2027 Earnings Summary
- Revenue (Q2 2027 vs. Q2 2026): ¥33,434 million vs. ¥34,018 million (slightly lower year on year)
- Net Income (Excl. Extra Items, Q2 2027 vs. Q2 2026): ¥3,130 million vs. ¥2,770 million (up about 13.0%)
- Basic EPS (Q2 2027 vs. Q2 2026): ¥20.10 vs. ¥17.39 (up about 15.6%)
- Net Profit Margin (Trailing 12 Months vs. Prior Year TTM): 8.8% vs. 8.8% (stable year on year)
Earnings show how Q2 looked on paper, but investors who care about what DTS is really worth often focus more on the cash being generated and retained in the business over time.
On DTS' cash flows alone, the stock could be a mild 10% undervalued.
DTS earnings, testing the optimistic story
For anyone leaning positive on DTS as a steady digital transformation partner, this quarter helps the case. Profitability moved in the right direction, with net income and EPS both higher than a year ago while the trailing net margin stayed at 8.8%. Revenue softened slightly, yet the business still converted a similar share of sales into earnings. That mix, modest top line slippage but stronger profit, suggests cost discipline and a service mix that can carry earnings even when project flow is not pushing revenue higher.
DTS risks, where the results cut the other way
A more cautious view on DTS finds some support in the numbers as well. Revenue in Q2 2027 was marginally lower than the prior year, which fits concerns about competition in systems integration and timing of client projects. The flat trailing margin at 8.8% signals that profitability did not weaken, yet it also did not advance despite higher quarterly earnings. For investors worried about pricing pressure or slower IT spending, this pattern points to a solid but not clearly accelerating profit engine in the near term.
After flat margins and a slightly softer top line, are you sure the unstable dividend record is the only issue? Review the risk analysis for DTS which shows 1 important warning sign.Hunt Quiet Fundamental Shifts
DTS just reported a quarter where earnings and share price moved in different directions. The real opportunity is finding stocks that could be low debt before the market reassesses them.
- Company 1 - 17% below our estimate - adds sales headcount to pursue long-term maintenance contracts around existing elevator installations.
- Company 2 - 40% below our estimate - deploys AI tools to help employers automate hiring decisions and match workers to specific roles.
- Company 3 - 48% below our estimate - redirects major spending into an AI-first security platform converting one-off licenses into recurring subscriptions.
Those are three of them. See every one of the 22 solid balance sheet companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com