


EN
TAT Technologies (TATT) Q3 Results Fuel Margin Surge And Stock Gains
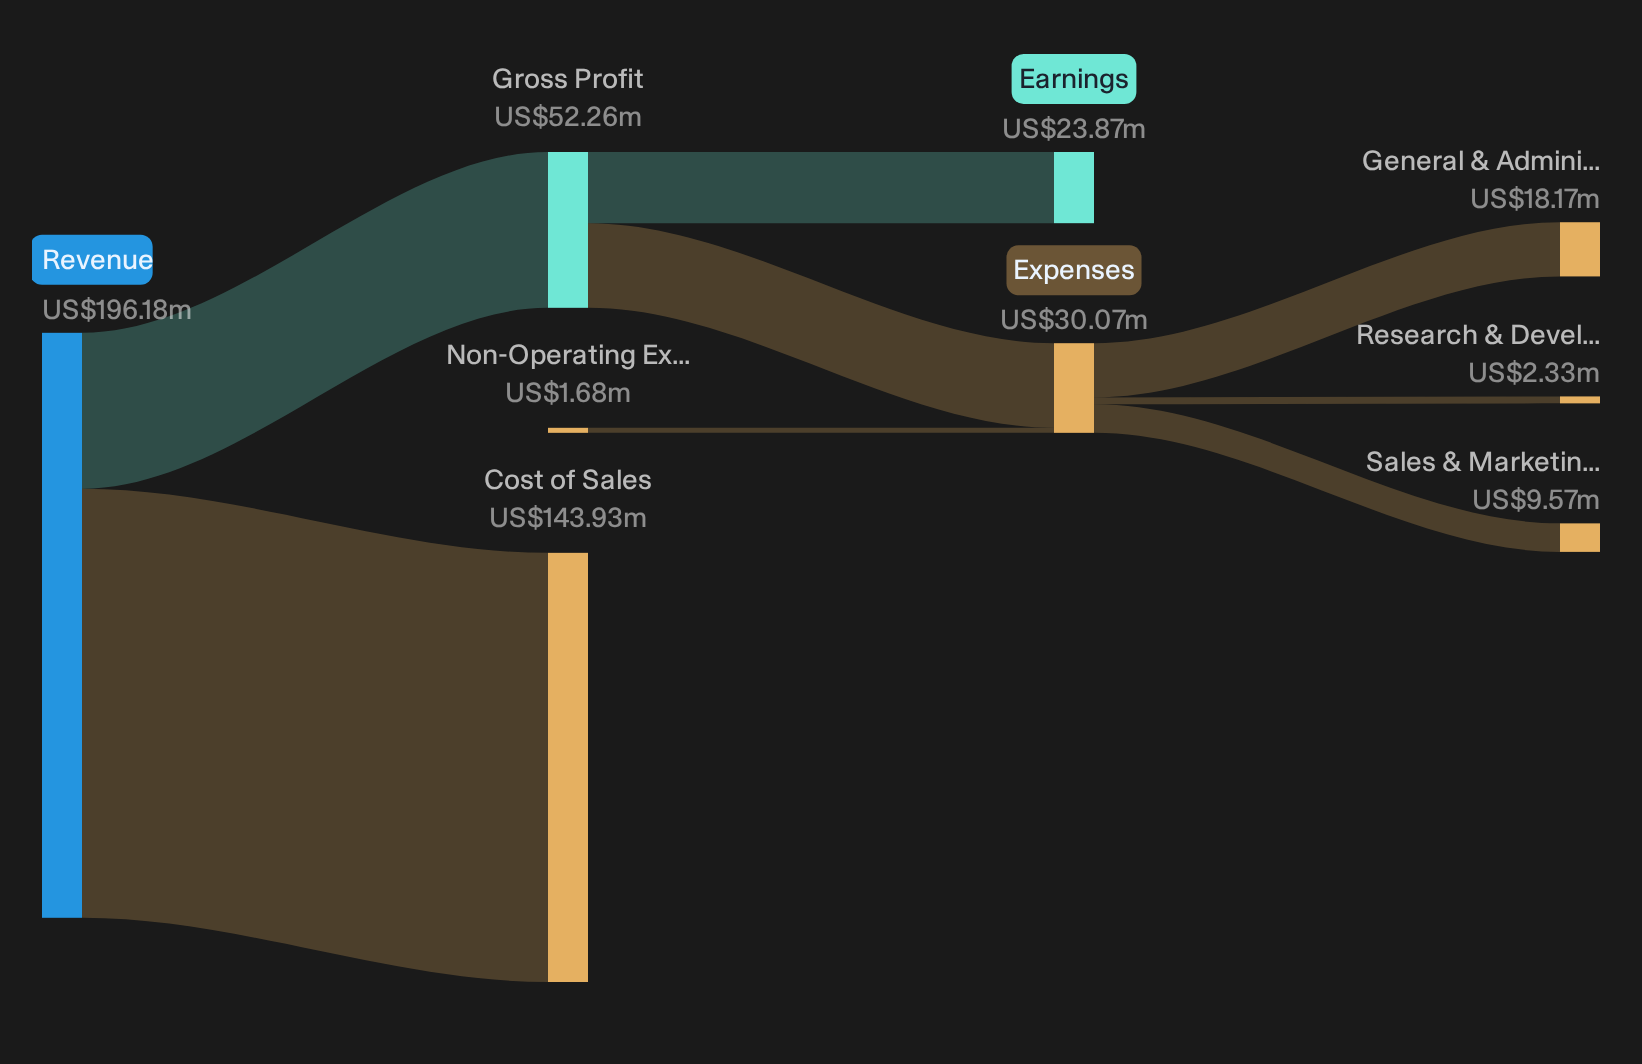
TAT Technologies came into this Q3 2026 earnings release with investors already leaning optimistic, after a 30 day gain of about 10% even before today’s move. The stock added another 3.7% to close at US$38.79, which might look like a routine relief rally on the surface. The raw numbers tell you why the reaction was stronger than that. Revenue reached US$55.6m and adjusted EBITDA climbed to about US$10.9m, turning margin expansion into the real story for this maintenance, repair and overhaul focused aviation player.
Impressed by TAT Technologies turning US$55.6m of revenue into US$10.9m of adjusted EBITDA and want more aviation and industrial stocks that mix healthy margins with solid balance sheets? Compare this quarter to our curated screener of companies with similar financial resilience in the list of solid balance sheet and fundamentals stocks (24 results).
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$55.6m vs. US$46.2m (up about 20%)
- Net Income (Excl. Extra Items, Q3 2026 vs. Q3 2025): US$7.7m vs. US$4.8m (up about 59%)
- Basic EPS (Q3 2026 vs. Q3 2025): US$0.59 vs. US$0.37 (up about 59%)
- Adjusted EBITDA Margin (Q3 2026 vs. Q3 2025): 19.6% of revenue vs. about 14% of revenue (profitability expanding faster than sales)
Margin Story Versus Backlog Reality For TAT Technologies
TAT Technologies is often framed as a backlog plus margin expansion story that depends on operational execution catching up with demand.
"The company's growing emphasis on operational efficiency, now supported by gross margin above 25% in Q2 2026 and 24.8% for the first half, shows that automation, expense discipline and process improvements are feeding through and can lift gross margin and EBITDA margin further, with a direct effect on operating income and net income."
Q3 confirms that efficiency push. Gross margin moved to 30.9% and adjusted EBITDA margin reached 19.6%. Backlog, however, eased from US$615m to US$577m after removing about US$34m of landing gear work, so execution is improving while the order book is being cleaned up.
Testing Supply Chain And Cash Strain Concerns
The bear side focuses on whether supply issues and working capital needs choke cash conversion even as TAT Technologies reports stronger profit metrics.
"Persistent supply chain constraints, including extended lead times on landing gear OEM parts that sometimes stretch beyond 12 months and earlier periods where about US$15.5m of APU and landing gear work was near completion but undeliverable, could keep delaying revenue recognition and increase input costs, which would weigh on margins and cash conversion."
Q3 results cut both ways. Management removed around US$34m of landing gear contracts from backlog and shifted capacity to higher margin APU activity, so the specific bottleneck is still visible. At the same time, record gross and EBITDA margins and net cash of US$42.6m indicate that, for now, those constraints are not eroding profitability or balance sheet flexibility.
One Narrative disagrees with today's price. → See where this Narrative says TAT Technologies should trade.
Hunt Quiet Disconnects In Plain Sight
TAT Technologies just showed how better execution can reshape the story ahead of market recognition. The real opportunity is tracking stocks that could be undervalued before any valuation gap narrows.
- Company 1 - 43% below our estimate - uses advanced cash recycling machines and branch-in-a-box setups to reduce reliance on teller-heavy branches for large banks.
- Company 2 - 38% below our estimate - ramps high horsepower engine capacity to align with data center power contracts while limiting exposure to newer energy ventures.
- Company 3 - 28% below our estimate - anchors critical chips and software that move, connect and secure data for large-scale cloud and enterprise infrastructure.
That is three of the list. See the full list of 34 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com