


EN
Cerus (CERS) Q3 Results Signal Profit Progress As Stock Stalls
Cerus just reported Q3 2026 and the stock barely flinched. Shares slipped about 0.8% today to US$2.34, a muted move for a blood safety specialist that just logged its 10th straight quarter of positive adjusted EBITDA and kept product revenue essentially flat at about US$57.7 million. The tape is treating this like a nonevent.
Fundamentals tell a different story. Losses narrowed to a small net loss of about US$0.6 million, product gross margin held in the low 50s, and operating cash flow turned positive. Price action looks cautious while the income statement quietly shifts closer to a sustainable profit profile.
If you appreciate the consistency in Cerus' adjusted EBITDA but remain concerned about its net loss on the bottom line, you can compare this situation with companies that already combine resilient earnings with cleaner balance sheets using our list of solid balance sheet and fundamentals stocks (24 results).
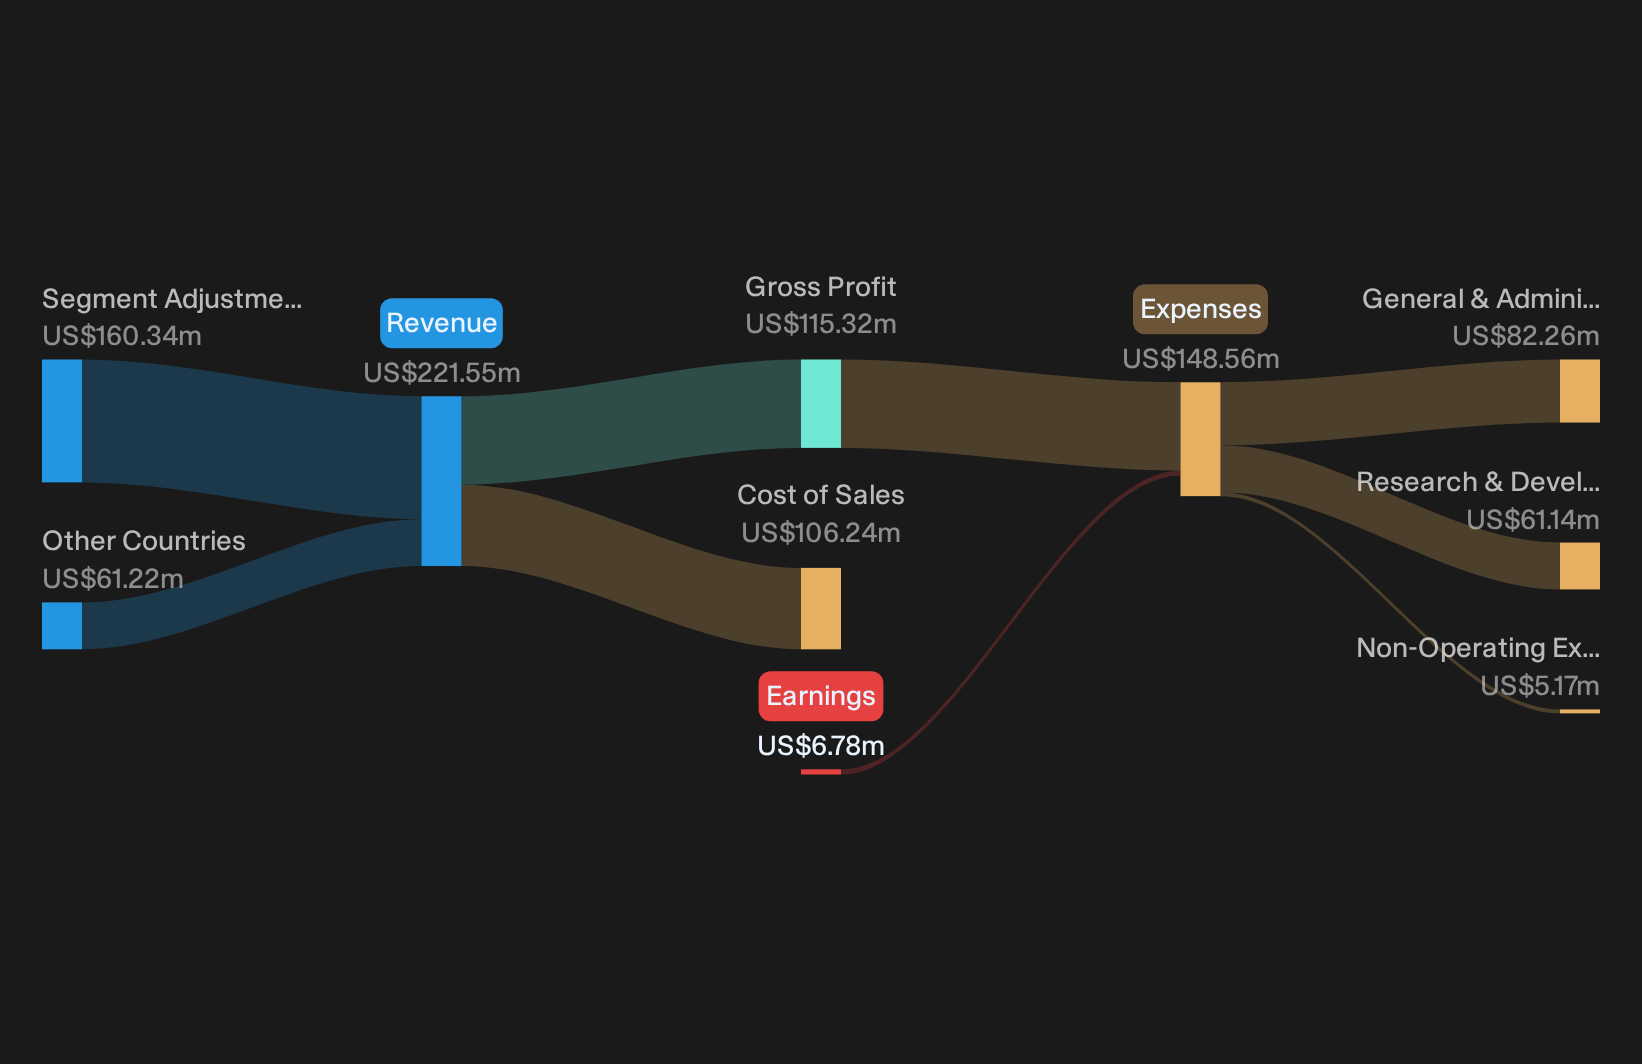
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$57.7 million vs. US$52.7 million (up about 9.5%)
- Net Loss (Q3 2026 vs. Q3 2025): US$0.55 million loss vs. US$0.02 million loss (loss widened modestly from a near breakeven base)
- Basic EPS (Q3 2026 vs. Q3 2025): US$0.0027 loss per share vs. near breakeven at roughly US$0.0001 loss per share (small move further into loss per share)
- Product Gross Margin (Q3 2026 vs. Q2 2026): 52.4% vs. prior quarter level in the low 50% range (sequential margin improvement despite FX and inflation headwinds)
Cerus finally has Phase 3 success for INTERCEPT-treated red cells. Ask Charlie what Cerus’ RedeS trial unlocks for red blood cells.
Cerus Bull Case Meets Real Operating Markers
Optimists argue Cerus can turn clinical traction into broader system usage and steadier cash generation.
"Expanding use of the INT200 illuminator and INTERCEPT platelets and plasma across EMEA, highlighted by the new multiyear contract with the French Blood Establishment that includes INT200 deployment, points to sustained demand for Cerus systems that can contribute to steadier revenue and better visibility on cash flows."
Q3 results give this view some footing. EMEA product sales moved higher despite FX and regional disruptions. Management also reported INT200 placements running ahead of internal plans. Combined with 10 consecutive quarters of positive adjusted EBITDA and fresh operating cash inflow, the contract-led system rollout is beginning to show up in the cash line, not just in slideware.
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there.
Cerus Bear Concerns On Adoption And Margins Under The Microscope
The key worry is that Cerus overpromises on new product rollouts while cost pressures quietly erode profitability.
"Although international contracts such as the multiyear agreement with the French Blood Establishment and the rollout of the INT200 illumination device provide medium term visibility, the need to complete device deployments and manage currency and inflation headwinds could restrict improvements in gross margin and delay any expansion in net margins."
Q3 data partly validates this caution. Product gross margin sits at 52.4% and is still below last year, so FX and inflation are not fully behind the company. Net loss remains, albeit small. At the same time, INT200 placements are tracking ahead of plan and adjusted EBITDA and operating cash flow are positive, which undercuts the idea that deployment risk is stalling the P&L altogether.
Find Quiet Dislocations Before Crowds
Cerus reported a stable quarter while the share price barely moved. The real opportunity is finding stocks that could be undervalued before the market corrects them.
- Company 1 - 38% below our estimate - use a major investment in power systems capacity to focus on higher return engine projects and integrated power solutions.
- Company 2 - 42% below our estimate - use expanded manufacturing capability to supply protective films and services into fast growing installer and dealership channels.
- Company 3 - 33% below our estimate - pursue rising data center demand by pairing advanced accelerators with an entrenched AI software ecosystem that customers already rely on.
Three companies from the same screener. Open the full list of 34 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com