


EN
Ethos Technologies (LIFE) Stock Price Slides After Q3 Earnings Cash Progress
Ethos Technologies walked into this Q3 2026 report with its stock on a strong multi‑month run, yet the first full trading day after the release has seen the share price fall about 4% to US$40.88. That pullback jars with the headline result. Revenue for the quarter reached US$235.2m and adjusted EBITDA came in at US$35m, numbers that sit at the center of the life insurance platform story investors have been paying up for.
The market is punishing a high‑expectation growth story in the short term, while the underlying earnings print looks more like a test of patience than a thesis breaker.
Love the Ethos Technologies growth story but concerned about paying up for a high expectation stock after a 4% pullback? Benchmark NasdaqGS:LIFE against a 30 resilient stocks with low risk scores if you want businesses with stronger downside resilience built into their fundamentals.
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$235.2m vs. US$93.8m (very large increase in quarterly revenue)
- Net Income (Q3 2026 vs. Q3 2025): US$4.7m vs. US$15.9m (quarterly profit declined)
- Basic EPS (Q3 2026 vs. Q3 2025): US$0.07 vs. US$0.96 (earnings per share fell sharply for the quarter)
- Adjusted EBITDA Margin (Q3 2026 vs. Q3 2025): 15% vs. prior year period not disclosed (management highlighted a 15% adjusted EBITDA margin as part of Q3 results)
Management says Ethos Technologies’ record quarter proves its growth is built to last. Ask Charlie what makes Ethos Technologies’ growth look durable.
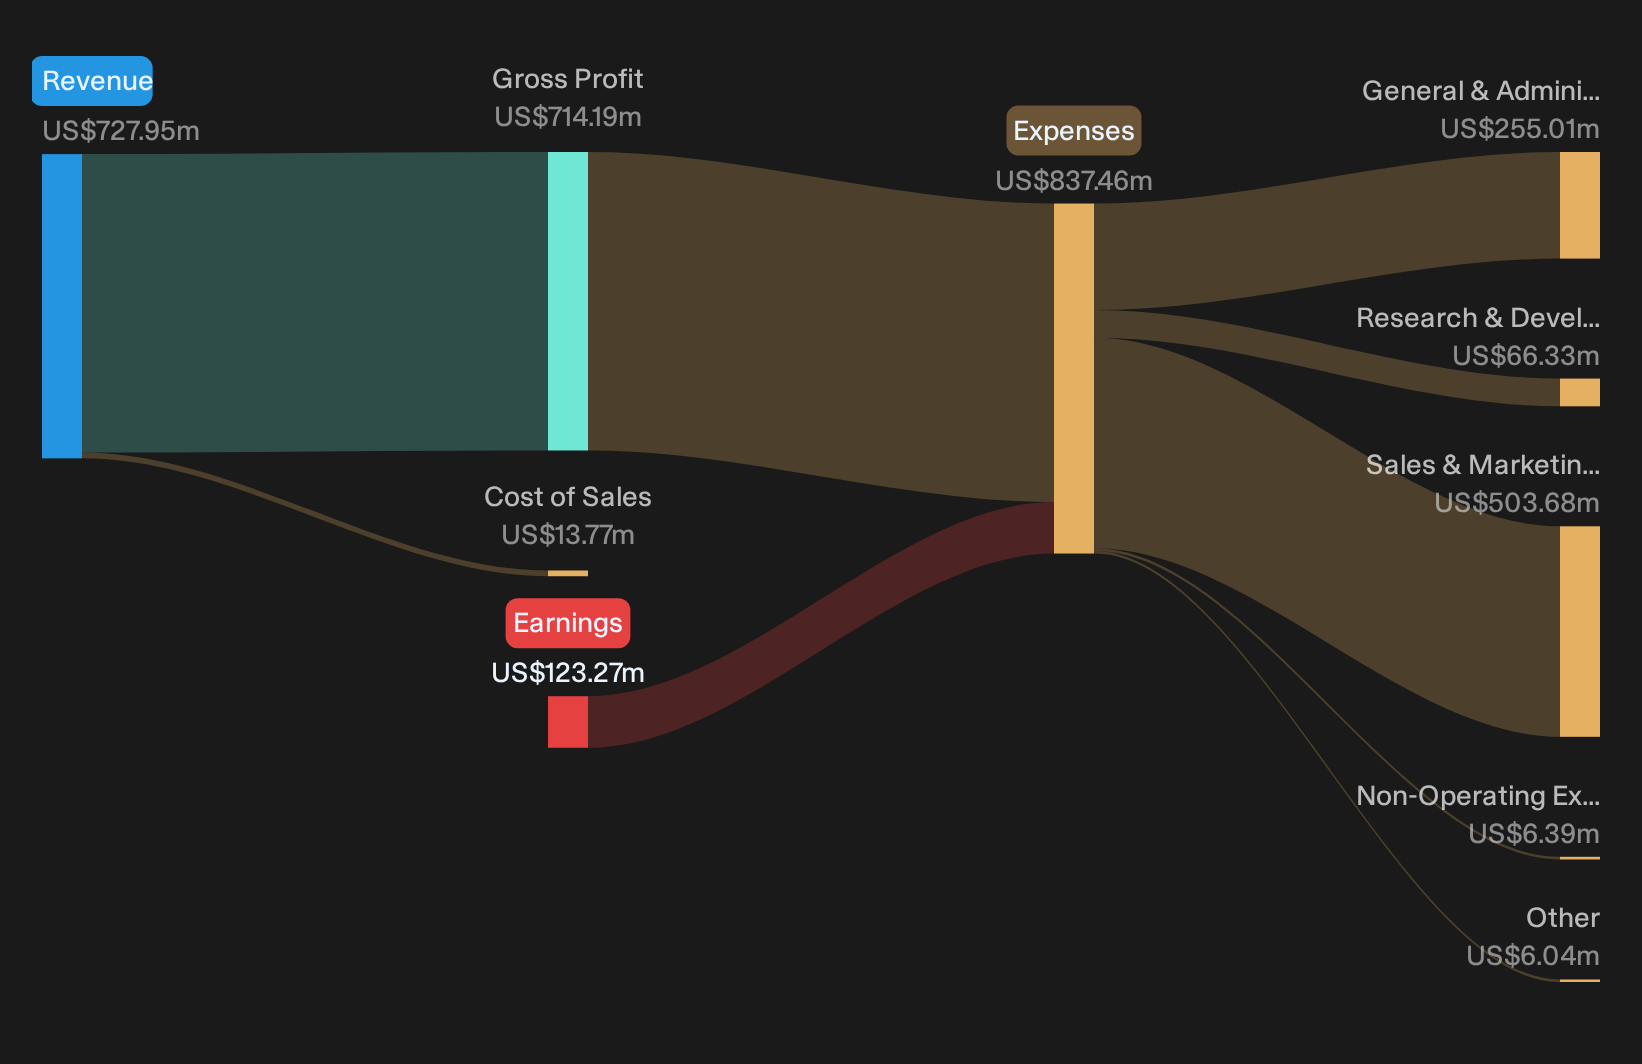
Ethos scale story meets first real cash test
The bullish script around Ethos Technologies hinges on scaling rapidly while keeping new business funding itself quickly. That ambition is clear in the thesis.
"Bullish analysts expect Ethos Technologies to keep scaling its vertically integrated life and protection platform across both direct and agent channels while remaining variable cash-flow positive on new business within about 60 days."
Q3 moves this from theory toward evidence. Revenue reached US$235.2m, with 142,111 policies activated, and contribution profit of US$66m. Operating cash flow was US$41m, which means reported cash generation exceeded adjusted EBITDA. For a scale story built on quick payback, that is an important milestone hit rather than just a marketing line.
That disagreement has a full argument behind it. → Uncover the lower Fair Value this Narrative argues for.
Ethos bearish risks meet a tougher margin reality
The more cautious view centers on fragile unit economics at Ethos Technologies rather than headline growth.
"Customer acquisition is heavily tied to advertising and agent recruitment, so rising media costs, weaker returns on marketing or slower agent onboarding could increase acquisition costs. This may soften contribution margins and adjusted EBITDA."
Q3 results partly echo that concern. Contribution margin sits at 28% and adjusted EBITDA at 15%, healthy but not expanding in step with very large revenue growth. A deliberate shift toward third party distribution and heavier brand spend supports scale, yet it also makes it harder to see clear evidence of structurally lower acquisition costs or stronger per policy profitability.
Hunt Fresh Dislocations Now
Ethos Technologies just showed how a single quarter can challenge a well-liked story without fully rewriting it. The real opportunity is finding stocks that could be undervalued before the market corrects them.
- Company 1 - 33% below our estimate - sells GPU platforms that hyperscale data centres use to retool server racks for AI workloads.
- Company 2 - 45% below our estimate - knits together acquired engine and component shops so airlines can source high margin repair programs from one aftermarket partner.
- Company 3 - 43% below our estimate - outfits stadiums, transit hubs and youth fields as they replace static signs with connected LED screens on software subscriptions.
Three companies from the same screener. Open all 34 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com