


EN
What Perseus Mining Holders Bought Into
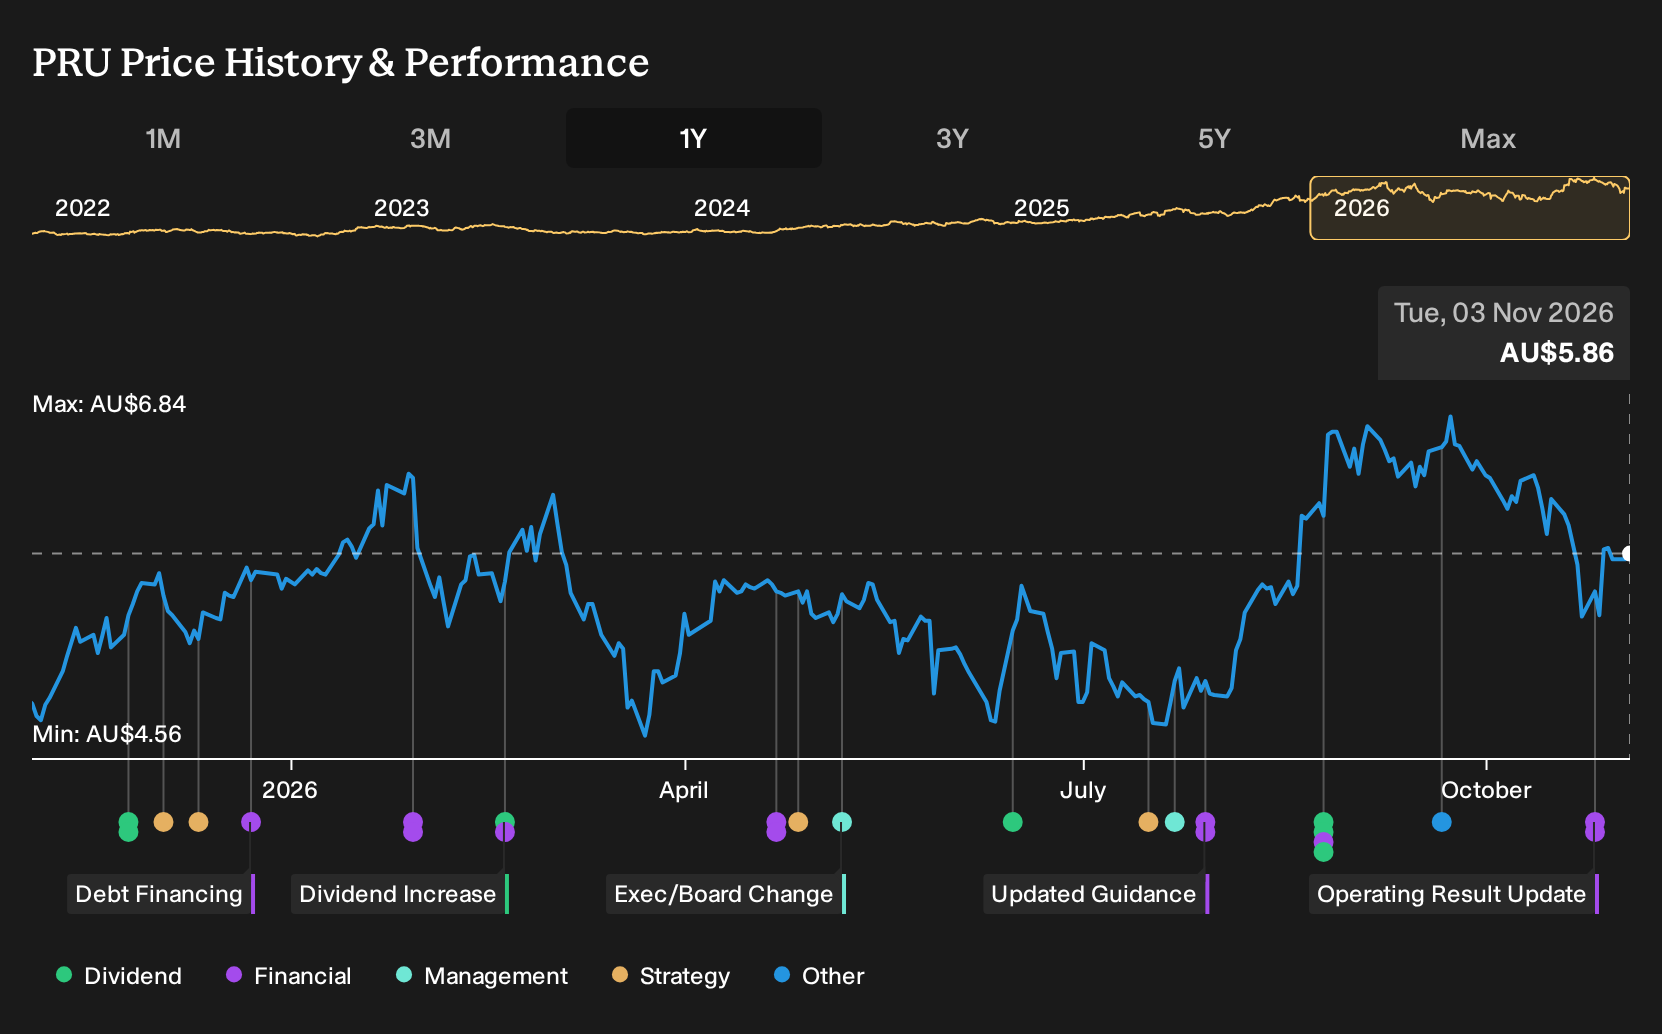
If you only skimmed the recent headlines about Perseus Mining’s richer ore reserves, rising cash pile, and expanded buyback, you might not expect the share chart to tell such a clean story. Investors who held Perseus Mining over the past year are up 27.4%, including dividends. If you had been weighing that November 2025 decision with only mixed analyst targets in hand, what exactly in the record would have justified taking that risk?
Narratives are how investors here put a case on the record, with explicit assumptions about revenue, margins and the multiple. Those assumptions imply an estimated Fair Value.
Perseus Mining is not the only name tied to this theme. Zero in on 34 elite gold producer stocks and compare how each one is priced.
The Argument You Would Have Been Weighing On Perseus Mining
The shares cost A$4.79 at the start of the period. Anyone looking at Perseus Mining then had to choose between two very different stories about what that price already assumed.
On the bullish side, the July 2025 Narrative put Fair Value at A$5.8, 21% above the start price. Supporters leaned on early delivery at Nyanzaga and CMA underground, as well as tight cost discipline, expecting stronger revenue growth and wider profit margins if elevated gold prices and safe haven demand persisted.
The October 2025 bear Narrative set Fair Value at A$4.26, 11% below the start price. This view still assumed revenue growth of 16.4% and a 31.6% profit margin, but focused on heavy reliance on gold prices, rising all in site costs and concentration in West Africa as key threats.
What The Results Changed For Perseus Mining
The clearest test for Perseus Mining came from its H2 2026 numbers. Revenue and net income were both higher than in H2 2025, and net margin moved from 28.9% to 30.2%. That outcome backed the optimistic case that assumed wider profitability, although it did not directly address the bear worries about regional concentration and cost pressure.
The takeaway for you is simple. When a story leans on better margins, check whether net income and the reported margin ratio actually move together over time, not just the top line.
What You Would Be Paying For Today With Perseus Mining
Perseus Mining now trades at A$5.86. The selected Narrative argues that its Fair Value sits below that level, because cost inflation and tighter royalty regimes could absorb more of the cash that growth projects generate.
To pay today’s price, you would be assuming new mines offset that pressure. The specific hurdle is that Nyanzaga, CMA Underground and other projects keep funding growth and buybacks even if West African royalties and fuel costs stay elevated.
"Key Takeaways: Bearish analysts expect Perseus Mining’s earnings power to be squeezed as higher West African royalties and fuel costs keep pressure on all-in site costs, despite a larger production base. The main thing that has to go right is that new and expanded assets like Nyanzaga, CMA Underground and the Edikan cutbacks deliver enough sustained cash flow to cover heavy FY27 growth and exploration spend, while still funding the enlarged capital returns program."
One Narrative has put a figure on that disagreement. → See the Narrative with its lower Fair Value, assumptions and all
Where Perseus Mining’s Theme Extends
Perseus Mining keeps you focused on gold, cash generation and mine lives. The same questions carry across to silver.
Gold projects respond to buyers seeking physical metal. Silver producers face many of the same impulses plus industrial demand.
One miner in that space is adding new assets and deepening exploration around existing shafts.
It also sells more bullion directly to customers, seeking to keep more value in house and smooth revenue swings.
If you are mapping Perseus’s risk and reward, this silver play offers a nearby yet different way to test conviction about precious metals.
The case is written up, with the assumptions it depends on. → Discover the silver company one Narrative values 118% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com