


EN
3 Canadian Dividend Stocks To Watch In November 2026
The Reserve Bank of Australia has pushed interest rates to 4.85%, the highest level since 2008, and that puts reliable cash income back in the spotlight for Australian investors. Higher borrowing costs punish overextended companies. They also shine a light on businesses that can still fund dividends comfortably. This article walks through three higher yielding dividend stocks from our quality screen that aim to combine income strength with discipline.
The three stocks highlighted here offer a compelling starting point if you want exposure to higher-yielding dividend powerhouses with well-covered, growing, and stable payouts. However, if you want the absolute best, these 3 dividend aristocrats stocks are the cream of the crop.
Sun Life Financial (TSX:SLF)
Overview: Sun Life Financial is a global insurer and asset manager that uses recurring premiums and fee income to support consistent dividend payments.
Operations: Sun Life Financial generates about CA$15.7b in Canada, CA$12.96b in the U.S., CA$7.7b from SLAM and CA$2.57b across Asia.
Market Cap: CA$62.8b
Sun Life Financial fits the Dividend Powerhouses theme because its core life and wealth franchises generate steady cash that can support a 3%+ yield. Recent business momentum illustrates how that income engine might continue to build.
"Strong growth in Asia individual insurance sales, with $875 million of quarterly sales and over $7 billion of contractual service margin in the region, supports the view that Sun Life Financial can keep expanding its addressable market and add new premium and fee income streams that feed into earnings growth."
What really matters next is how one unresolved pressure shapes the balance between that expanding fee pool and future dividend headroom.
That unresolved pressure is exactly what the full narrative for Sun Life Financial unpacks, separating short term noise from the longer term dividend capacity story.

Magna International (TSX:MG)
Overview: Magna International designs and supplies high volume automotive systems and components, including Power & Vision and Seating parts, to global vehicle manufacturers.
Market Cap: CA$24.3b
Magna International appeals to dividend-focused investors because its recurring contracts on everyday vehicle parts can translate into smoother cash generation that supports a 3%+ payout even through industry swings.
"Although Magna International credits operational excellence and Factory of the Future programs for roughly 150 bps of net margin uplift through 2025 and guides to around 200 bps by the end of 2026, rising DRAM costs that are only modestly embedded as unrecovered headwinds leave limited buffer if cost inflation broadens, which could cap future EBIT margin and earnings progress."
What really matters now is how a single cost pressure shapes the balance between improving efficiency and the dividend coverage investors rely on.
That trade off is exactly what the full narrative for Magna International unpacks, showing how Magna International could convert cost pressure into accelerating cash earnings resilience beyond near term margin headwinds.
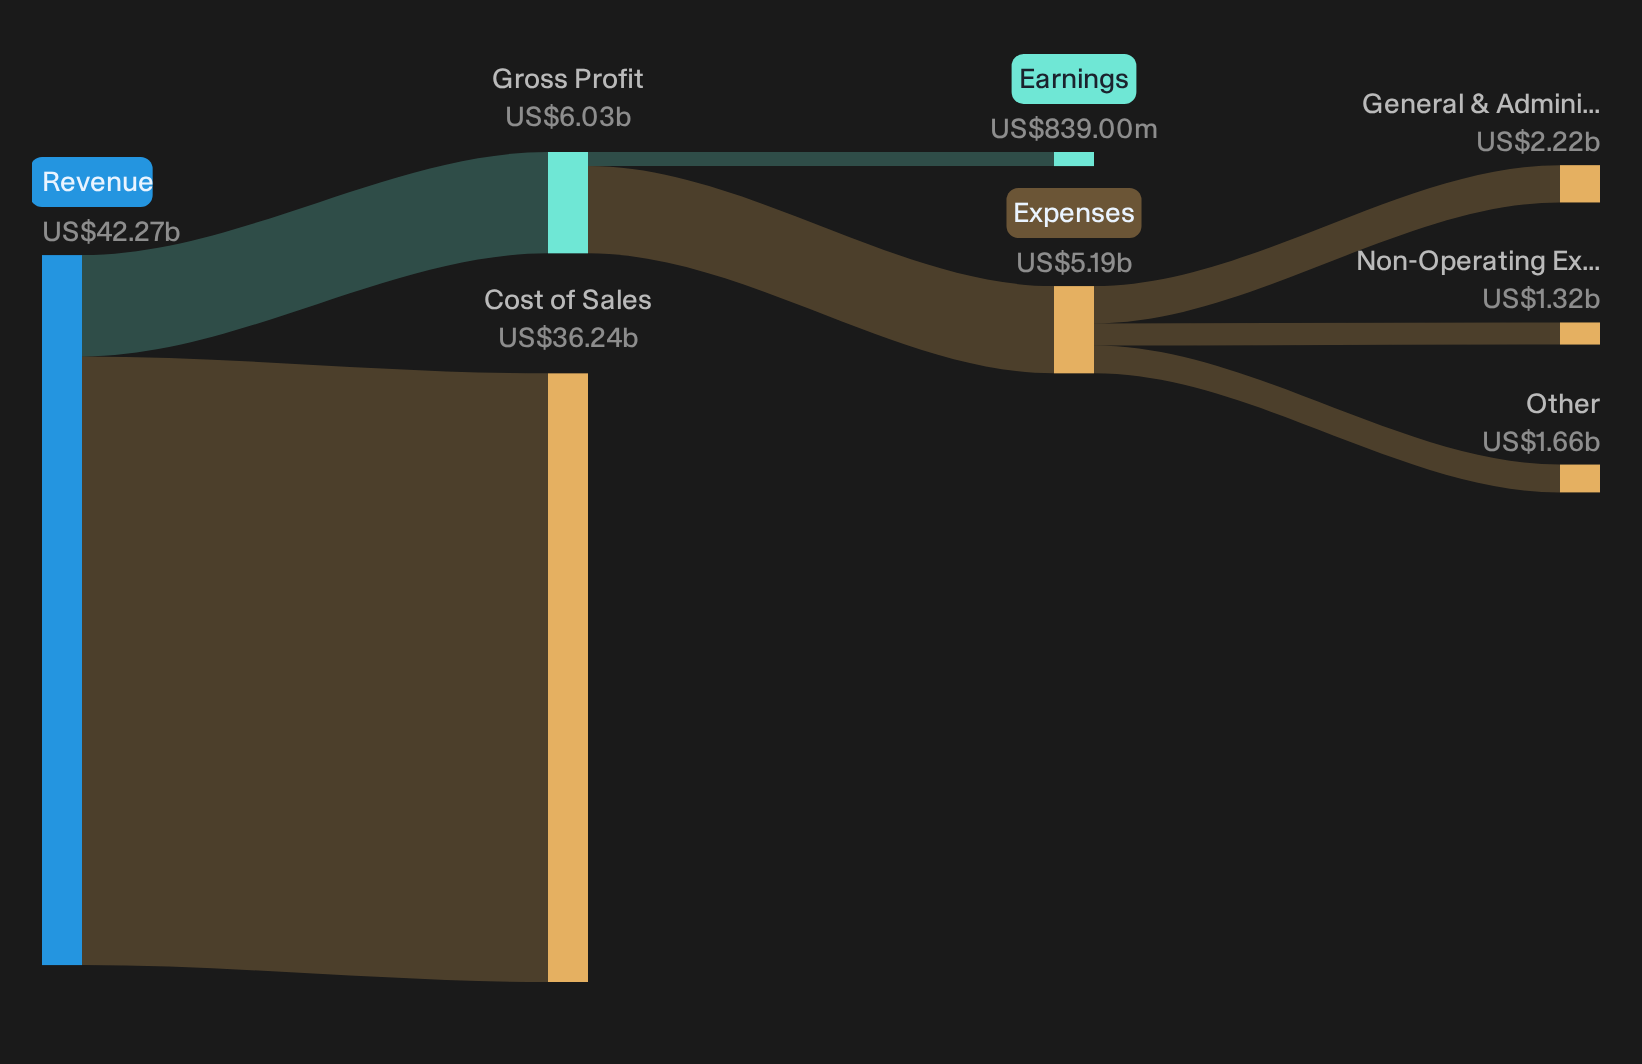
Bank of Nova Scotia (TSX:BNS)
Overview: Bank of Nova Scotia is a large North and Latin American bank providing everyday banking, lending, cards, wealth management and insurance services.
Operations: Bank of Nova Scotia generates about CA$11.9b from Canadian Banking, CA$9.6b from International Banking, CA$7.1b from Global Wealth Management, and CA$6.8b from Global Banking and Markets.
Market Cap: CA$160.1b
Bank of Nova Scotia fits the Dividend Powerhouses theme because its core Canadian and international retail and commercial banking arms generate steady earnings that support a 3%+ yield with room for measured dividend growth.
"Expansion of banking and wealth management services in Pacific Alliance markets such as Mexico, Peru, Chile and Colombia remains a live driver. International Banking revenue and loan growth in these regions and ROE above 16% point to further potential for fee income and earnings growth as Bank of Nova Scotia continues to deepen client relationships."
What really shapes the next leg of that dividend story is how one quiet shift in credit and capital demands feeds back into earnings consistency.
That quiet shift is exactly what the full narrative for Bank of Nova Scotia lays out in full, revealing how credit trends and capital demands could be decoupling from headline earnings momentum.

Seeking Fresh Alternatives Before They Fly
Some of the strongest future performers often move first, then get crowded fast. Track fresh ideas gaining quiet momentum while it matters and establish a position early.
- Target resilient compounders backed by strong cash generation and conservative balance sheets using the curated list of solid balance sheet and fundamentals (6 results) before the market fully catches on.
- Consider potential AI infrastructure trends as demand develops for the picks and shovels of compute, power, and cooling with the focused 53 AI infrastructure stocks while it remains less widely followed.
- Prepare for possible supply shifts and policy changes by scanning the hand-picked 34 elite gold producer stocks that could participate if interest turns back toward precious metals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com