


EN
Mistras Group (MG) Stock Shrugs Off Q3 Earnings Despite EPS Slide
Mistras Group just reported Q3 2026 results that quietly pushed earnings forward while the stock barely moved, with the share price ticking up only 0.2% to about where it started the week. The headline is simple: revenue reached about US$204.6 million and basic earnings per share came in near US$0.22, enough to keep trailing net profit margin at 2.8% rather than pointing to any clear squeeze.
For a company that trades on sentiment around small shifts in profitability, that muted one day reaction looks like a market still unsure how to price steady, if unspectacular, progress.
Like the gradual move in margins at Mistras Group, some investors prefer businesses with stronger profitability and sturdier balance sheets in the same broad quality bucket. If that is what you want to compare against MG, take a look at our list of solid balance sheet and fundamentals stocks (24 results)
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$204.6 million vs. US$195.5 million (up about 4.7%)
- Net Income, excl. extra items (Q3 2026 vs. Q3 2025): US$6.9 million vs. US$13.1 million (down about 47.0%)
- Basic EPS (Q3 2026 vs. Q3 2025): US$0.22 vs. US$0.42 (down about 47.5%)
- Trailing Net Profit Margin (latest vs. prior year): 2.8% vs. 2.5% (up around 0.3 percentage points)
Prefer clean visuals to another wall of earnings tables and margin figures? Get a full picture of Mistras Group, including its recent profitability trends presented in intuitive charts, inside the company report for Mistras Group.
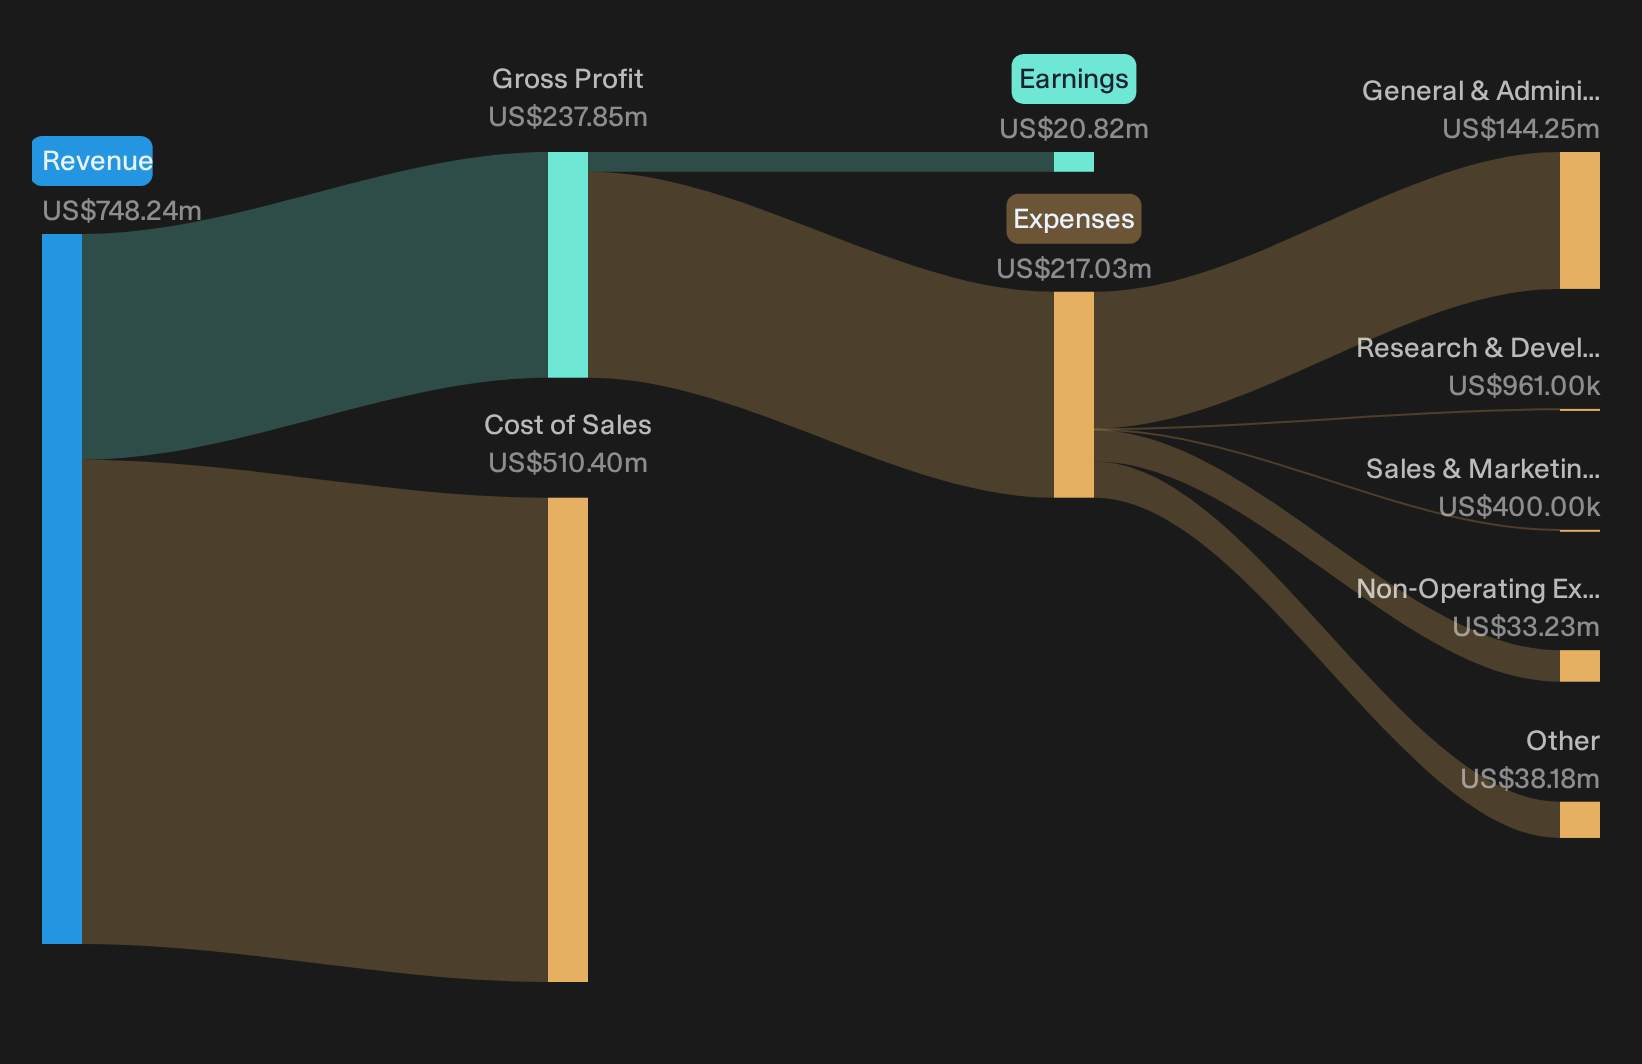
Mistras bullish mix shift meets softer earnings power
The upbeat narrative around Mistras Group rests on higher value software and lab work carrying more weight in the business.
"Mistras Group is positioned to capitalize on accelerating customer demand for integrated digital asset monitoring and predictive analytics, with recent double digit growth in PCMS asset integrity software and continued new customer wins and site expansions supporting higher margin software revenue and improved earnings quality."
Q3 revenue of US$204.6 million and a trailing net margin of 2.8% are consistent with some uplift in earnings quality. However, the 47% drop in quarterly EPS versus Q3 2025 shows that mix and software progress have not yet translated into stronger overall earnings power.
Bear case on oil and gas still visible in Q3
On the risk side, the key worry is that oil and gas drag could blunt the benefits of that mix shift.
"The earlier concern that Mistras Group faced prolonged softness and revenue declines in its core oil and gas sector remains live, as oil and gas revenue fell 11.5% year over year in Q1 2026 and 8.2% in Q2 2026, which could limit total revenue growth and put pressure on earnings if weakness or contract exits continue."
Q3 top line of US$204.6 million sits only modestly above the prior year while EPS roughly halved. This points to this concern still playing out and suggests that exits and weakness in traditional energy remain a real counterweight to the higher margin areas.
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there.
Hunt Quiet Disconnects In Plain Sight
Mistras Group just showed how earnings shifts and muted price moves can leave investors debating what really changed. The real opportunity is finding stocks that could be undervalued before the market corrects them.
- Company 1 - 45% below our estimate - focus on building a pure-play aviation aftermarket platform as new acquisitions and OEM partnerships reshape engine and component service volumes.
- Company 2 - 48% below our estimate - lean on a dense app-driven store footprint to turn spending on rentals, delivery and technology into stronger drink volumes per location.
- Company 3 - 43% below our estimate - sell integrated data center building block systems as large AI infrastructure buyers consolidate around modular server and storage solutions.
Three companies from the same screener. Open every one of the 34 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com