


EN
Healthpeak Properties (DOC) Stock Shrugs Off Q3 Earnings Guidance Lift
Healthpeak Properties just dropped its Q3 2026 scorecard and the stock barely flinched. Shares closed at US$19.56 on Tuesday, up only 0.4% on the day, even after the real estate investment trust lifted full year funds from operations guidance for the third time in 2026.
That muted reaction sits at odds with the core message. Adjusted funds from operations reached US$0.44 per share in the quarter, and management tightened the full year range to US$1.76 to US$1.78, while also raising same store cash net operating income guidance. The tape is treating this like a routine quarter. The guidance reset reflects a shift in expectations.
Like the funds from operations beat but uneasy that Healthpeak Properties barely moved after a third guidance bump in 2026? Compare this with a 34 high quality undervalued stocks that pairs upgraded outlooks with stronger price reactions.
Q3 2026 Earnings Summary
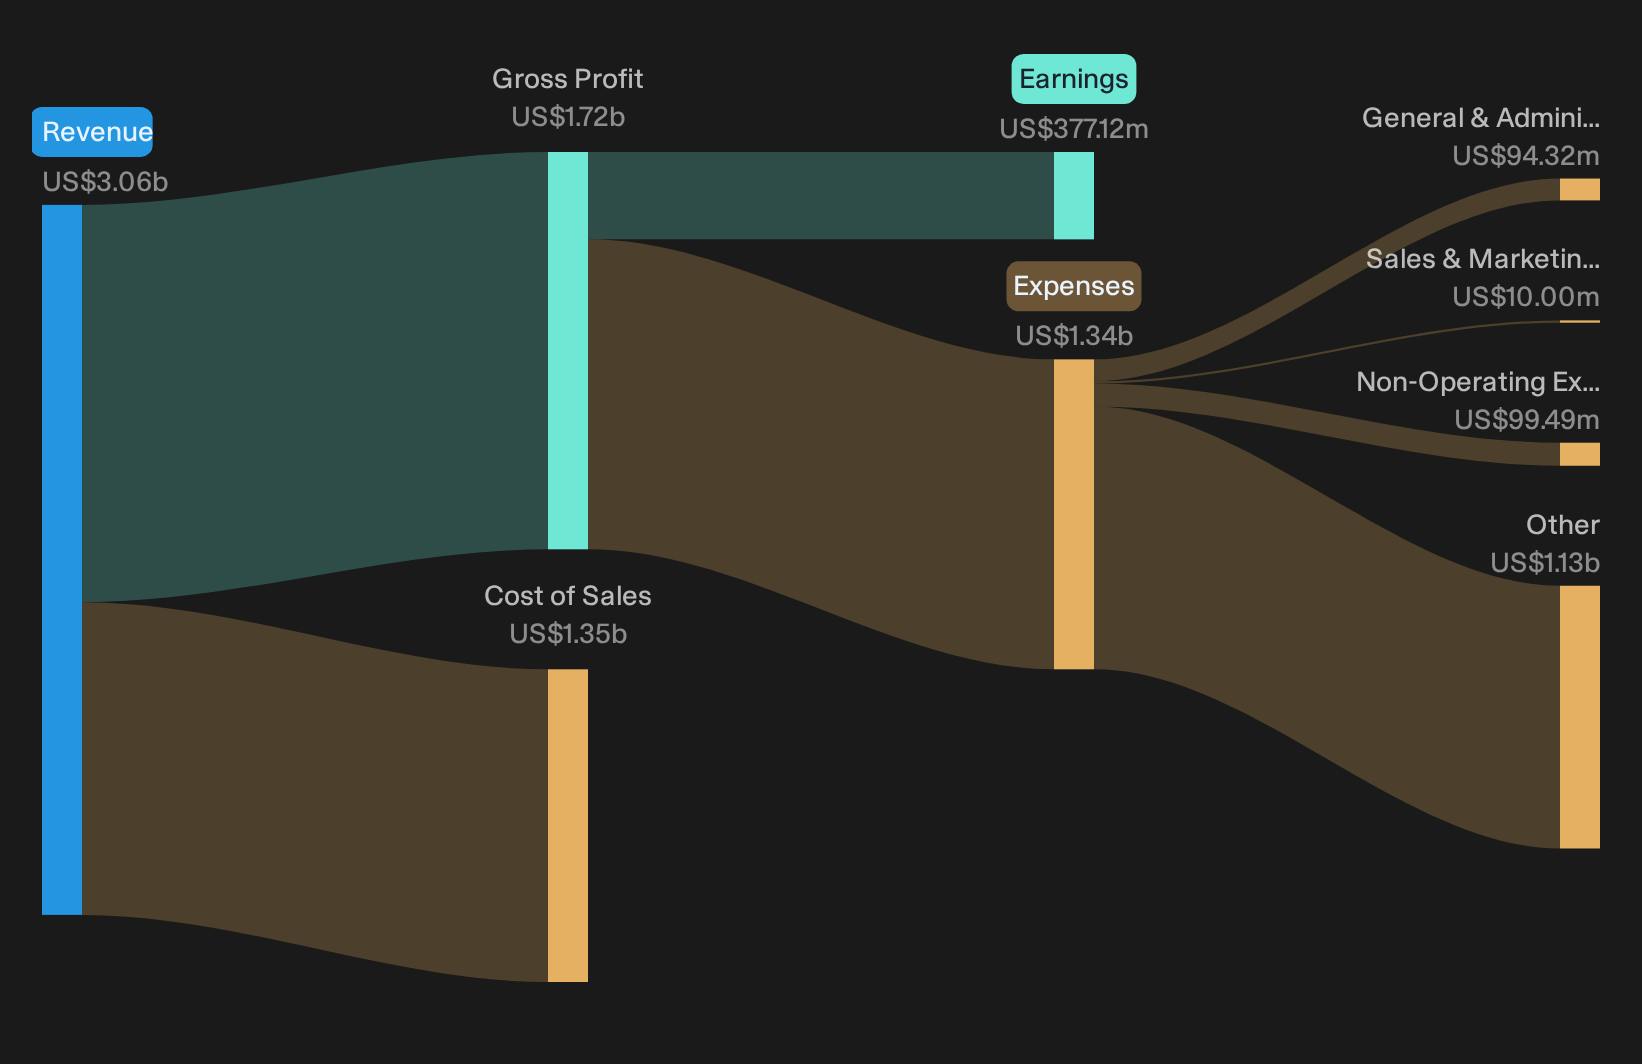
- Revenue (Q3 2026 vs. Q3 2025): US$820.9m vs. US$705.9m (up about 16.3%)
- Net Income (Excl. Extra Items, Q3 2026 vs. Q3 2025): US$17.1m vs. a loss of US$117.3m (returned to profit)
- Basic EPS (Q3 2026 vs. Q3 2025): US$0.02 vs. a loss of US$0.17 per share (moved back into positive territory)
- Funds From Operations (FFO, Q3 2026 vs. Q3 2025): Q3 2026 not disclosed at the headline level vs. US$318.2m in Q3 2025 (a direct quarterly comparison is not available, and investors are relying on management’s raised full year FFO guidance)
Healthpeak is buying half-empty lab buildings and guiding to big upside. Ask Charlie what makes Healthpeak confident in those 9–10% lab yields.
Evaluating Healthpeak’s Multi Engine Growth Ambition
The bullish script casts Healthpeak Properties as a three cylinder cash flow machine across outpatient, labs and Janus Living.
"Bullish analysts expect Healthpeak Properties to compound outpatient medical growth, life science leasing progress, and senior housing earnings from Janus Living into a larger, more diversified cash flow base that supports continued capital deployment."
Outpatient metrics line up with that vision, with about 5% cash re leasing spreads, over 3.2m square feet leased year to date and tighter same store NOI guidance. Life science is partway there, with occupancy moving toward 80% and the strongest leasing quarter in over a year, although same store NOI for labs is still guided to decline. Janus is the clearest milestone hit, with same store NOI up 26%, revenue up 78% and EBITDA more than doubling, plus heavy acquisition activity. Together with higher FFO guidance and 4.7x net debt to adjusted EBITDA, the diversified cash flow goal looks directionally supported, even if labs remain a work in progress.
The price and this Narrative do not agree. → Uncover what this Narrative says Healthpeak Properties is actually worth.
Healthpeak’s Bear Case: Lab Drag And Refinancing Risk
Bearish investors argue that Healthpeak Properties is one misstep away from stalled earnings once life science softness and higher interest expense fully bite.
"Although life science occupancy has moved higher with a pipeline of leases and letters of intent, the roughly 30% vacancy in the broader Route 128 West market suggests that renewed market level weakness or prolonged lease up periods could cap rental revenue growth and limit any uplift to earnings from acquisition led expansion."
Q3 shows this concern is not hypothetical. Lab same store NOI is still guided to decline 3% to 6%, even as occupancy approaches 80%. Management is buying partially vacant lab assets and underwriting a 2 to 3 year path to stabilization. That keeps execution risk firmly on the table just as US$650m of low coupon notes roll toward refinancing at higher rates, so the raised FFO guidance does not yet neutralize the downside scenario.
Hunt For Mispriced Earnings Stories
Healthpeak Properties shows how earnings changes may not align with immediate share moves. The potential opportunity is identifying stocks that appear undervalued before the market reassesses them.
- Company 1 - 31% below our estimate - taps broader workplace retirement programs and on site financial guidance to strengthen employer sponsored savings relationships.
- Company 2 - 48% below our estimate - uses dense store rollouts and a fully digital ordering model to turn urban coffee demand into recurring app based spending.
- Company 3 - 42% below our estimate - expands film manufacturing capacity and closer OEM partnerships to secure more protective installations at the vehicle point of sale.
Three companies from the same screener. Open all 34 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com