


EN
TOLI (TSE:7971) Stock Faces A Q2 Earnings Valuation Gap
TOLI came into this earnings season wearing the label of a low‑expectation, high‑yield building stock, trading on a modest 8.3x P/E and offering a 4.7% dividend. The market barely flinched at the Q2 2027 release, with the share price at ¥724 after the numbers hit. Yet the headline result was clear: quarterly net income reached ¥983 million on revenue of ¥27,998 million, and trailing net profit margin sat at 4.3%. The real story is the valuation gap investors are still pricing in despite those profit levels.
If you like the combination of a 4.7% dividend and a low 8.3x P/E on TOLI but want income ideas supported by similarly steady profit margins and balance sheets, scan the 28 dividend fortresses to compare this payout with other high-yield candidates.
Q2 2027 Earnings Summary
- Revenue (Q2 2027 vs Q2 2026): ¥27,998 million vs. ¥27,236 million (steady year on year top line)
- Net Income (Excl. Extra Items, Q2 2027 vs Q2 2026): ¥983 million vs. ¥711 million (higher quarterly profit level)
- Basic EPS (Q2 2027 vs Q2 2026): ¥17.32 per share vs. ¥12.21 per share (EPS improvement)
- Trailing Net Profit Margin (TTM, Q2 2027 vs Q2 2026): 4.3% vs. 3.5% (margin uplift over the past year)
Strong earnings growth and a rich dividend contrast with TOLI’s low P/E. Ask Charlie what keeps TOLI’s low P/E this far below peers.
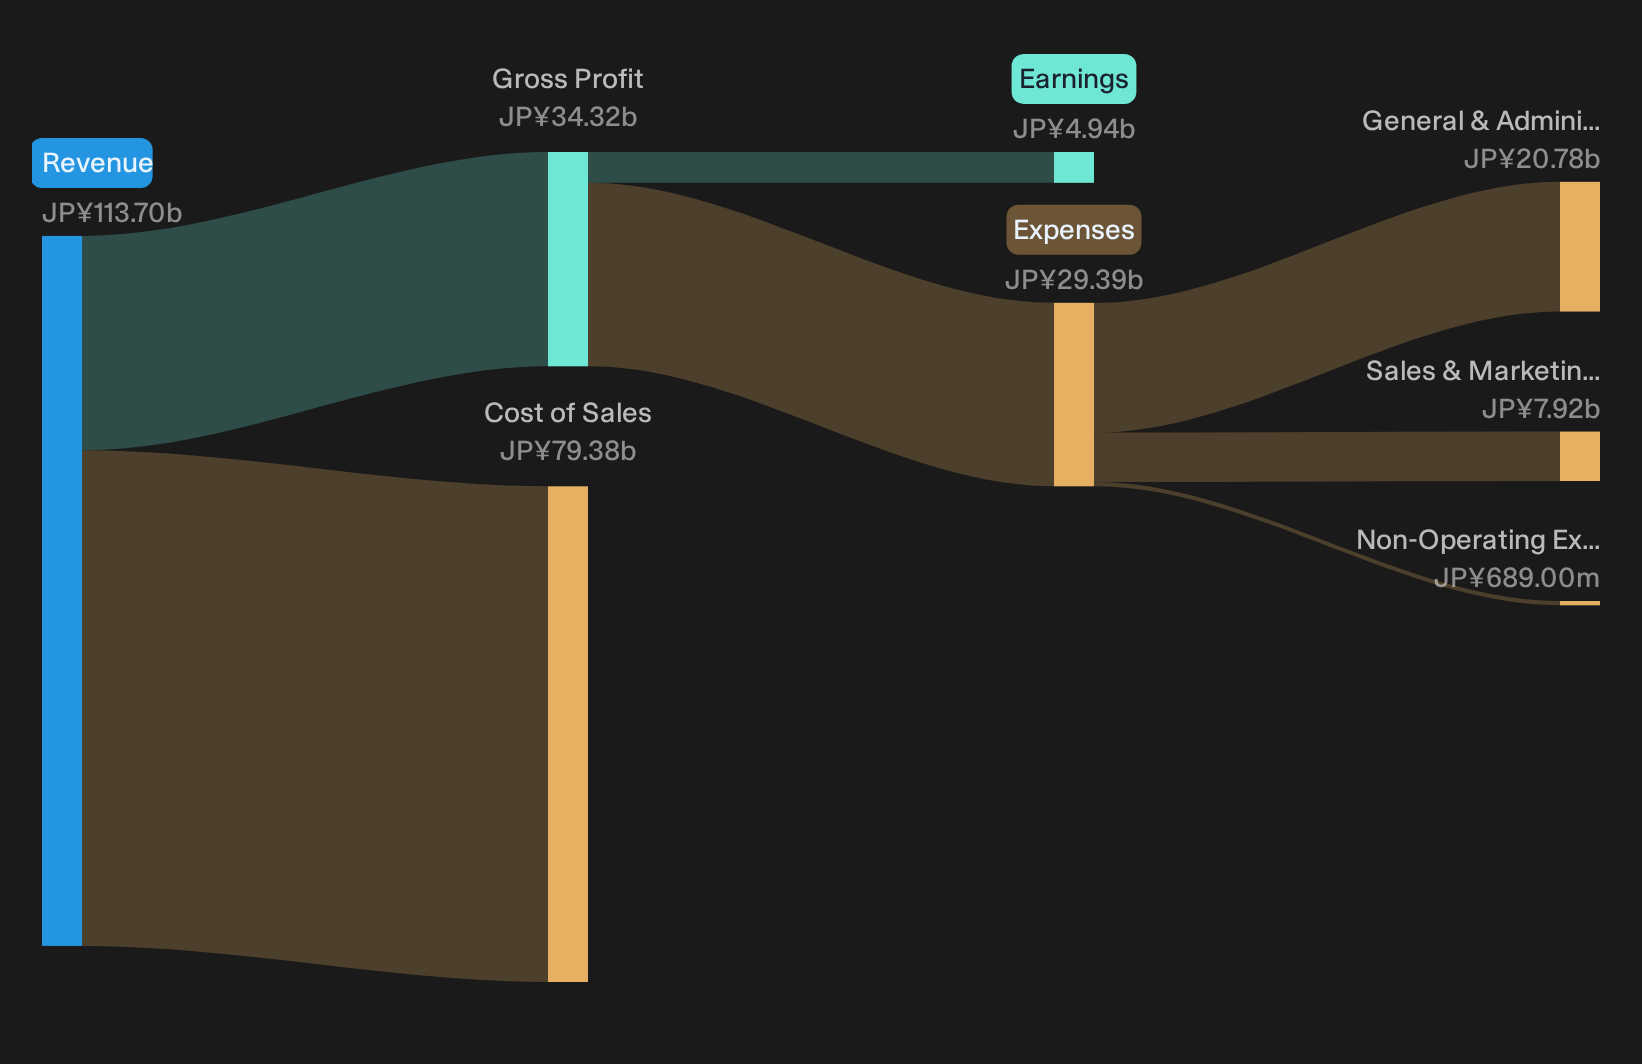
TOLI earnings reinforce steady-cycle optimism
TOLI looks closer to a “steady operator” than a struggling cyclical right now. Revenue of ¥27,998 million alongside higher quarterly earnings and a 4.3% trailing net margin points to an interior materials business that is holding its ground even as construction sentiment stays muted. The ongoing share buyback plan running through December 2026 also signals management confidence in the balance sheet and cash generation. This supports the view that this is a measured way to get exposure to renovation and building activity rather than a binary construction bet.
Risks to the TOLI story still visible
The numbers do not erase the cyclical question mark around TOLI. Results still tie directly to building and refurbishment demand, so any slowdown in projects or delayed renovations could pressure the 4.3% margin and profit base. The muted share price reaction around ¥724 hints that investors are not treating this as a clear breakout story despite the earnings improvement. The buyback helps offset some downside risk, but it does not fully shield the business from weaker order volumes or tougher pricing in flooring and wall coverings.
With earnings growth and a 4.7% dividend pulling investors in, the real question is whether TOLI’s balance sheet quietly supports that story. Check the financial health analysis of TOLI stock to verify liquidity, leverage and cash coverage.Hunt For Quiet Balance Sheets
TOLI reports a steady quarter and a muted share reaction that draws attention to balance sheet strength. The real opportunity is spotting stocks that could be low debt before the market corrects that view.
- Company 1 - 17% below our estimate - adds maintenance salespeople to win recurring contracts and pack more elevators into each service route.
- Company 2 - 40% below our estimate - leans on AI hiring tools and marketing platforms that turn job posts and local service searches into higher fee revenue.
- Company 3 - 48% below our estimate - pushes an AI-first security platform and subscription model that convert heavier cloud spending into expanding recurring protection contracts.
Those are three of them. See all 22 companies with the balance sheet to back it up →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com