


EN
Topaz Energy (TSX:TPZ) Can Q3 Earnings Sustain Its Premium Valuation?
Topaz Energy came into this Q3 2026 report wearing the label of a high margin royalty player with a P/E of 27.8x and a share price that had slipped about 3.4% over the last week. The market closed today at CA$29.62, treating the latest numbers as a mild reset rather than a breakout.
The print itself was quieter than the reputation. Q3 revenue of CA$87.19 million and basic EPS of CA$0.21 landed against a still strong trailing net profit margin of 43.8%. For holders, the story is less about a single quarter and more about whether that rich profitability still justifies the multiple.
If you like the high margin profile at Topaz Energy but are uneasy about paying a 27.8x P/E for it, check out our screener of stocks with strong profitability and sturdier valuation support in the 4 high quality undervalued stocks.
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): CA$87.19 million vs. CA$76.44 million (about 14.1% higher year on year)
- Net Income (Excl. Extra Items, Q3 2026 vs. Q3 2025): CA$32.02 million vs. CA$11.36 million (a very large year on year increase, close to 3x)
- Basic EPS (Q3 2026 vs. Q3 2025): CA$0.21 vs. CA$0.07 (around 184% higher year on year)
- Net Profit Margin (TTM to Q3 2026): 43.8% (reported as lower than the margin a year ago but still indicating high profitability for Topaz Energy)
Prefer visual charts instead of scrolling through another wall of earnings figures and valuation ratios? Get a clear, at-a-glance view of Topaz Energy's valuation profile in the full company report for Topaz Energy.
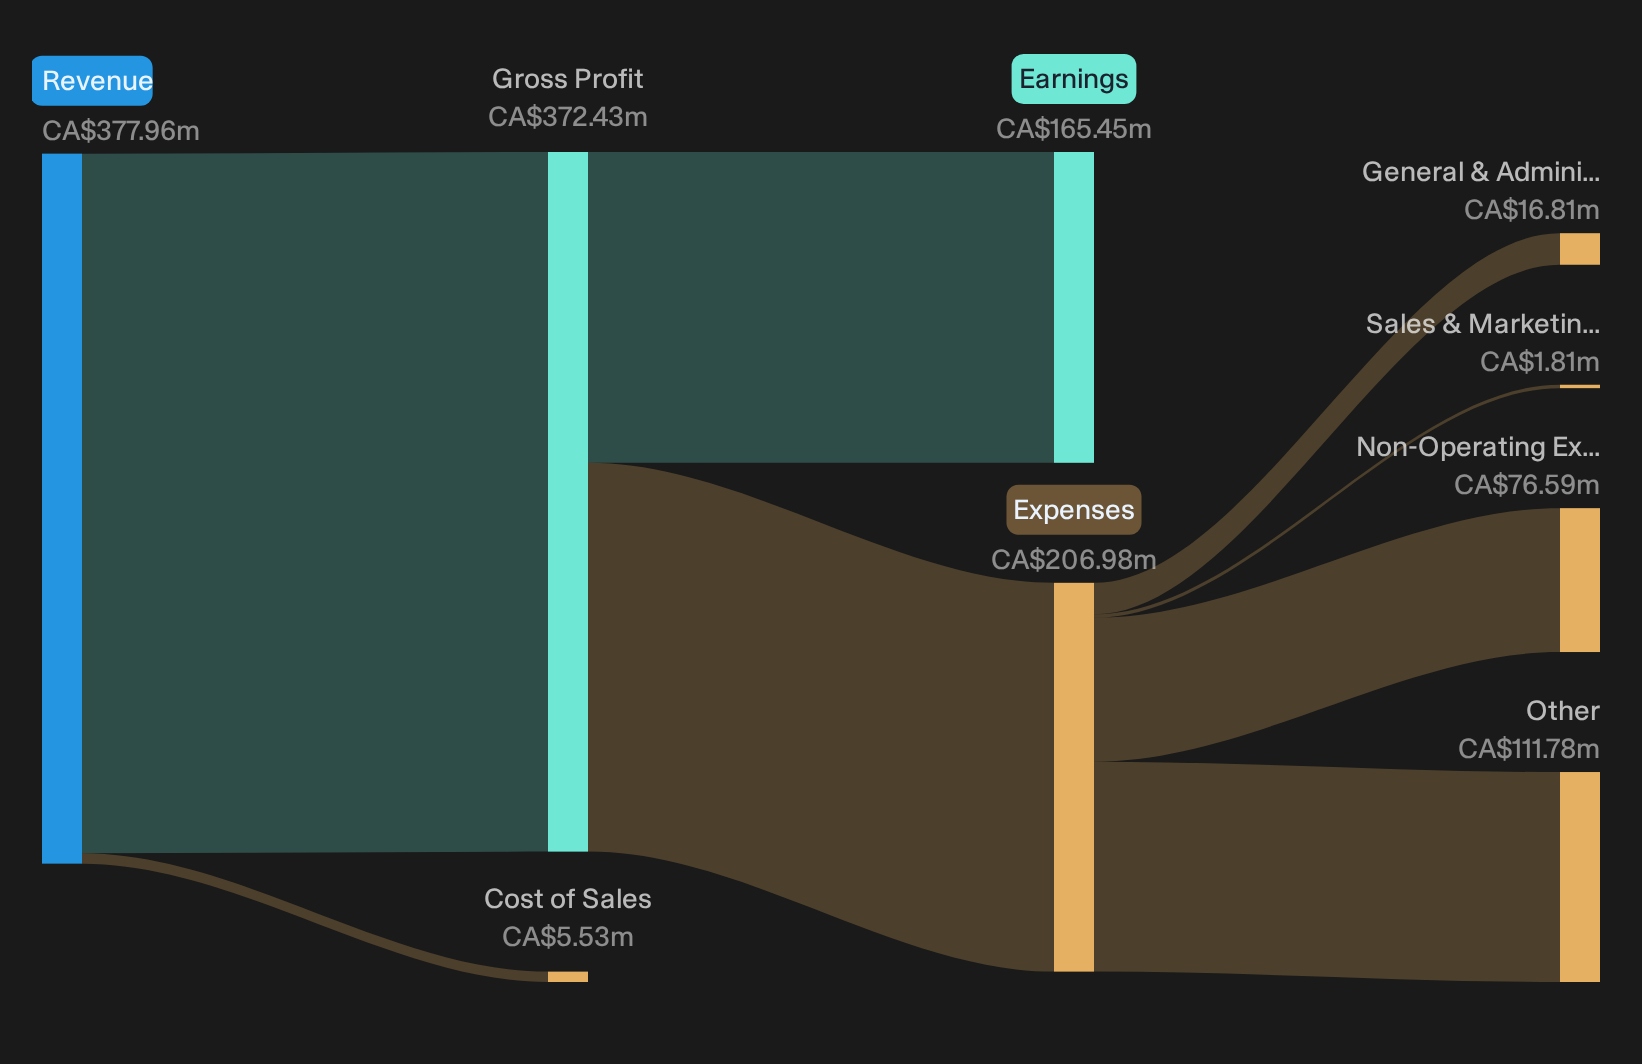
Topaz bullish story: royalties and pipes under scrutiny
Supporters argue Topaz Energy can lean on its structure to keep cash coming through cycles.
"Analysts expect Topaz Energy to keep leaning on its asset light royalty and infrastructure mix to support resilient cash flow and dividends, even through commodity swings."
Q3 tells a mostly supportive story. Royalty production rose 9% year on year and revenue reached CA$87.19 million, while net profit margin on a trailing basis stayed high at 43.8%. The dividend was held at CA$0.35 per share and 2026 guidance for royalty volumes and infrastructure processing revenue was reaffirmed, which points to this model largely doing what the narrative asked of it so far.
Bear case on balance sheet and payouts under test
Critics worry that funding growth and dividends might stretch Topaz Energy if cash generation cools.
"Net debt of $497.4 million at the end of Q2 2026, combined with ongoing acquisition spending and a target to finish 2026 with net debt in the $435 million to $440 million range before any additional deals, could limit flexibility if cash flow growth slows."
Q3 numbers partly push back on that concern. The company reaffirmed guidance and now expects to exit 2026 with net debt slightly lower at CA$425 to CA$430 million while keeping the CA$0.35 per share dividend. That suggests acquisitions and payouts are still being funded within existing balance sheet guardrails rather than forcing higher leverage today.
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for.
Hunt Quiet Disconnects In Plain Sight
Topaz Energy just showed how a rich profit profile can come with a mixed share price reaction. The real opportunity sits in spotting stocks that could be undervalued before the market closes the gap.
- Company 1 - 46% below our estimate - uses premium mall expansion and stronger omnichannel tools to deepen spending by loyal shoppers.
- Company 2 - 30% below our estimate - turns index inclusion and long contract wins into steadier fee income across integrated platforms.
- Company 3 - 32% below our estimate - leans on fast-payback boutiques and an expanding online app ecosystem to lift shopper engagement.
Those are three of them. See every one of the 4 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com