


EN
Williams (WMB) Q3 Earnings Hint At More Than A Routine Stock Gain
Williams Companies cleared another quarterly hurdle for Q3 2026, yet the emotional read in the market is only mildly upbeat. The stock closed at US$72.47, up 1.8% on the day. This is a muted reaction for a pipeline operator reporting record quarterly adjusted earnings before interest, tax, depreciation and amortisation of US$2.04b and tracking toward the upper end of its full year guidance.
Short term traders appear content to price this as a routine win. The operational story tells something louder. Contracted midstream cash flow and expanding project economics are carrying more weight than the modest one day share move suggests.
If you like how Williams Companies is reporting record adjusted EBITDA and want to explore other infrastructure plays with a similar contracted cash flow profile, scan the list of solid balance sheet and fundamentals stocks (23 results) for a benchmark set of peers built on comparable balance sheet strength and fundamentals.
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$3,223 million vs. US$2,867 million (up about 12%)
- Net Income, Excluding Extra Items (Q3 2026 vs. Q3 2025): US$699 million vs. US$646 million (up about 8%)
- Basic EPS (Q3 2026 vs. Q3 2025): US$0.56 vs. US$0.53 (up about 7%)
- Adjusted EBITDA (Q3 2026 vs. Q3 2025): US$2.04 billion vs. US$1.92 billion (up 6%)
Tired of scrolling through dense earnings tables and raw figures for Williams Companies? See the full story in a visual format, with a clear view of its valuation picture in the company report for Williams Companies..
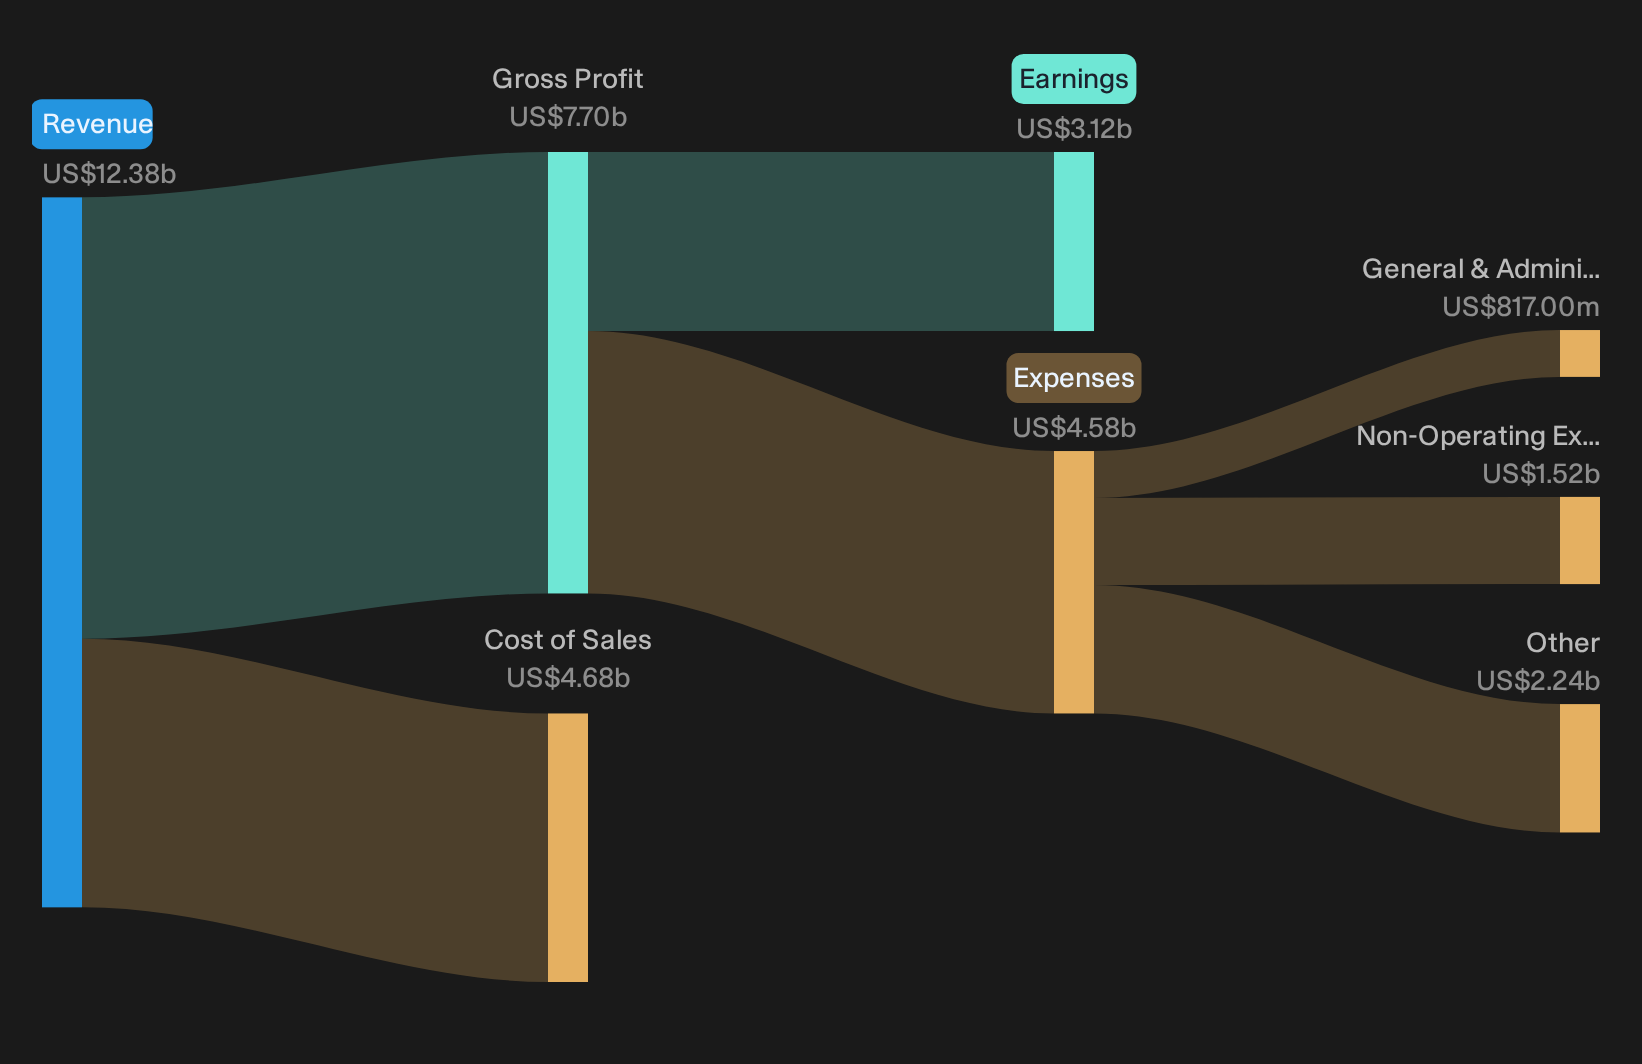
Evaluating Williams Companies’ Power And Corridor Ambitions
The bullish story hangs on Williams Companies turning big-ticket projects into reliable, contracted earnings rather than just headline promises.
"Rapid execution on behind the meter projects such as the 200 megawatt Phase 1 of Socrates entering service in under 18 months on time and within budget creates a template for faster deployment of future data center focused facilities, which can accelerate the ramp of contracted revenue and EBITDA."
Q3 results give that idea some backing. Record adjusted EBITDA, transmission and power leading segment contribution, multiple fully contracted pipeline expansions, and Socrates Phase 2 coming online ahead of schedule all point to real milestones hit, not just a marketing slide. The 8% profit increase aligns with that execution story.
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for.
Williams Bear Case: Execution Risks Versus Delivery
Bearish views on Williams Companies hinge on the idea that execution or demand shortfalls will turn today’s backlog into tomorrow’s headache rather than tomorrow’s cash flow.
"Any combination of construction delays, higher than expected leverage around the stated 4x ceiling or slower ramp on projects such as Neo and Silver Spur would challenge assumptions embedded in the current valuation and could leave future cash flow and dividend growth below what investors are currently modeling."
This quarter does not show those cracks. Socrates Phase 2 is early, Momentum Midstream closed ahead of schedule and is contributing, and several Transco expansions are already in service. Leverage is guided to about 3.75x, which sits inside the 3.5x to 4x target band, not above it.
Hunt For Mispriced Cash Flows
Williams Companies delivered a steady earnings story that drew a muted share reaction. The real opportunity could sit in stocks where cash generation and market pricing appear misaligned.
- Company 1 - 25% below our estimate - leans into AI focused data center capacity tied to advanced photonics and packaging programs.
- Company 2 - 45% below our estimate - moves from basic assembly toward co-designing complex hardware platforms embedded in medical, automotive and industrial systems.
- Company 3 - 23% below our estimate - ties testing equipment and engineered components to grid modernization, aerospace programs and diagnostics used by utilities and renewable operators.
Three companies from the same screener. Open the full list of 35 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com