


EN
3 High Growth Stocks To Own In November 2026
Former IMF economist Gita Gopinath is warning that interest rates may stay higher for longer as inflation proves sticky, which puts a premium on businesses that can grow earnings without relying on cheap money. That is where financially solid companies with strong profit growth potential start to look compelling. This piece breaks down three stocks from this high quality growth pool that could suit investors hunting for future earnings power.
The three stocks highlighted here offer a compelling starting point if you want exposure to financially solid high growth potential businesses that focus on building earnings rather than cheap credit. However, if you want the standouts, these 83 best high growth potential stocks are the most outstanding.
DoorDash (DASH)
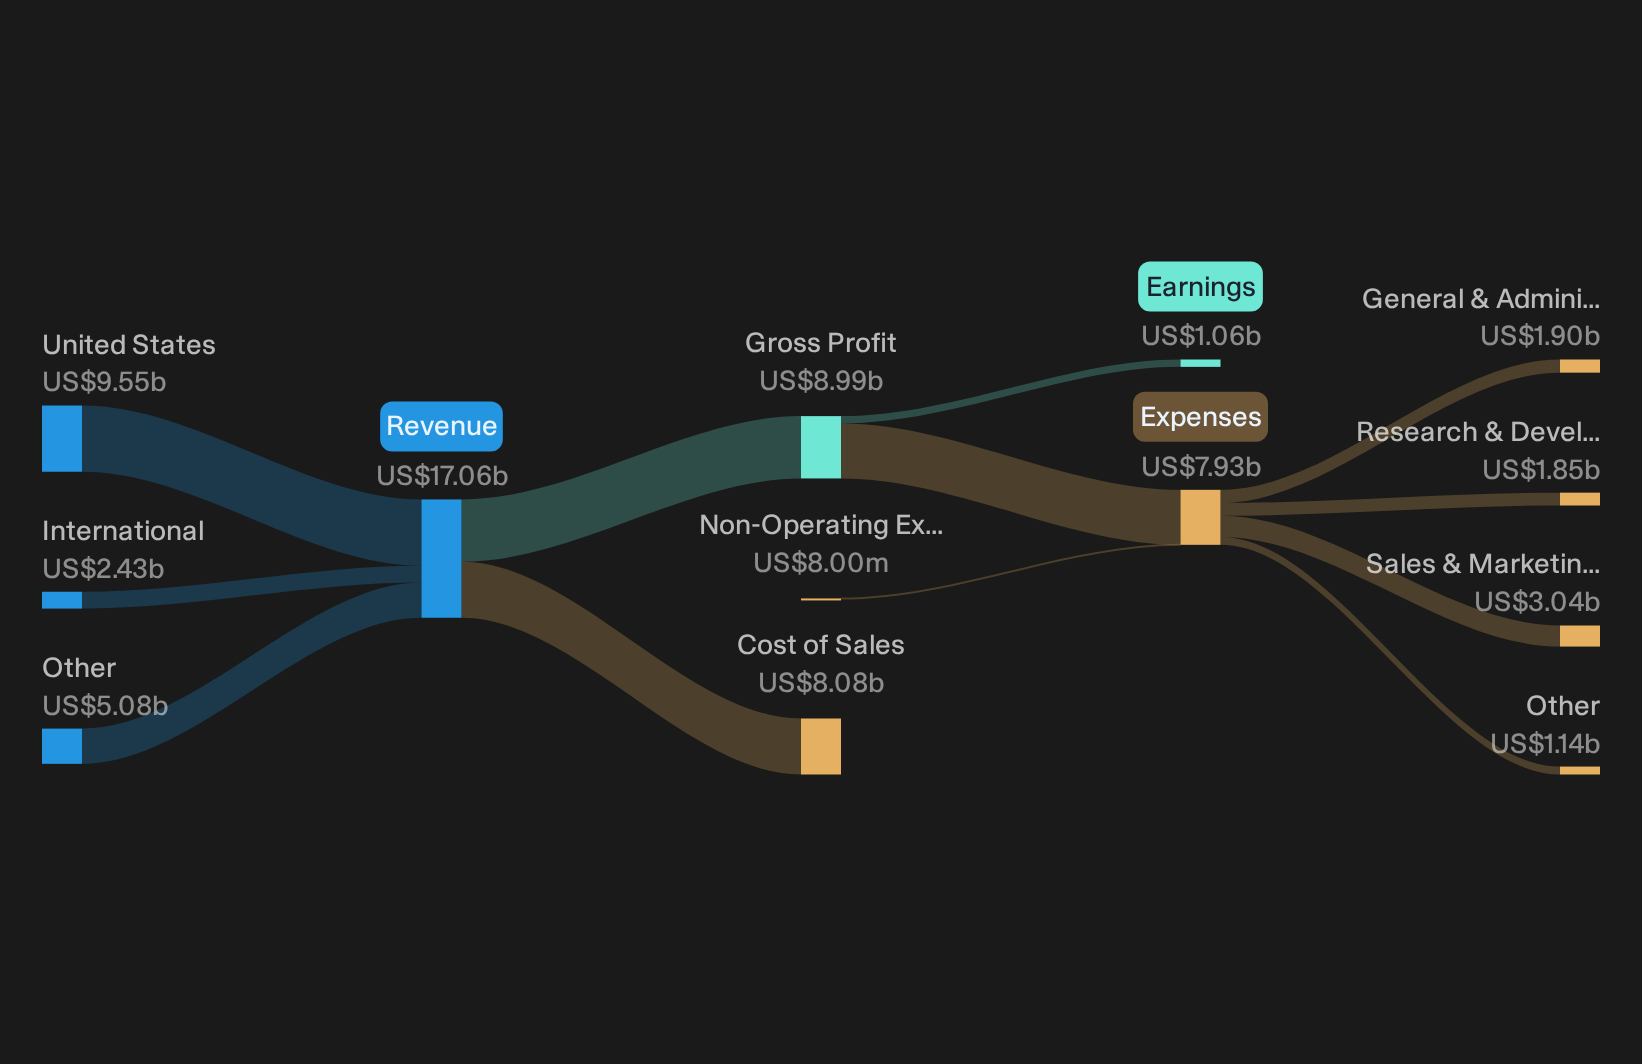
DoorDash runs an online delivery and software platform that connects restaurants, retailers, and consumers, with its Marketplace and subscription ecosystem central to the Healthy high growth potential theme. It generated about US$17.1b from internet information services and carries a roughly US$82.9b market value.
For this screener, DoorDash matters because the Marketplace, subscriptions, and advertising engine is built for compounding earnings rather than relying on cheap financing. Yet the way management chooses to invest that growth runway is where the story gets interesting.
"AI and autonomy initiatives such as DoorDash Dot robots, DoorDash Air and broad internal AI adoption are positioned as long term efficiency levers. Yet redeploying productivity gains into more feature development rather than cost reduction, combined with the upfront expense of autonomous delivery pilots, may keep fulfillment and support costs elevated and compress future net margins versus optimistic scenarios."
What happens to DoorDash’s margins and long term earnings power hinges on how one unresolved pressure on its cost base ultimately plays out.
That cost pressure is only half the story, and the full narrative for DoorDash reveals how DoorDash could still convert its AI push into accelerating earnings power over time.
ServiceNow (NOW)
ServiceNow gives large organisations a single cloud platform to digitise and automate workflows, which is exactly the kind of earnings-focused growth engine this screener targets. Its AI-enabled IT service management and automation platform is where much of that potential gets tested in the real world.
ServiceNow delivers cloud workflow software across IT, customer service, HR and security, generating about US$15.4b from internet software and services, with a market value near US$110b. That mix of workflow automation at scale and sizeable recurring revenue puts ServiceNow firmly in the Healthy high growth potential camp.
"Agentic AI monetization: ServiceNow AI crossed $1 billion in annual contract value in Q2 2026, suggesting AI is moving from experimentation toward meaningful enterprise spending."
What happens when that early AI traction meets one quietly shifting pressure on ServiceNow’s profitability and pricing power will matter a lot for investors.
That pressure on profitability is exactly what the full narrative for ServiceNow unpacks. It shows where ServiceNow’s AI momentum could accelerate, stall, or quietly decouple earnings from old pricing assumptions.

CrowdStrike Holdings (CRWD)
CrowdStrike Holdings runs the Falcon cybersecurity platform, selling SaaS subscriptions that protect endpoints, cloud workloads, identities and data. This is exactly the type of recurring, scalable earnings stream this Healthy high growth potential screen looks for. It generated about US$5.4b from security software and services and is valued around US$248.1b.
CrowdStrike matters for this screener because Falcon’s recurring subscriptions line up with the hunt for scalable earnings, and the focus now is on how its commercial model might change that earnings path.
"The introduction of Falcon Flex, a subscription model that accelerates module adoption and simplifies procurement, is increasing customer commitment and lengthening customer relationships, which may lead to increased future revenue and improved net margins due to larger, bundled sales."
How the Flex model interacts with ongoing pressure on how much customers are willing to pay for bundled security will be important.
That pricing pressure is exactly where the story gets interesting, and the full narrative for CrowdStrike Holdings shows whether Falcon Flex is accelerating durable earnings or masking new risk.

Seeking Fresh Alternatives Before They Fly
Markets move fast and the next breakout list will not stay under the radar for long. Scan fresh ideas before the crowd, while it matters, and act now.
- Spot early-stage turnarounds that already show financial discipline by reviewing the 19 high quality undiscovered gems, which is curated from stronger balance sheets and cleaner fundamentals.
- Ride structural trends in power demand by checking the 42 power grid technology and infrastructure stocks, which highlights businesses exposed to grid upgrades, transmission buildouts, and critical infrastructure momentum.
- Target durable cash generators by using the 4 dividend fortresses, which is curated for higher yields that still keep an eye on balance sheet strength and payout resilience.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com