


EN
What Oxford Biomedica Bears Spotted Before The Slide
If you only glanced at the headlines on Oxford Biomedica, talk of AI tools cutting development time and a swelling roster of client programmes might have sounded like everything was moving in the right direction. For Oxford Biomedica shareholders, the loss over the past year was 20.1%, including dividends. If you were weighing up a position back in November 2025, what in the public record hinted that this apparently upbeat story could still end in a deeper red bottom line?
Narratives are how investors here put a case on the record, with explicit assumptions about revenue, margins and the multiple. Those assumptions imply an estimated Fair Value.
Oxford Biomedica has already moved. Pinpoint other ways to investigate the theme among 9 healthcare AI stocks.
The Two Oxford Biomedica Stories Investors Had To Weigh
The shares cost £6.54 at the start of the period, and Oxford Biomedica sat between two very different stories about what might happen next.
The bullish narrative set Fair Value at £9.01, based on assumed revenue growth of 36.4% a year and profit margins moving from a loss to 15.7%, with the business eventually trading on a P/E of 25.8x.
The more cautious case set Fair Value at £5.93, built around assumed annual revenue growth of 26.2%, an 8.4% profit margin, and a higher 35.1x P/E assumption that highlighted execution and cost risks.
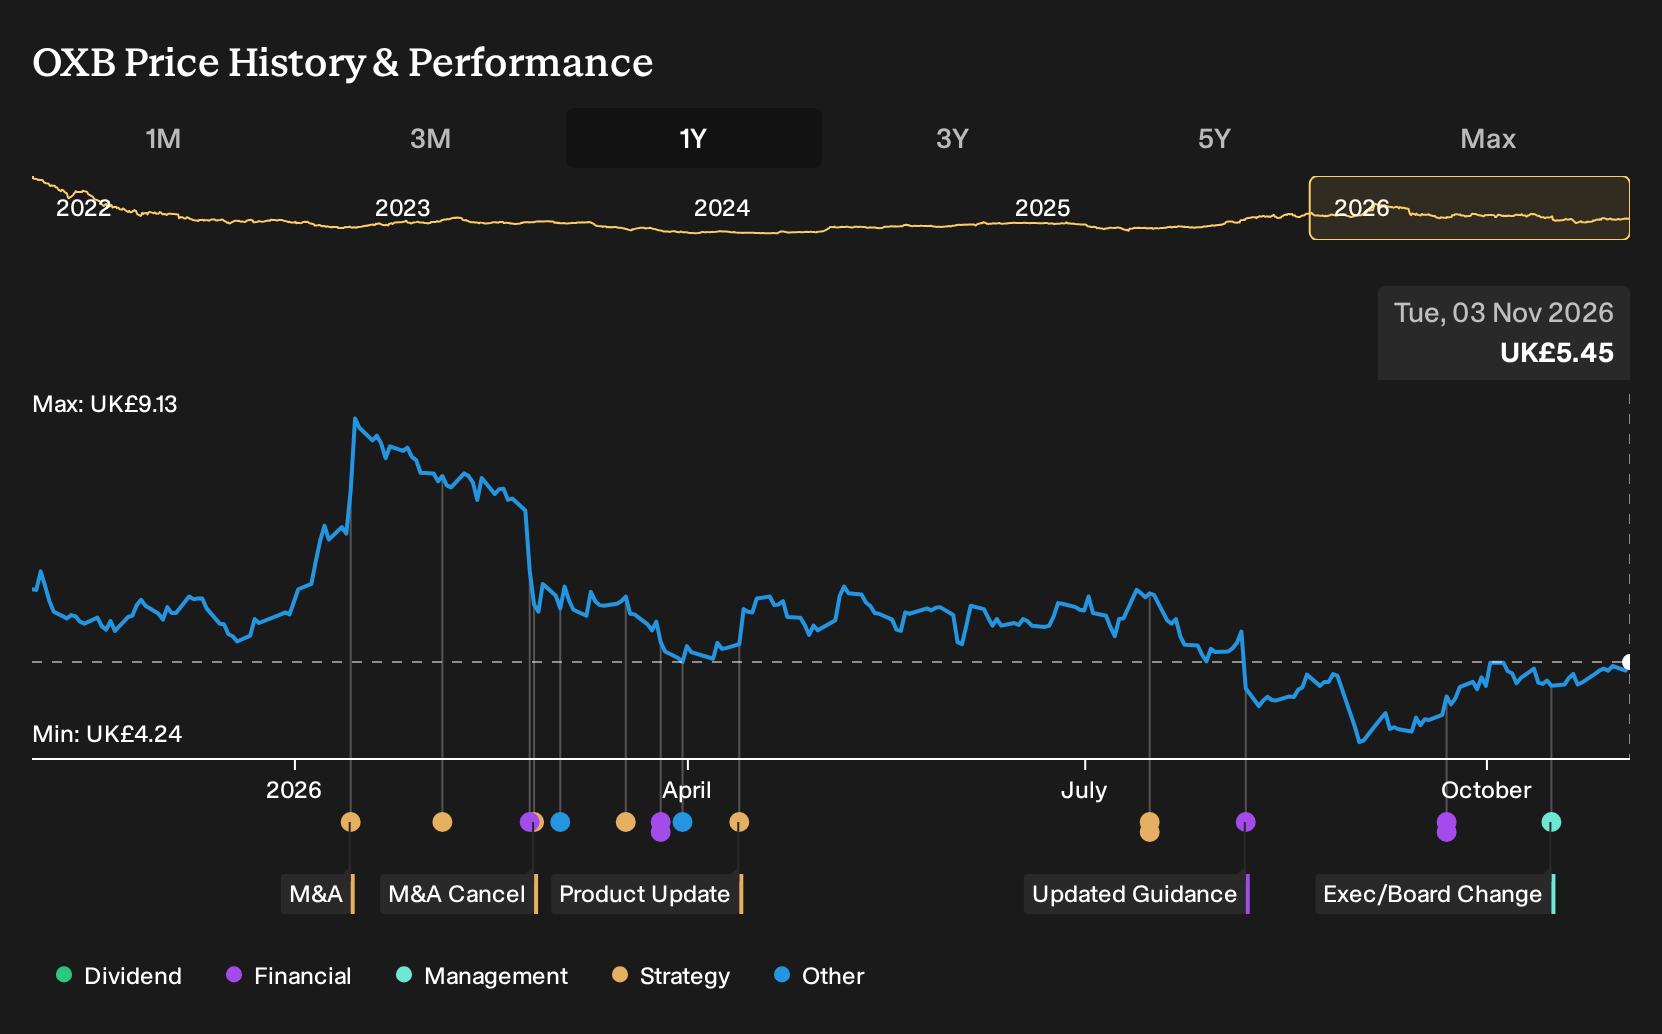
What The Results Changed For Oxford Biomedica
The headline story was Oxford Biomedica using AI tools and automation to shorten experiments and win work, with 17 new clients and 59 programmes across 50 customers. That backed the growth angle in both cases. The later H1 2026 numbers told a different story. Revenue reached £79.845m, yet the business still reported a larger loss and a net margin that fell to -46.3%, so profitability in the bullish script remained unproven. The evidence cut both ways.
The hinge assumption here was margin recovery catching up with revenue momentum. For another stock built on similar promises, focus on whether higher sales move the net margin figure toward break-even or deeper into loss, and test any upbeat claims against that trend over more than one reporting period.
What You Are Paying For In Oxford Biomedica Today
Oxford Biomedica now trades at £5.45, with this Narrative’s Fair Value sitting above that level based on its reading of the current setup. The focus is less on headline market growth and more on how quickly already awarded projects turn into revenue and cash.
The distinctive claim is that backlog, client momentum and proposal win rates could support stronger cash generation than implied by today’s price. For that higher Fair Value to be reached, a buyer now would need to believe the existing pipeline converts into timely, higher margin GMP manufacturing rather than stalling or slipping.
"A commercial pipeline of about $730m at mid 2026, up 30% year on year with contracted orders rising from £97m at half year to £127m by end August and a revenue backlog of £199m, gives Oxford Biomedica scope to convert a larger pool of already awarded work into recognised revenue and operating cash flow than typical top line models assume."
One Narrative disagrees with today's price. → See where this Narrative says Oxford Biomedica should trade
Go Straight To The Source
The next headline does not have to be where your research begins. Go straight to the companies and see whether a contrarian opportunity could be taking shape.
- Company 1 - 38% below our estimate - uses new wealth products and co investments to raise fee income.
- Company 2 - 33% below our estimate - leans on subscriptions and recommerce to grow cash generation from traffic.
- Company 3 - 20% below our estimate - scales long cycle defense programs and autonomous platforms into service contracts.
That is three of the list. See every one of the 15 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com