


EN
SBI Shinsei Bank (TSE:8303) Stock Shrugs Off Q2 Earnings Revenue Drop
SBI Shinsei Bank came into this Q2 2027 report with a reputation as a discounted growth story, trading on a 12.5x P/E and about 30% below one discounted cash flow estimate. The fresh numbers show Basic EPS of ¥34.53 and net income of ¥30.63b for the quarter, healthy on their own for a mid sized Japanese bank, yet the stock closed at ¥1,599.5 with only modest recent gains. The real tension for holders is simple: earnings keep moving while forecasts still point to pressured revenue over the coming years.
Love the earnings traction at SBI Shinsei Bank but concerned about forecasts that still flag pressure on revenue ahead? Benchmark this setup against a curated list of companies that combine earnings power with clearer top line momentum in our 17 high quality undervalued stocks
Q2 2027 Earnings Summary
- Revenue (Q2 2027 vs. Q2 2026): ¥126,965 million vs. ¥193,823 million (Revenue declined 34.5%)
- Net Income (Q2 2027 vs. Q2 2026): ¥30,630 million vs. ¥21,551 million (Net income increased 42.1%)
- Basic EPS (Q2 2027 vs. Q2 2026): ¥34.53 vs. ¥26.49 (Basic EPS increased 30.3%)
- Total Loans (Q2 2027 vs. Q2 2026): Not disclosed for Q2 2027 vs. ¥10,664,233 million (Loan book comparison not available this quarter)
Earnings only tell part of the story, since SBI Shinsei Bank's cash generation ultimately underpins both its ability to invest and to return money to shareholders. Based on SBI Shinsei Bank's cash flows alone, the stock could be a hefty 30% undervalued.
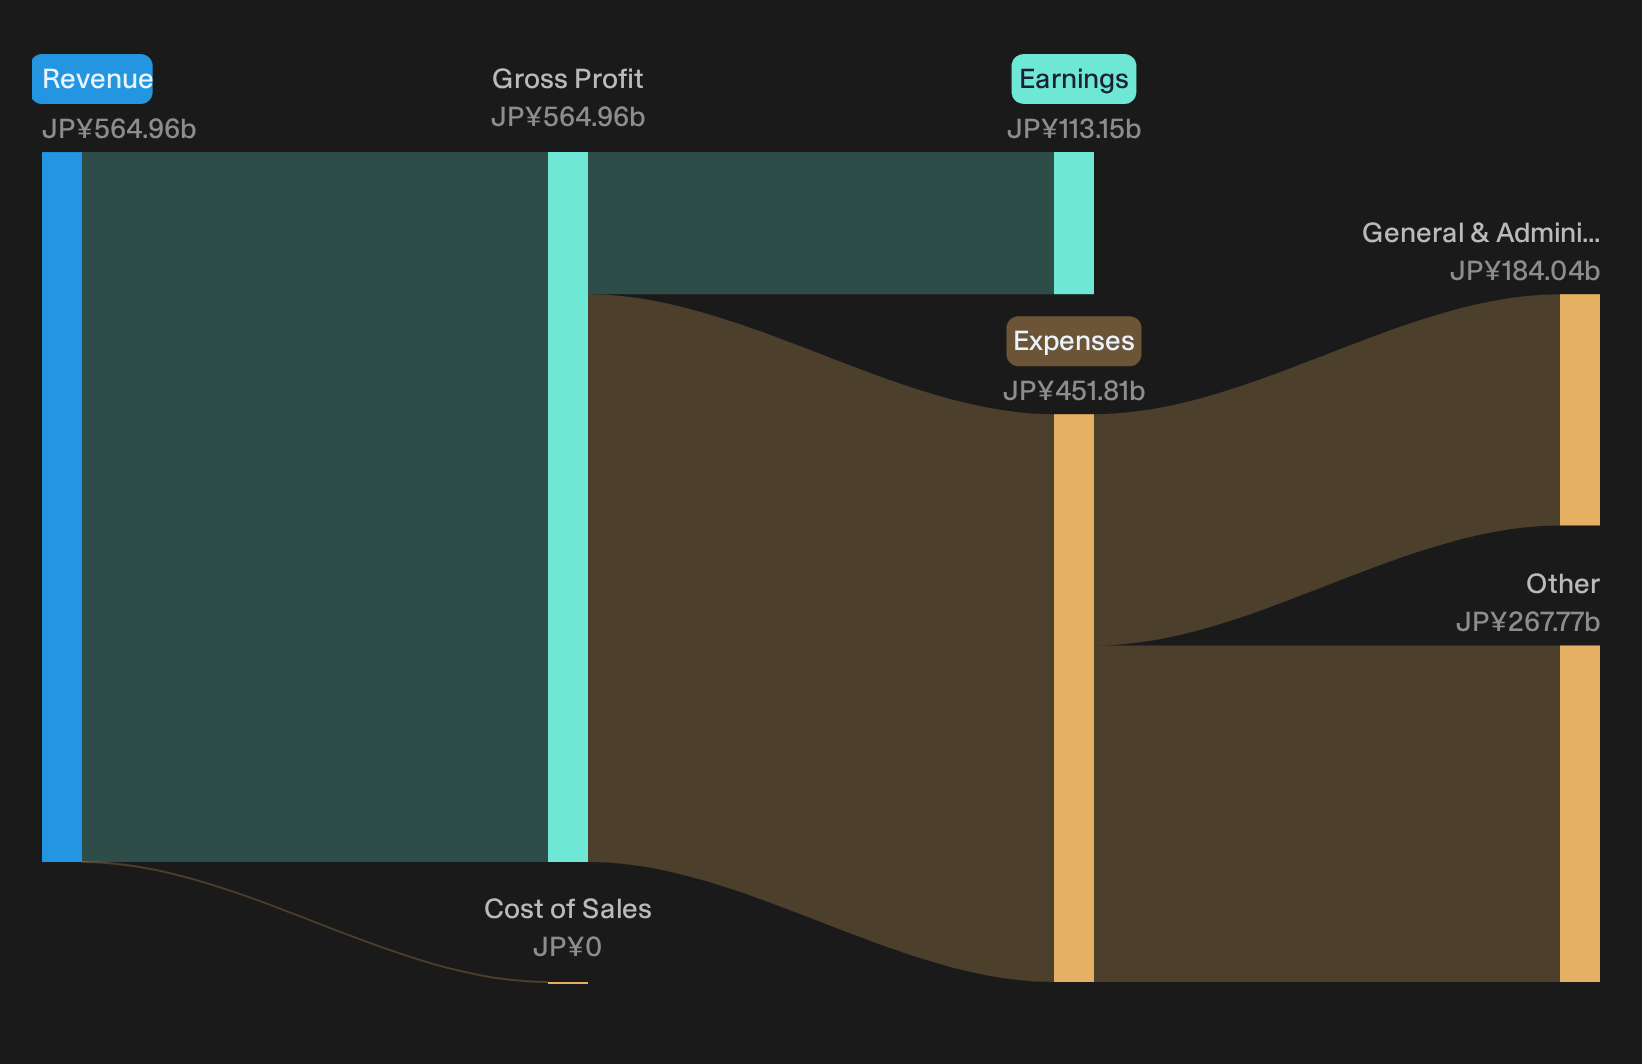
SBI Shinsei Bank’s Earnings Strength vs Revenue Drag
SBI Shinsei Bank shows a split picture. Profitability is moving in the right direction, with quarterly net income of ¥30.63b and Basic EPS at ¥34.53, both above last year’s levels. That supports a narrative that the diversified model can still produce solid earnings even when conditions are tough. Market reaction has been calm rather than euphoric. The share price is up only mid single digits over 30 and 90 days, which suggests investors see progress but are still waiting for clearer follow through.
Revenue Slide Keeps Bears Interested For Now
The bearish angle does not look misplaced. Revenue fell 34.5% year on year to ¥126,965m while total loans were not disclosed. That removes a useful volume reference point for this quarter. For a bank that leans on multiple lending and fee engines, such a steep top line step down raises questions about how repeatable the current profit mix is. Recent share price gains around 5% to 7% over 1 to 3 months suggest risks are being acknowledged but not treated as urgent distress.
After a 34.5% revenue drop and missing loan data, it is fair to ask whether SBI Shinsei Bank’s earnings resilience is masking softer structural issues in funding, credit quality, or capital allocation. Scan the risk analysis for SBI Shinsei Bank which shows 2 important warning signs to see if these are isolated concerns or part of a broader risk pattern you might be overlooking.Explore Quiet Balance Sheet Outliers
SBI Shinsei Bank shows how steady earnings and a muted share price can leave investors questioning the setup. The real opportunity is finding stocks that could be low debt before the market corrects them.
- Company 1 - 40% below our estimate - uses AI driven matching to translate job and local service searches into higher value placements.
- Company 2 - 17% below our estimate - adds sales capacity to secure maintenance contracts that deepen customer relationships and support modernization work.
- Company 3 - 48% below our estimate - pushes an AI native security platform that shifts one off licenses toward recurring protection bundles.
Three companies from the same screener. Open the full list of 22 financially solid companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com