


EN
Should Stronger Earnings Require Action From First Capital REIT (TSX:FCR.UN) Investors?
- First Capital Real Estate Investment Trust reported third quarter 2026 results with sales of C$187.17 million and net income of C$116.1 million, while nine-month figures reached C$562.75 million in sales and C$232.53 million in net income, all compared with the same periods a year earlier.
- The trust paired these earnings with a 13.2% lease renewal lift, 96.9% portfolio occupancy, ongoing property sales activity and a declared November 2026 cash distribution of C$0.076 per unit.
- The focus now turns to how First Capital Real Estate Investment Trust's higher net income shapes the investment narrative that investors are tracking.
What Is First Capital Real Estate Investment Trust's Investment Narrative?
The investment case for First Capital Real Estate Investment Trust starts with a simple belief. You need to think grocery anchored centers in strong Canadian neighborhoods can keep drawing tenants and shoppers, even as retail formats and consumer habits keep evolving. The latest quarter fits that picture. Leasing spreads rose, occupancy sat at 96.9% and management kept pruning the portfolio with property sales, which can help recycle capital in a capital intensive real estate model.
In the short term, the fresh jump in net income and the November cash distribution of C$0.076 per unit speak to solid execution, but the risk profile has not disappeared. One off gains still influence reported earnings quality, interest costs are not fully covered by earnings and the dividend history has had bumps. The real test for First Capital Real Estate Investment Trust now is how consistently cash flow backs this story.
Yet there is a pressure point in this setup that only really shows up once you look at ...
There's only one way to know the right time to buy, sell or hold First Capital Real Estate Investment Trust. Head to Simply Wall St's company report for the latest analysis of First Capital Real Estate Investment Trust's Fair Value.
Exploring Other Perspectives
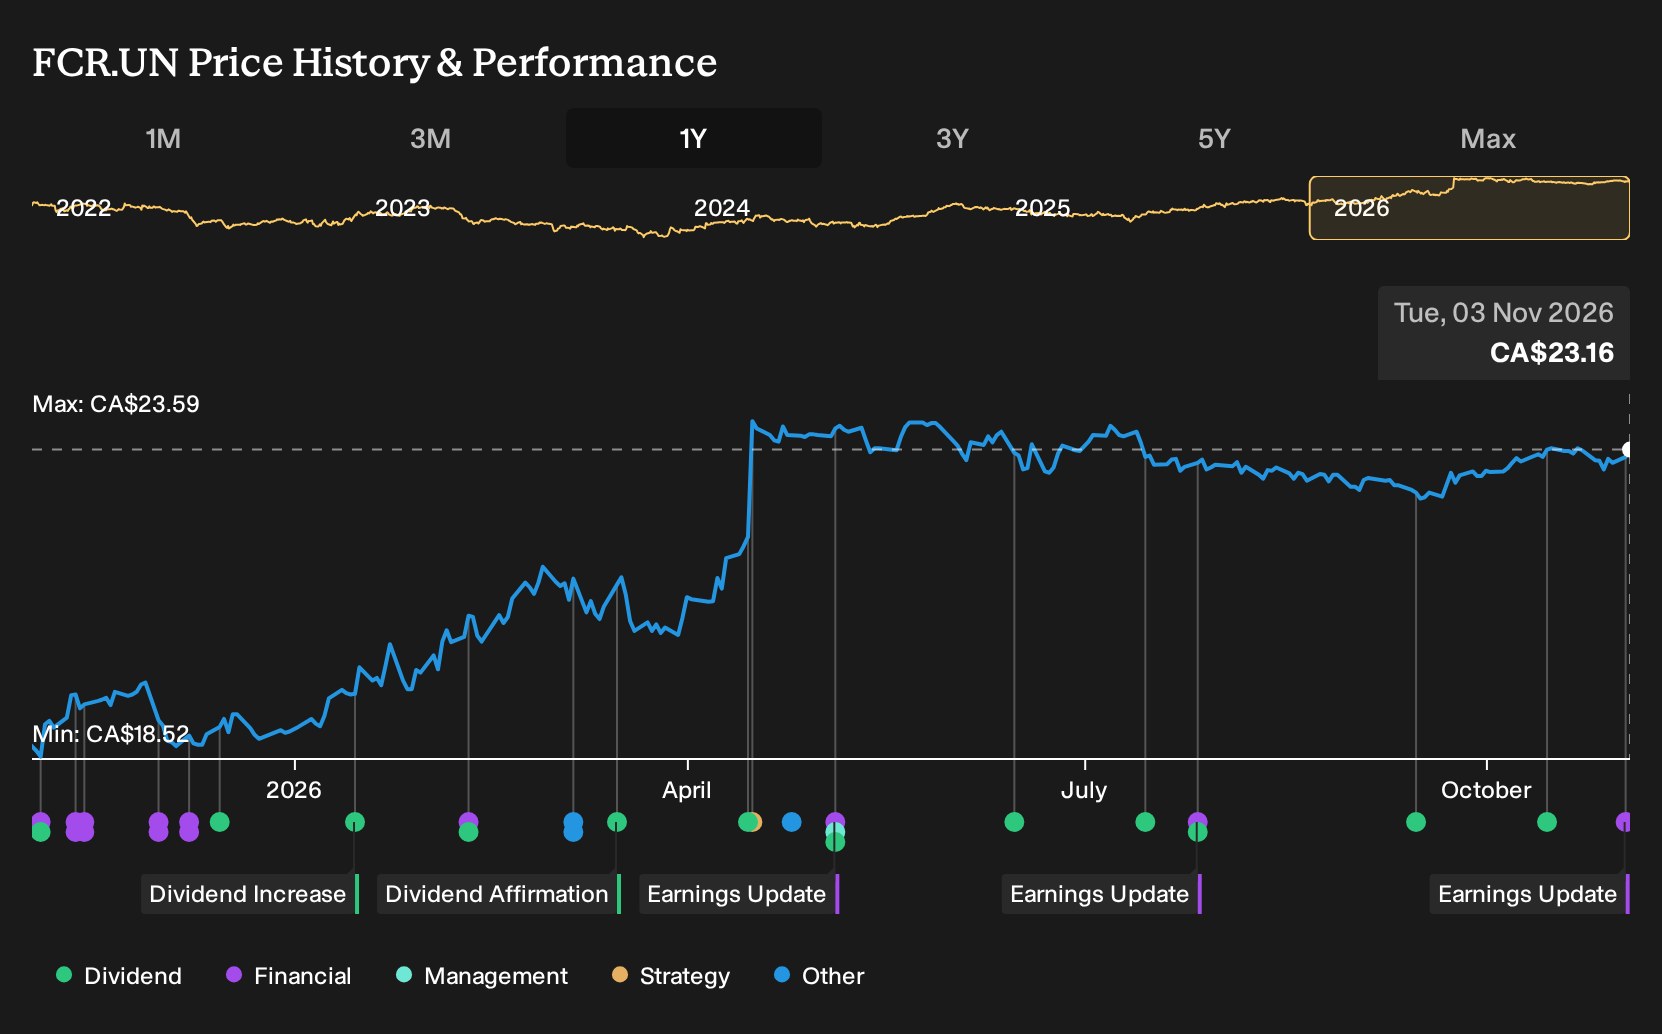
Two fair value estimates from the Simply Wall St Community cluster in a narrow C$24.36 to C$27.43 band, so even a small price move can change the perceived upside or downside for First Capital Real Estate Investment Trust. Those community views were set before the recent earnings release. You can compare them with fresh numbers and weigh how your own expectations for future leasing, asset sales and distributions line up. Investor opinions can differ widely. It helps to test your view against several alternative takes before deciding how First Capital fits into your portfolio.
Explore another First Capital Real Estate Investment Trust fair value estimate, including one that suggests it could be worth just CA$24.36.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that is truly your own.
- A great starting point for your First Capital Real Estate Investment Trust research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for First Capital Real Estate Investment Trust. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate First Capital Real Estate Investment Trust's overall financial health at a glance.
Looking For More Investment Ideas Beyond First Capital Real Estate Investment Trust?
If First Capital Real Estate Investment Trust has sharpened your focus on income, quality and risk, you can widen the search by using screeners that surface other stocks with clear financial profiles and different trade offs. Let the data do the heavy lifting while you concentrate on whether each opportunity matches your goals and time horizon.
- If you want potential value combined with fundamental strength, scan a curated set of 4 high quality undervalued stocks that pair quality cash flows with conservative balance sheets.
- For investors who put capital preservation first, filter the market for 9 resilient stocks with low risk scores and see which companies score well on stability and downside resilience.
- Income focused readers can round out their watchlist by reviewing a 3 dividend fortresses that target higher yielding businesses with established payout records.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com