


EN
What TriCo Bancshares (TCBK)'s Strong Earnings Report Means For Shareholders
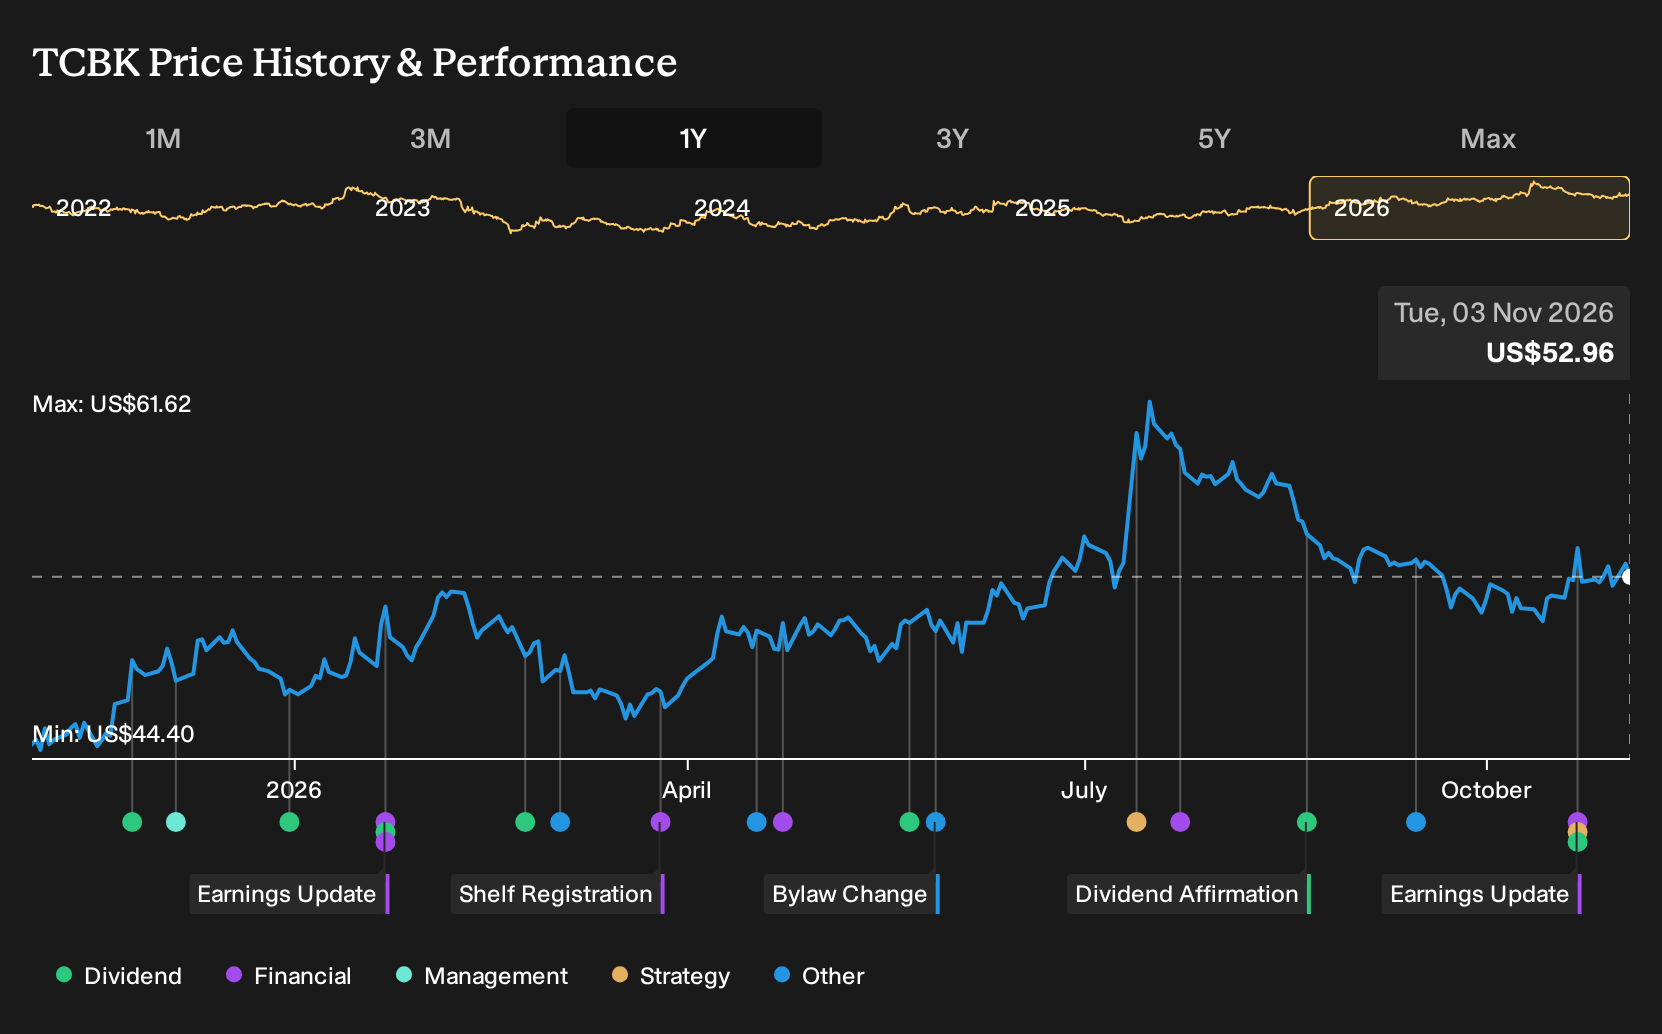
- TriCo Bancshares reported third quarter 2026 net interest income of US$96.55 million and net income of US$37.97 million, with diluted EPS from continuing operations of US$1.18, and affirmed a US$0.36 quarterly dividend.
- The combination of higher earnings per share over both the quarter and nine month period and very limited net charge offs of US$0.3 million indicates how TriCo Bancshares is managing credit quality while growing profitability.
- It remains to be seen how TriCo Bancshares' higher earnings per share and maintained dividend could shape the broader investment narrative.
Compare TriCo Bancshares' mix of higher earnings, low charge offs, and a maintained dividend with a curated 29 resilient stocks with low risk scores that share a similar focus on resilience and balance sheet strength.
TriCo Bancshares Investment Narrative Recap
To hold TriCo Bancshares, investors generally need to believe the combined bank can keep earnings quality solid while integrating with First Hawaiian and controlling funding costs. The latest quarter points to a business that is generating higher net interest income and net income with very low net charge offs, which supports that view.
The near term swing factor remains merger execution, especially delivering the planned IT and vendor cost savings without hurting service or credit standards. The biggest risk is that integration drags or savings fall short, in which case the recent earnings strength would not meaningfully change the overall catalyst or risk profile.
The third quarter earnings report is the clearest reference point for your thesis today. TriCo Bancshares posted US$96.55 million of net interest income, US$37.97 million of net income and diluted EPS from continuing operations of US$1.18, alongside nine month diluted EPS of US$3.29 from continuing operations, supported by net charge offs of US$0.3 million.
That mix matters for the merger story because it shows the banking franchise entering integration with positive earnings trends and very limited credit losses. If management can layer planned cost savings on top of this operational base, the earnings profile and capital generation that analysts focus on as key catalysts will depend less on outsized growth and more on consistent execution.
Analysts expect TriCo Bancshares to reach about US$515.4 million of revenue and US$145.0 million of earnings by 2029. This reflects forecast yearly revenue growth of 6.5% and an earnings increase of roughly US$9.5 million from current earnings of US$135.5 million.
Discover how TriCo Bancshares' fair value indicates an 11% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Fair value guesses for TriCo Bancshares from the Simply Wall St Community cluster tightly between about US$57.84 and US$58.67 across 2 individual estimates, so you are not seeing extreme bargain or bubble calls yet. Those views sit beside merger execution risk and cost saving targets that could heavily influence how the story develops. Investor opinions can differ widely, so explore several of these alternative viewpoints before deciding how the recent earnings and dividend news fit your own thesis.
Explore another TriCo Bancshares fair value estimate, including one that suggests it could be worth just $57.84.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your TriCo Bancshares research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for TriCo Bancshares. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate TriCo Bancshares' overall financial health at a glance.
Looking for more investment ideas beyond TriCo Bancshares?
Once you have a handle on TriCo Bancshares, it can help to benchmark your thesis against other companies with different return profiles, risk levels, and income characteristics. The Simply Wall St Screener lets you filter the wider market using the same kind of fundamental signals used throughout this article.
- If you want potential upside with strict attention to financial strength, start with a 29 resilient stocks with low risk scores that prioritises resilience and balance sheet quality.
- For investors focused on value opportunities backed by solid fundamentals, scan through a 36 high quality undervalued stocks that filters for quality businesses trading below their estimated worth.
- If reliable income is your priority, compare TriCo Bancshares' payout profile with a 4 dividend fortresses built around higher yield companies that aim to sustain regular distributions.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com