


EN
Why BOK Financial (BOKF) Is Back In The Spotlight
Legal action puts BOK Financial in the spotlight
BOK Financial (BOKF) has moved into the spotlight after filing a lawsuit against two former employees and Cerity Partners, alleging client solicitation, contract breaches, and misuse of proprietary client information.
The claim centers on clients overseeing about US$1.2b in assets who reportedly shifted to Cerity, raising fresh questions for investors about BOK Financial’s wealth management relationships and potential longer term client retention risks.
Recent trading shows that the BOK Financial share price has eased 1.2% over the past day but still carries a year to date share price return of 10.31%. Longer run total shareholder returns of 28.01% over one year and about double over three years point to investors having previously rewarded the story, despite a 9.42% decline in the 90 day share price return that hints at fading momentum as this legal dispute and other developments, including maintained 2026 earnings guidance with mid single digit revenue growth expectations, reset risk perceptions around the stock.
Stress test how this BOK Financial story compares by scanning a curated set of banks and financials using 29 resilient stocks with low risk scores, which may offer steadier risk profiles than headline-driven situations like this lawsuit.
For BOK Financial, the pullback after the lawsuit headlines comes alongside steady 2026 guidance and recent share price gains. Is this move pointing to cracks in the business or just cooler sentiment, and how might that affect valuation next?
Most Popular Narrative: 10% Undervalued
BOK Financial last closed at $130.92, against a widely followed fair value estimate of $145 that points to a modest discount and puts fresh focus on whether the lawsuit changes the long term story at all.
The numbers imply the share price does not fully reflect a bank with roughly 38% of 2025 revenue from fees, ongoing net interest margin expansion, strong capital levels, and management using buybacks and Visa share monetization when it sees value in the stock.
Continued broad based loan growth led by core C&I and specialty areas such as health care, energy and the newer mortgage finance warehouse business, guided to over 10% for 2026, may lift interest earning assets and net interest income.
See why 0 investors see BOK Financial as 10% undervalued.
Result: Fair Value of $145 (UNDERVALUED)
Still, pressure on fee income and any sector specific weakness in commercial real estate or energy lending could quickly test the BOK Financial valuation story.
Find out about the key risks to this BOK Financial narrative.
Another View on BOK Financial’s valuation
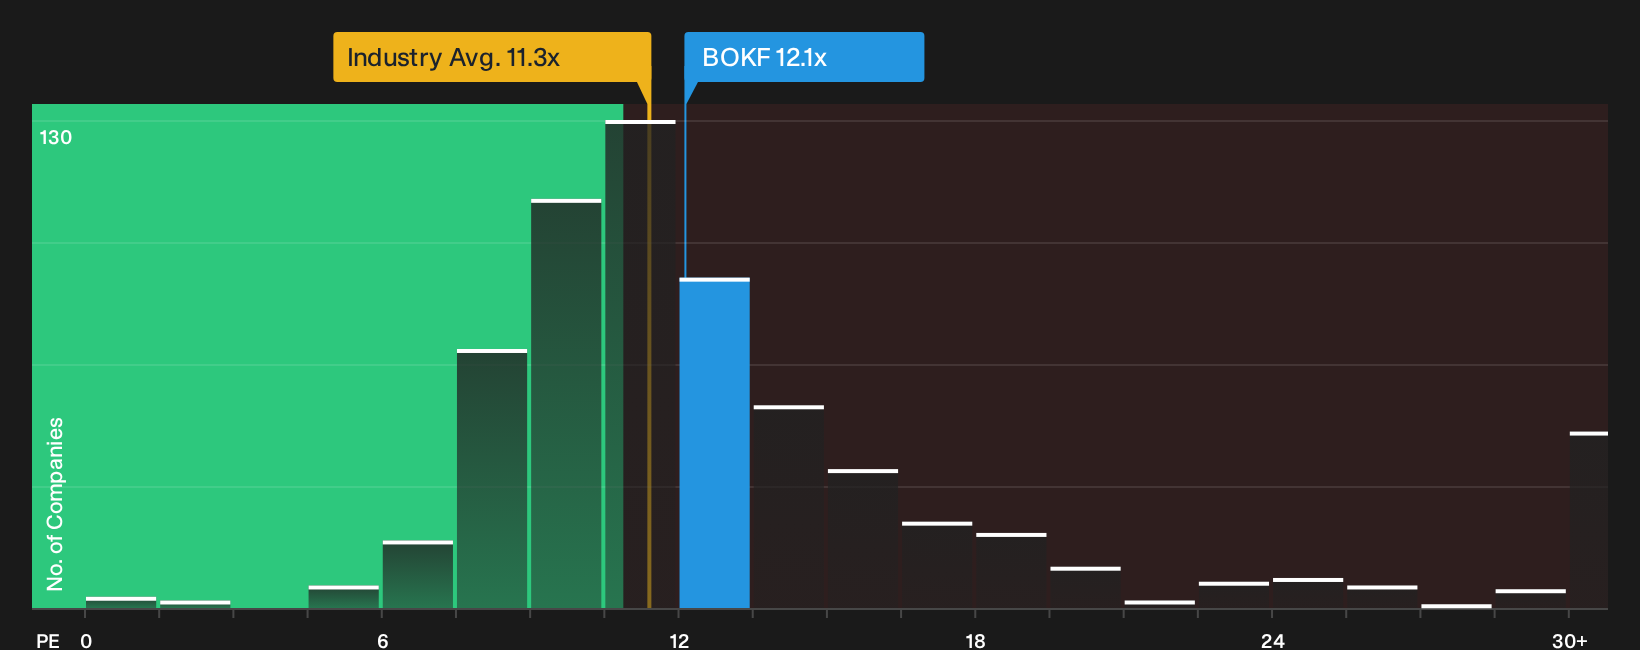
The earlier fair value narrative paints BOK Financial as undervalued, yet the simple P/E check tells a different story. The shares trade on about 12.1x earnings, above both the US Banks industry at 11.3x and the fair ratio of 11.3x, which points to less valuation cushion if sentiment weakens next.
To see how those earnings multiples stack up across peers and where the fair ratio could matter most for risk, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals around BOK Financial’s valuation and legal risks can feel messy, so act promptly, review the underlying data carefully, and decide where you stand using 3 key rewards and 1 important warning sign.
Looking for more BOK Financial sized investment ideas?
If BOK Financial has sharpened your focus on risk, valuation, and long term potential, do not stop here. Fresh opportunities rarely wait around for hesitation.
- Target resilience in tougher markets by scanning a list of solid balance sheet and fundamentals (23 results) that can help you focus on companies with sturdier finances than headline driven situations.
- Hunt for pricing gaps where quality and valuation look more compelling by checking a curated 36 high quality undervalued stocks before others move first.
- Build a stream of income ideas by reviewing a focused 4 dividend fortresses that highlights higher yield options you might otherwise overlook.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com