


EN
Analog Devices (ADI) Stock Could Be Overvalued As ASIC Demand Expands
Analog Devices has delivered a powerful share price run in recent years, and the latest moves in key chip markets keep expectations in focus. With the stock now reflecting a long stretch of strong gains, the central question is whether that price still lines up with what its earnings can support.
- Over the past 3 years, Analog Devices has returned about 161.6%, which puts a lot of weight on whether its current earnings profile can carry that kind of re-rating.
- Recent industry reports highlight Analog Devices as a participant in fast-expanding ASIC and digital power IC markets. This can influence how investors think about the durability and timing of its profit streams.
- There is a second opinion on Analog Devices worth weighing. See what analysts think Analog Devices's shares could be worth.
The issue now is whether the stock's current price is justified by its earnings when set against a Fair Ratio benchmark.
If you want to explore the same earnings-based valuation question across a broader set of chip-related opportunities, review the 53 AI infrastructure stocks results.
Has Analog Devices Run Too Far on Earnings?
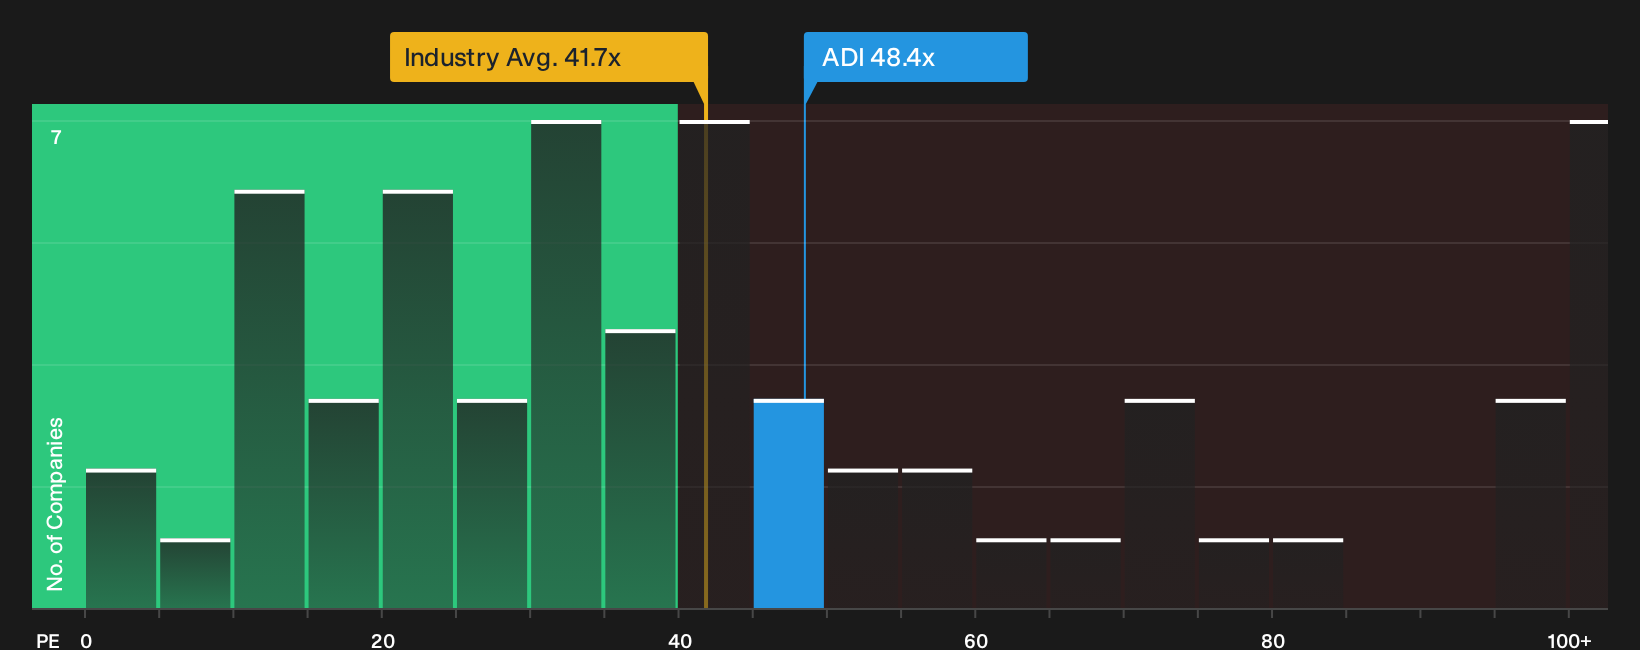
The P/E ratio works well for Analog Devices because earnings are a core focus for how this chip business is valued. The stock currently trades on about 49.2x earnings, which is above the broader semiconductor sector at roughly 41.7x and also higher than the peer group average near 34.2x. On this yardstick, investors are paying a visibly richer price for each dollar of profit than they would for many similar chip makers.
The Fair Ratio model, which looks at what kind of P/E multiple might fit Analog Devices given its growth profile, profitability, size and risk, points to the current valuation sitting on the expensive side of that tailored range. Because recent reports flag ASIC and digital power IC demand tied to AI, 5G and data centers, some of this premium likely reflects investors leaning into those themes, even as the shares already trade at a marked premium to both sector and peer benchmarks. Explore the numbers behind Analog Devices's P/E valuation.
The Analog Devices Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Analog Devices take that rich P/E debate and translate it into clear, testable stories about what would need to happen to Analog Devices' growth, margins and earnings for the current share price to look either stretched or conservative. Each narrative links its implied valuation back to a specific view on how the business could develop and what risks might matter next, which you can revisit as new information comes through.
Views on Analog Devices are now split between investors who see more upside left in the story and those who think AI and auto optimism already crowd the price.
Bull case: 11% undervalued
"Ongoing industrial and mass market recovery, with industrial at 49% of Q3 2026 revenue and up strongly across automation, energy infrastructure…"
Discover why this Narrative puts Analog Devices at 11% undervalued.
Bear case: 13% overvalued
"At least one external analysis that values Analog Devices around US$228 per share on a discounted cash flow basis, compared with a market price near US$389…"
Explore why this Narrative puts Analog Devices at 13% overvalued.
One more Analog Devices check that belongs beside the valuation debate
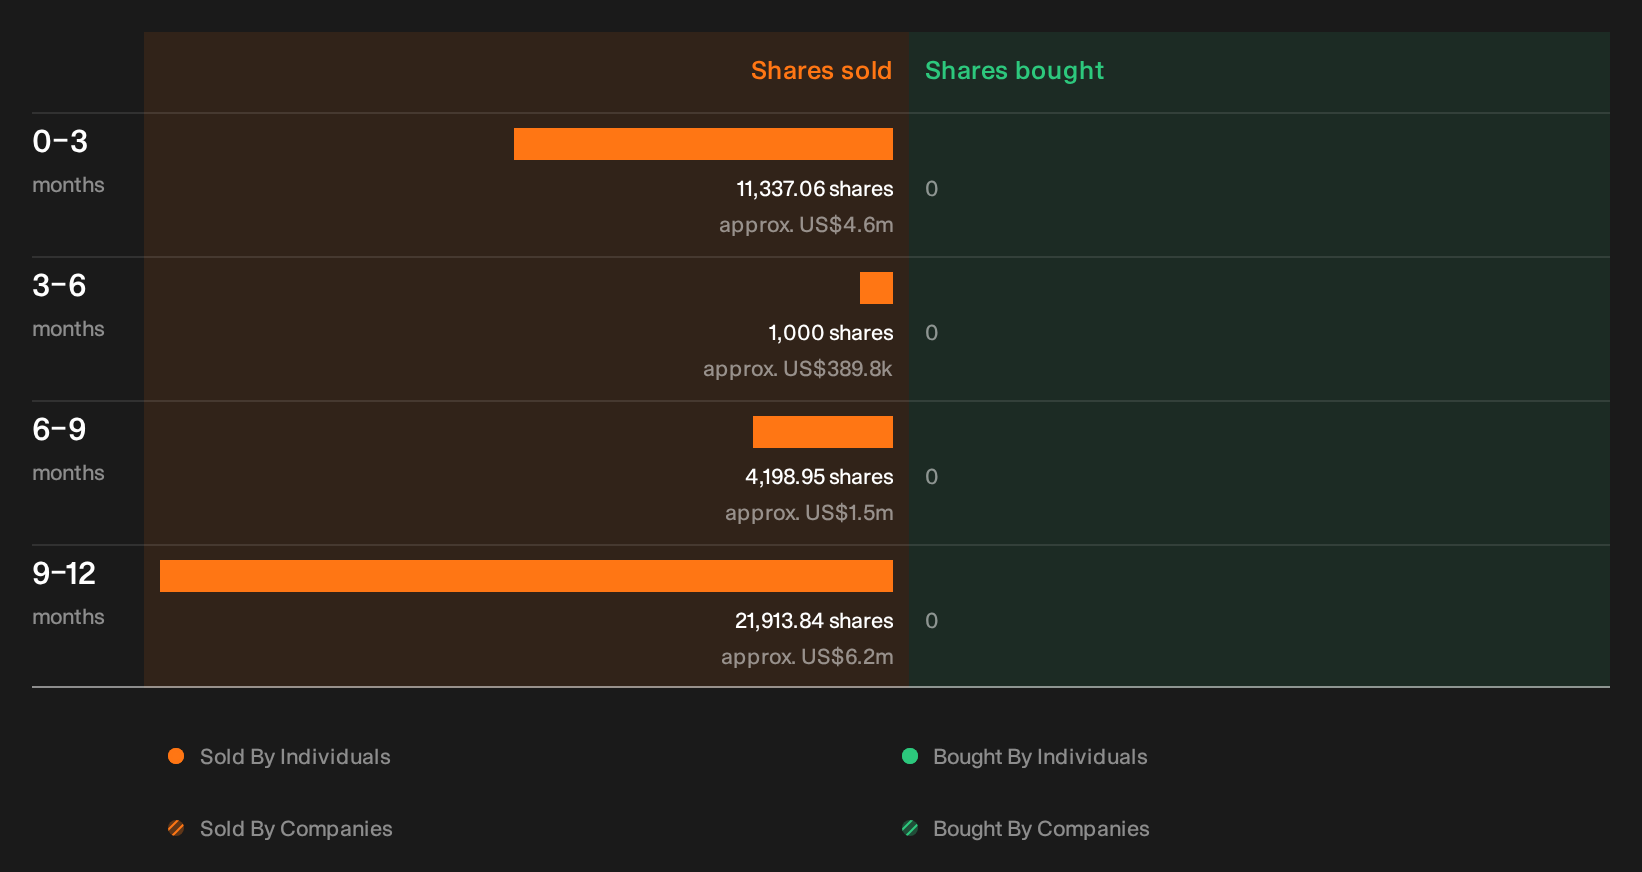
Price ratios and storylines only go so far when insiders are making their own decisions about holding or selling. Recent trading by key people at Analog Devices now sits on that list of things to review next. See the recent insider selling flagged for Analog Devices.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com