


EN
Eversource Energy (ES), Why Is Attention Building Ahead Of Its Latest Update?
Eversource Energy (ES) heads into its third quarter 2026 earnings report on 4 November, with investors weighing expected lower profit against a streamlined regulated utility portfolio and ongoing grid investment.
Recent trading has leaned positive for Eversource Energy, with the share price up 7.83% over the past 30 days and 2.19% year to date at US$69.55, although the 1 year total shareholder return is slightly negative at 2.15%, while the 3 year total shareholder return of 41.25% points to stronger longer term momentum.
Scan a curated set of regulated utilities with similar risk return profiles and see how Eversource Energy compares against the 29 resilient stocks with low risk scores in your watchlist today.
Eversource Energy now pairs a regulated utility footprint with a recent share rebound, which raises a simple tension. Are investors paying a fair price for that stability, or stretching for it?
Most Popular Narrative: 3% Undervalued
On the widely followed narrative, Eversource Energy screens modestly below its fair value estimate of $72.00 compared with the latest close at $69.55. That gap rests on a view that regulated capital spending and cost recovery can support higher earnings over time than the market is currently pricing in.
The move toward a pure play regulated electric and gas utility has advanced with the US$2.4b Aquarion Water sale and exit from offshore wind development. This reduces non core exposure and allows more balance sheet capacity to support regulated investments that drive rate based revenue and earnings.
See why 19 investors see Eversource Energy as 3% undervalued.
Result: Fair Value of $72.00 (UNDERVALUED)
Still, the narrative around Eversource Energy can be tested if regulators keep trimming allowed returns on key transmission assets or if they continue to limit recovery of storm related costs.
Find out about the key risks to this Eversource Energy narrative.
Another View: What Eversource Energy’s P/E Is Really Saying
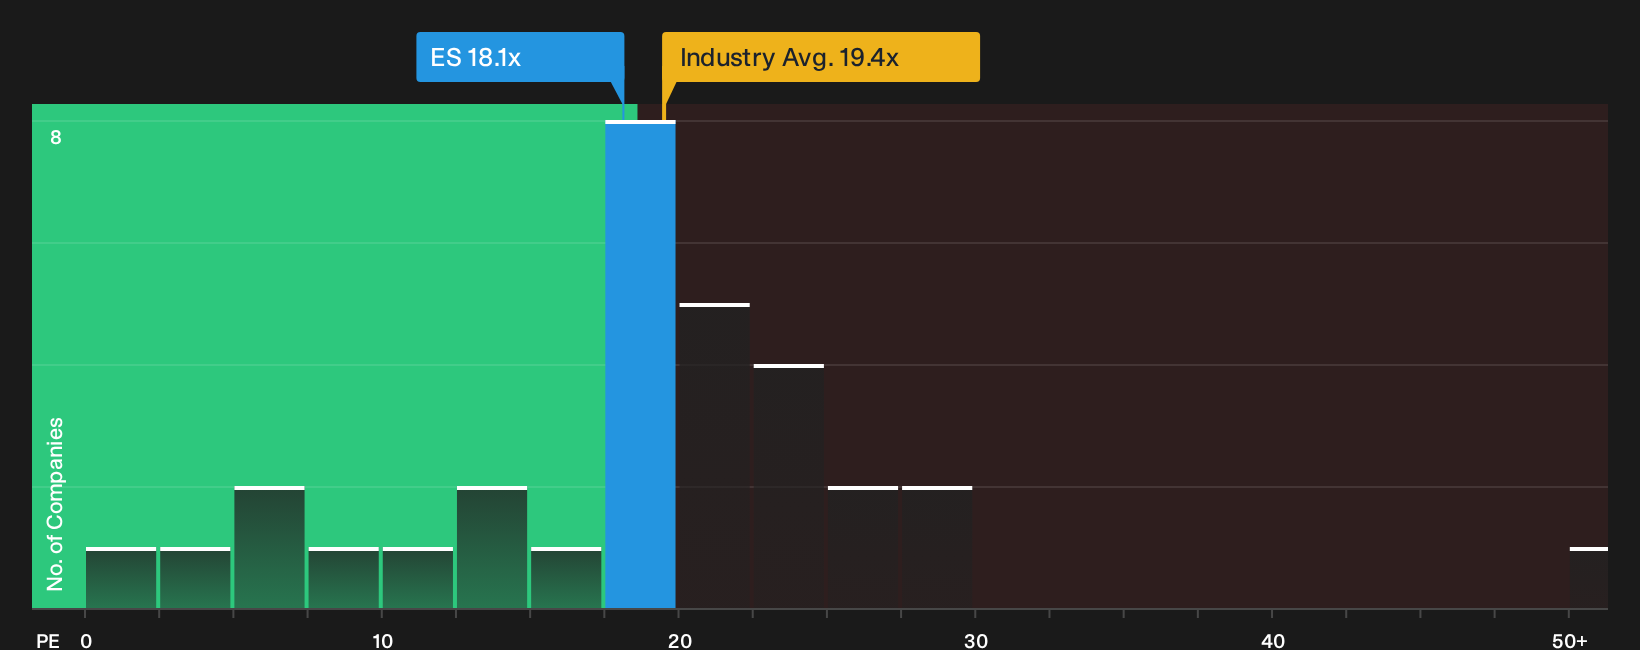
The first fair value story puts Eversource Energy modestly below a US$72.00 intrinsic estimate. A simple P/E lens paints a rougher picture. The stock trades at 18.1x earnings, above the 15.2x peer average, even though the estimated fair ratio is 21.8x. That gap suggests investors are already paying a premium to similar utilities while still leaving room before the P/E reaches the level our fair ratio implies, which can cut both ways. Is that enough margin of safety for you, or does it feel like you are paying up for stability?
To pressure test this second view against the narrative driven fair value, take a closer look at how the numbers stack up across different utilities in the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals can feel uncomfortable, especially when Eversource Energy carries both risk flags and upside triggers that pull in different directions. If you want to move quickly and build your own view from the ground up, start with the full breakdown of 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Eversource Energy?
If Eversource Energy has sharpened your thinking on utilities, you can use that momentum to scan broader opportunities before the next wave of market moves passes you by.
- Target resilient balance sheets by reviewing companies in our list of solid balance sheet and fundamentals (24 results) that combine financial strength with room for further analysis.
- Hunt for potential value by checking the 34 high quality undervalued stocks that may offer mispriced quality based on fundamentals you can scrutinize in detail.
- Build a cash flow focused watchlist by filtering for income opportunities across the 4 dividend fortresses and see which payouts align with your goals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com