


EN
Guardant Health (GH) Heads To ESMO, Is The Premium Already Priced In?
Guardant Health (GH) is back in front of oncologists, with multiple presentations scheduled at the 2026 European Society for Medical Oncology Congress in Spain. That conference spotlight prompts a closer look at the stock today.
Guardant Health’s share price has cooled in the very short term, with a 1-day share price return of 4.51% down and a 30-day share price return of 3.98% down, yet the year-to-date share price return of 67.81% and a 1-year total shareholder return of 72.59% indicate strong momentum. Recent conference attention at ESMO could either reinforce or test this momentum as expectations around growth and execution shift.
Scan 33 healthcare AI stocks to find other oncology and diagnostics stocks that could see similar attention when major medical conferences present their data to specialists.
The question now is whether Guardant Health’s sharp year-to-date climb reflects improving business fundamentals or a swing in sentiment around liquid biopsy and cancer screening, and how that balance shows up in the current valuation.
Most Popular Narrative: 16% Undervalued
Guardant Health’s most followed valuation view puts fair value at $202.24, above the last close of $170.73. This frames today’s rally as a move inside an already optimistic earnings and cash flow story that leans heavily on screening and oncology volume.
Accelerating adoption of Guardant Health’s blood based colorectal cancer screening Shield, supported by coverage for roughly 70 to 80% of eligible U.S. adults and sharply higher test volumes, is expanding the screening revenue base and creating operating leverage that can support future margins and cash generation.
Planned cost reductions for Shield, with cost per test already at about US$410 and management targeting roughly US$350 by late 2026 and about US$200 at scale by 2028, directly support gross margin improvement and a shorter path toward company wide cash flow breakeven.
See why 22 investors see Guardant Health as 16% undervalued.
Result: Fair Value of $202.24 (UNDERVALUED)
Still, the patent infringement judgment and ongoing free cash flow burn guidance for 2026 leave Guardant Health exposed if cash needs or royalties tighten the story.
Find out about the key risks to this Guardant Health narrative.
Another View: Guardant Health Looks Expensive On Sales
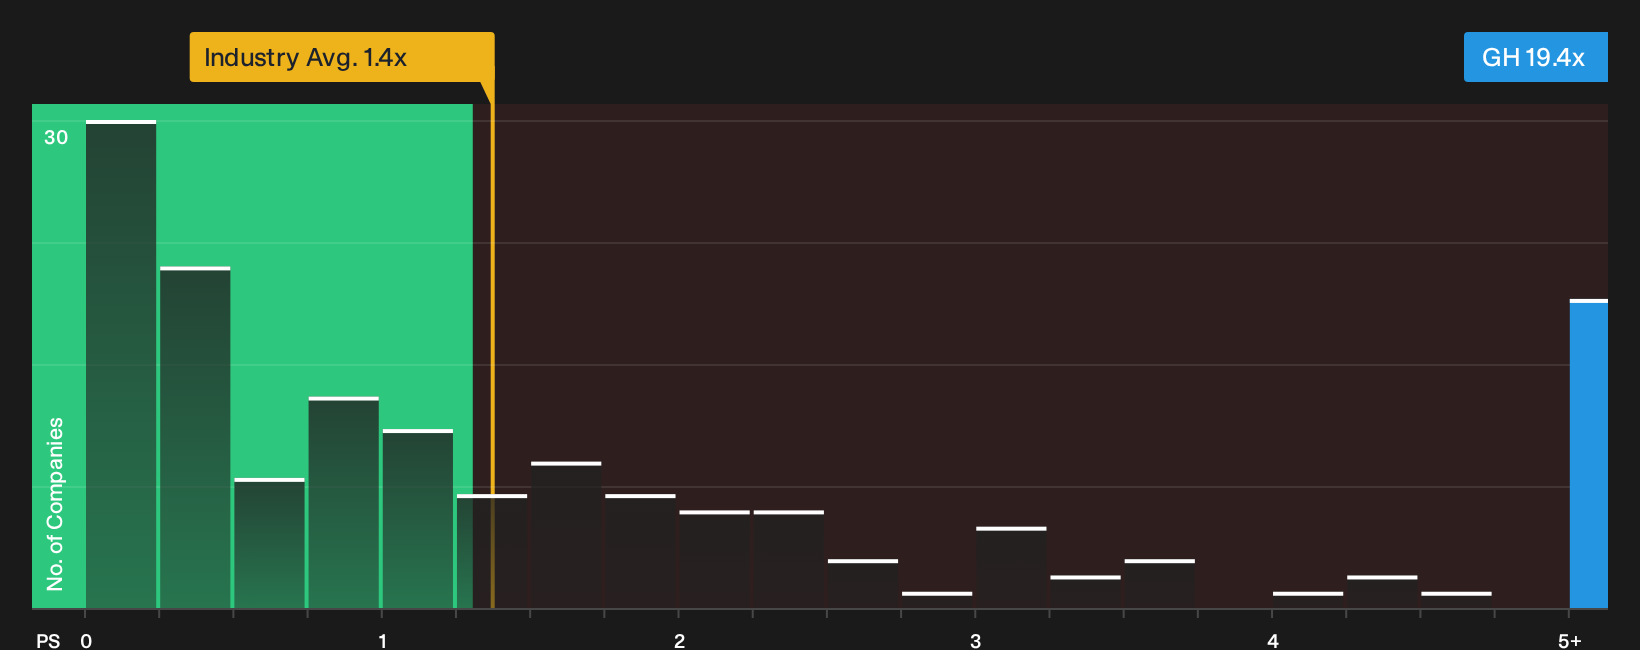
That 16% undervaluation story meets a very different message when you look at simple sales multiples. Guardant Health trades on a P/S of 19.4x, while the US Healthcare sector averages 1.4x and the fair ratio estimate sits at 10x. The gap points to a lot of expectation already in the price. The question is whether future execution can live up to that premium.
Before leaning on the analyst target alone, it helps to see how this rich P/S level fits into a fuller breakdown of Guardant Health's valuation set up: See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Guardant Health so far. If you want to move fast and base your view on the numbers, take a closer look at the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Guardant Health?
If Guardant Health has your attention, do not stop here. Broaden your watchlist with a few focused stock ideas that target very different edges of the market.
- Target powerful upside skew by scanning hand picked 8 elite penny stocks with strong financials that pair tiny market caps with balance sheets that still hold up under closer inspection.
- Zero in on mispriced quality by reviewing a curated 34 high quality undervalued stocks that filters for solid cash generation and cleaner finances than headline multiples suggest.
- Dial down portfolio stress by running through a 29 resilient stocks with low risk scores built around resilient balance sheets and more stable business profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com