


EN
Cigna (CI) Stock May Still Be A Bargain After Lead To One Vision
Cigna Group has delivered a 48.5% share price gain over the past five years, and recent price swings now put fresh attention on whether that move is backed up by its earnings power. With the stock last closing at US$295.19, the question is how much of the healthcare group's profit story is already built into that tag.
- The 48.5% total return over five years puts real weight on whether Cigna Group's current earnings justify that climb or ask investors to pay up for more.
- Management's "Lead to One" plan to personalize healthcare, from specialty pharmacy to integrated services, can influence how quickly earnings grow and how reliably cash flows support today's valuation.
- Your read on Cigna Group is one view; the desks covering it have another. See what analysts think Cigna Group's shares could be worth.
For investors, the debate is whether Cigna Group's current share price is reasonably aligned with what its earnings can support today and over the coming years.
If you are considering whether Cigna Group's current P/E provides sufficient earnings support for the price, it may be helpful to compare that same question across 34 high quality undervalued stocks.
Is Cigna Group a Bargain on Earnings?
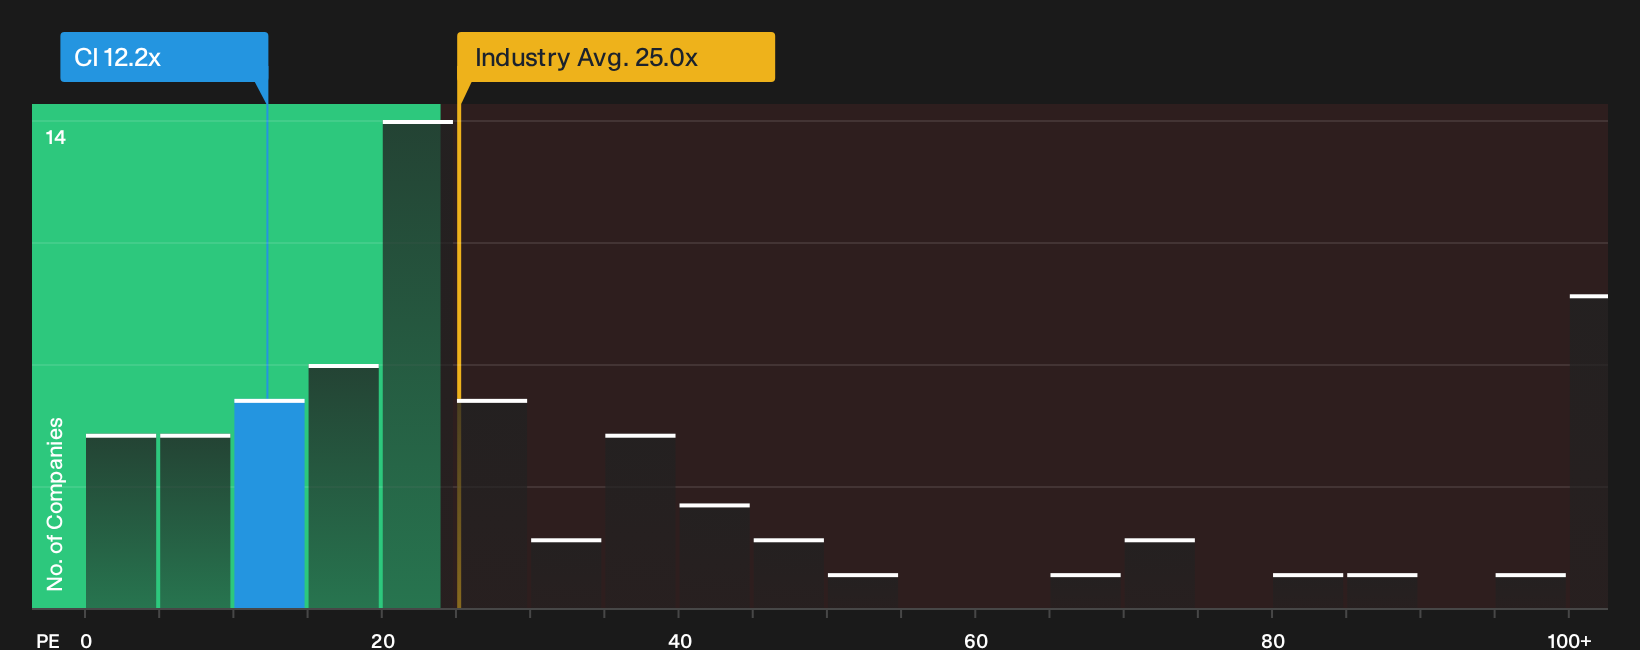
The P/E ratio fits Cigna Group because earnings remain the main yardstick investors watch in large, mature healthcare insurers. At roughly 12.2x earnings, the stock trades at a clear discount to the broader Healthcare sector, where the average P/E sits near 25.0x, and well below the peer group cluster around 30.2x.
Because the fair benchmark multiple for Cigna Group screens higher than the current figure, the model framework treats the shares as undervalued on this earnings lens. The "Lead to One" plan to personalize care and integrate services has brought fresh attention to the story, yet despite that focus the market still prices the business below what similar healthcare groups command on P/E. If you want to see how far the current valuation sits from that tailored fair multiple, you can check the detailed comparison in. Explore the numbers behind Cigna Group's P/E valuation.
The Cigna Group Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where Cigna Group's P/E puzzle leaves off by spelling out which combinations of future growth, profitability and earnings power would need to play out for the stock to be worth materially more or materially less than today’s price on the Community page. Each scenario ties a fair value estimate to a specific view of Cigna Group's potential catalysts and key risks so you can track over time which storyline appears to be unfolding.
One of the top community narratives on Cigna Group: 13% undervalued
"Cigna Group is capitalizing on the growing demand for specialty pharmacy and care services, with recent 22% pretax earnings growth in Specialty & Care Services..."
Discover why this Narrative puts Cigna Group at 13% undervalued.
One more check on Cigna Group that belongs beside the valuation work
Price tags and earnings multiples only tell part of the story, since Simply Wall St's broader review has also surfaced specific concerns that investors may want to weigh before leaning on the P/E alone. Take a closer look at 1 warning sign before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com