


EN
Blue Owl Capital (OWL) Earnings Strength Keeps Valuation Debate Alive
Blue Owl Capital (OWL) is back in the spotlight after reporting third quarter results on 29 October 2026 that showed higher revenue, improved net income and an affirmed quarterly dividend of US$0.23 per Class A share.
The recent earnings and dividend update comes after a volatile stretch for Blue Owl Capital, with the share price up 16.96% over 30 days and 13.70% over the past week, yet the year-to-date share price return has fallen 30.63% and the 1-year total shareholder return has declined 29.05%. This suggests short-term momentum has picked up even as longer-term performance remains weak.
Compare Blue Owl Capital's rebound with a hand picked pool of income focused financials in the 4 dividend fortresses.
Blue Owl Capital now trades at US$10.62 while analyst targets cluster closer to US$12.92, leaving a clear gap. Is that discount a genuine margin of safety, or a value trap in disguise?
Most Popular Narrative: 43% Undervalued
At a last close of $10.62 versus a widely followed fair value estimate of $18.75, the current pricing for Blue Owl Capital reflects a sizeable gap that hinges on whether its fund flows and real asset build out translate into durable fee income.
A key factor is whether Blue Owl Capital continues to convert its large pool of non-fee-paying assets under management, its growing data center and net lease platforms, and its expanding private wealth and institutional channels into stable, fee-based revenue, while managing private credit redemption pressures and project-specific risks such as Jupiter and Loparex.
See why 10 investors see Blue Owl Capital as 43% undervalued.
Result: Fair Value of $18.75 (UNDERVALUED)
Still, the bullish Blue Owl Capital story can crack if heavy redemptions in private credit vehicles persist or if project issues like Jupiter and Loparex deepen.
Find out about the key risks to this Blue Owl Capital narrative.
Another View: What Blue Owl Capital's Earnings Multiple Signals
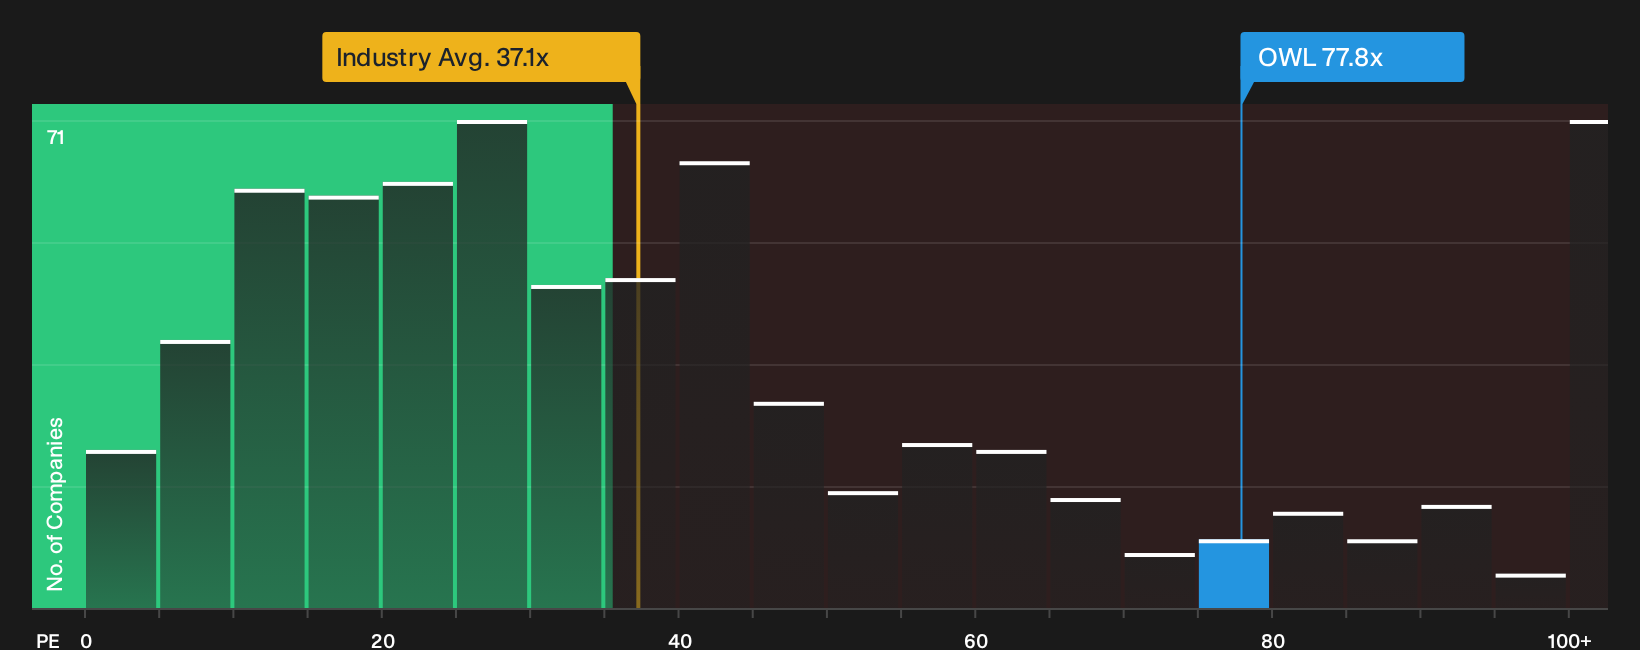
The fair value narrative leans on earnings forecasts and optimism about fee growth. A simple P/E check tells a very different story. Blue Owl Capital trades on a P/E of 77.8x, compared with 37.1x for the US Capital Markets industry and 29.9x for peers, while the fair ratio sits at 20x. That gap suggests the share price already bakes in a lot of good news. If earnings stumble or sentiment cools, how comfortable are you with that kind of valuation air pocket?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Blue Owl Capital so far, right? Use the data, pressure test both the risks and potential upsides, then weigh the 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Blue Owl Capital?
If Blue Owl Capital has sharpened your thinking, do not stop there. A broader watchlist gives you options when market mood and valuations shift.
- Target potential mispricing by scanning companies that pass strict quality and valuation filters using the 34 high quality undervalued stocks.
- Prioritise resilience by reviewing a list of solid balance sheet and fundamentals (24 results) that can better handle funding shocks and earnings bumps.
- Get ahead of the crowd by spotting early-stage opportunities in the 19 high quality undiscovered gems before they attract wider attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com