


EN
Could Revenue Rebound Alter The Investment Case For Talos Energy Stock (TALO)?
- Talos Energy is set to report Q3 earnings after market close, with analysts expecting revenue to grow 19% year on year following last year's decline.
- The central question is whether Talos Energy can translate its operational track record into a revenue rebound that supports its margin and free cash flow goals.
- Attention now turns to how Talos Energy's anticipated 19% revenue growth might influence the current investment narrative around efficiency and cash generation.
Scan beyond Talos Energy and line up other potential beneficiaries of stronger upstream sentiment with our hand picked 34 high quality undervalued stocks that match solid cash generation and balance sheet discipline.
Talos Energy Investment Narrative Recap
To own Talos Energy, you need to be comfortable with a Gulf of Mexico focused producer that is still loss making but aiming to squeeze more out of its existing asset base. The big belief is that efficiency gains and integration of recent acquisitions can offset heavy capex and decommissioning demands. The upcoming earnings print, with expectations for 19% revenue growth, speaks directly to that operational story.
The most important short term catalyst is whether Talos Energy can show that higher production and efficiency are feeding through to steadier cash generation. The key risk is unchanged. Weather, basin specific regulation and rising abandonment costs can still hit volumes and expenses, especially when insider selling and a relatively new management team already sit at the back of investors minds.
With Q3 results around the corner, the earlier focus on integrating the Na Kika and Coulomb interests from Shell feels especially relevant. Those assets are expected to contribute additional proved reserves and daily output, so the upcoming report gives you a cleaner look at how well they are bedding into the broader portfolio and whether operating costs are staying under control.
If Talos Energy shows that these fields support its US$100m per year efficiency and cost reduction plan, that supports the narrative that higher scale can co exist with better capital discipline. Any signs of slippage on spending or decommissioning obligations would sit awkwardly next to that story and may refocus attention on balance sheet usage and the timing of any future buybacks or M&A.
Talos Energy earnings assumptions and what they imply
Analysts are effectively asking Talos Energy to execute on a slow and steady plan rather than a moonshot. The current consensus builds in revenue expansion of 4.5% per year over the next 3 years, alongside a swing from a loss making margin of 20.5% today to a modest 3.2% profit level in that same timeframe. That path relies on the Gulf of Mexico portfolio doing enough heavy lifting to support higher utilization of existing infrastructure and tighter control of costs as the acquired fields settle into the system.
The earnings bridge is where the leap becomes clearer. Forecasts call for Talos Energy to move from a loss of US$405.0 million today to earnings of US$73.3 million by about 2029, which is roughly a US$478 million improvement. That headline number masks wide dispersion in the analyst set, with the most optimistic penciling in US$381.0 million of profit and the most cautious still assuming a small loss of US$10.2 million. For you as an investor, that spread signals that the market is still debating how durable the efficiency program and Gulf focused growth plan really are.
To line this up with valuation, the consensus assumes Talos Energy trades on a P/E of 57.6x those projected 2029 earnings, versus a current multiple of 7.5x on today’s loss making base and an industry level of 12.4x. That is a big premium to the wider US oil and gas peer group. For the thesis to hold together, you would need to be comfortable that a combination of improving profitability, capital discipline and balance sheet management justifies paying a higher multiple than more diversified producers.
Talos Energy's narrative projects US$2.3b revenue and US$73.3 million earnings by 2029. This rests on 4.5% yearly revenue growth and an earnings improvement of about US$478 million from the current loss of US$405.0 million.
Uncover why Talos Energy's fair value indicates a 31% potential upside to its current price before the market closes that discount.
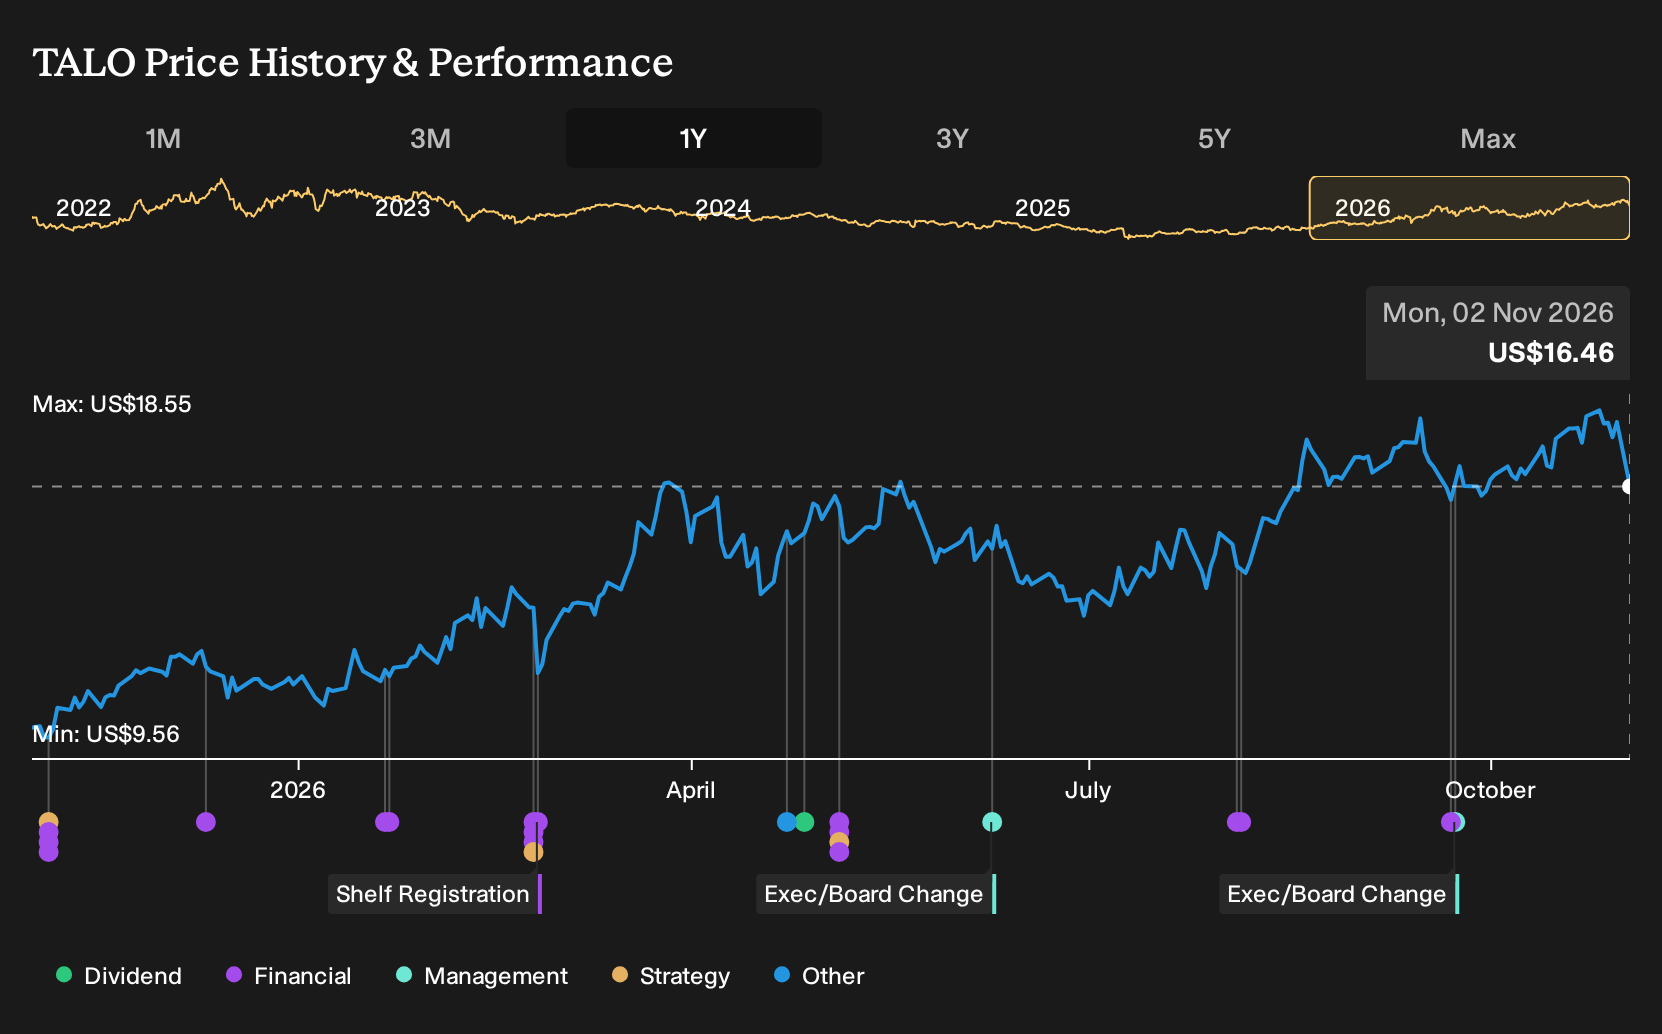
Exploring Other Perspectives
One alternate view leans hard on Talos Energy’s most optimistic free cash flow story. Bullish analysts were penciling in US$2.5b of revenue and US$376.8 million of earnings by 2029, far above consensus, assuming Mexico Block 29, Honduras and capital returns all click. With tomorrow’s 19% growth test coming up, those stories may shift.
Explore 3 other Talos Energy fair value estimates, including one that suggests as much as 489% upside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Talos Energy research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Talos Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Talos Energy's overall financial health at a glance.
Looking for more investment ideas beyond Talos Energy?
If the Talos Energy setup has you thinking about portfolio upgrades, it can help to line up a few ready made stock shortlists that match different risk and income preferences.
- If capital preservation is front of mind, start with a group of businesses that pair steadier fundamentals with measured risk using our 29 resilient stocks with low risk scores.
- For investors hunting for value supported by balance sheet strength, run your eye over a list of solid balance sheet and fundamentals (24 results) that filters for financial resilience first.
- Those looking for yield can focus on dependable income streams by scanning a curated mix of 4 dividend fortresses that already clear a 5% threshold.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com