


EN
Ahead of Qualcomm Earnings, Here's What Barchart Data Says Comes Next for QCOM Stock
The derivatives market believes Qualcomm (QCOM) shares will tumble in the weeks following its fiscal Q4 earnings, which are scheduled to be released on Nov. 4. And Bernstein analysts aren’t particularly bullish on QCOM heading into the quarterly print, either. In their latest report, they maintained a “Market Perform” rating on the company and lowered their price target to $155.
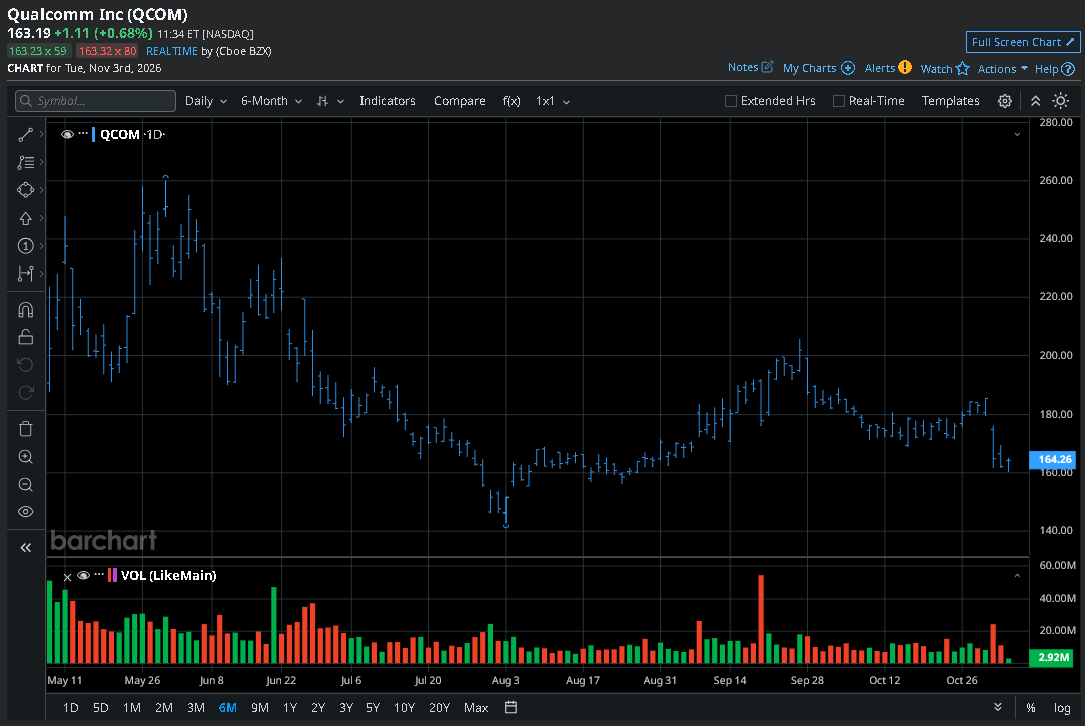
Qualcomm stock has already been in a downtrend since late May, currently trading about 35% below its year-to-date high.
Options Sentiment Is Bullish for Qualcomm Stock
Consensus is for Qualcomm to record $1.46 in earnings per share (EPS) for its fourth fiscal quarter, which would represent a nearly 43% decline on a year-over-year basis. Traders seem to believe that contraction would trigger a selloff in QCOM shares in the weeks ahead, as evidenced in the put-to-call ratio of 1.06x on options expiring Nov. 20.
According to Barchart’s latest data, the lower price on those contracts is set at about $147, signaling potential downside of 9.52% over the next two weeks.
Qualcomm is trading for about 26x forward earnings as of this writing, which looks stretched for a company set to report a major year-over-year decline.
Bernstein Lowers Price Target for QCOM Shares
In their research report, Bernstein analysts acknowledged Qualcomm’s diversification efforts but said smartphones still account for the bulk of its chipset sales.
Rising memory prices and supply constraints could result in continued weakness in the global handset market, making it increasingly difficult for QCOM to stage a comeback, they told clients.
Bernstein admitted that data center strength could drive Qualcomm earnings higher in fiscal 2028 and fiscal 2029, but not in the near term. Its price target assigns a 15x multiple on the firm’s estimated fiscal 2028-2029 earnings per share.
How Wall Street Recommends Playing Qualcomm
Other Wall Street firms seem to disagree with Bernstein’s dovish stance on Qualcomm, though.
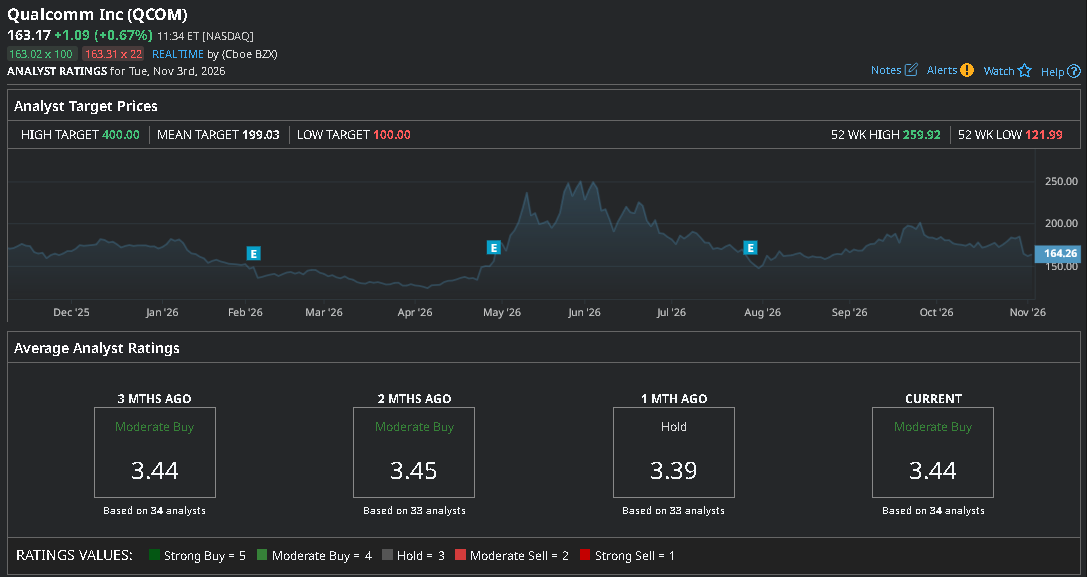
According to Barchart, the consensus rating on QCOM stock remains at “Moderate Buy,” with the mean price target of about $199 indicating potential upside of roughly 23% from current levels.
On the date of publication, Wajeeh Khan did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.