


EN
AMETEK (AME) Beat Expectations And Raised Outlook, Is The Stock Fully Priced?
AMETEK (AME) just posted record third quarter 2026 results, reporting US$2.22 billion in sales and adjusted earnings per share that exceeded consensus estimates, and raised its full-year sales and earnings outlook.
At a share price of US$241.91, AMETEK has eased over the past month with a 30 day share price return of 4% and a 90 day move of 4.8% lower. However, the year to date share price return of 15.7% and a 1 year total shareholder return of 22.5% signal that longer term momentum remains intact, supported by strong earnings delivery and interest in its exposure to aerospace, defense and semiconductor linked instrumentation.
Scan how AMETEK’s record quarter compares with other industrial and electronics plays by checking the hand picked list of solid balance sheet and fundamentals (24 results) in similar sectors.
After that kind of earnings beat and guidance raise, yet with AMETEK still easing off recent highs, are you looking at more upside ahead or a lot of good news already priced in as you weigh the valuation next?
Most Popular Narrative: 13% Undervalued
Against AMETEK’s last close at $241.91, the most followed narrative points to a fair value of about $278.33. This frames the stock as trading at a discount that relies heavily on execution in higher value electronics, aerospace and energy infrastructure.
Growing exposure to AI driven semiconductor and data center infrastructure, supported by strong orders and design wins in optics, metrology, embedded computing and power simulation, is expected to support multi-year revenue growth and earnings from these higher value instrumentation and electronics platforms.
See why 19 investors see AMETEK as 13% undervalued.
Result: Fair Value of $278.33 (UNDERVALUED)
Still, the bullish AMETEK story can wobble if investors pull back from paying premium P/E multiples, or if acquisitive growth and integration fall short of expectations.
Find out about the key risks to this AMETEK narrative.
Another View: AMETEK Looks Pricey On Earnings
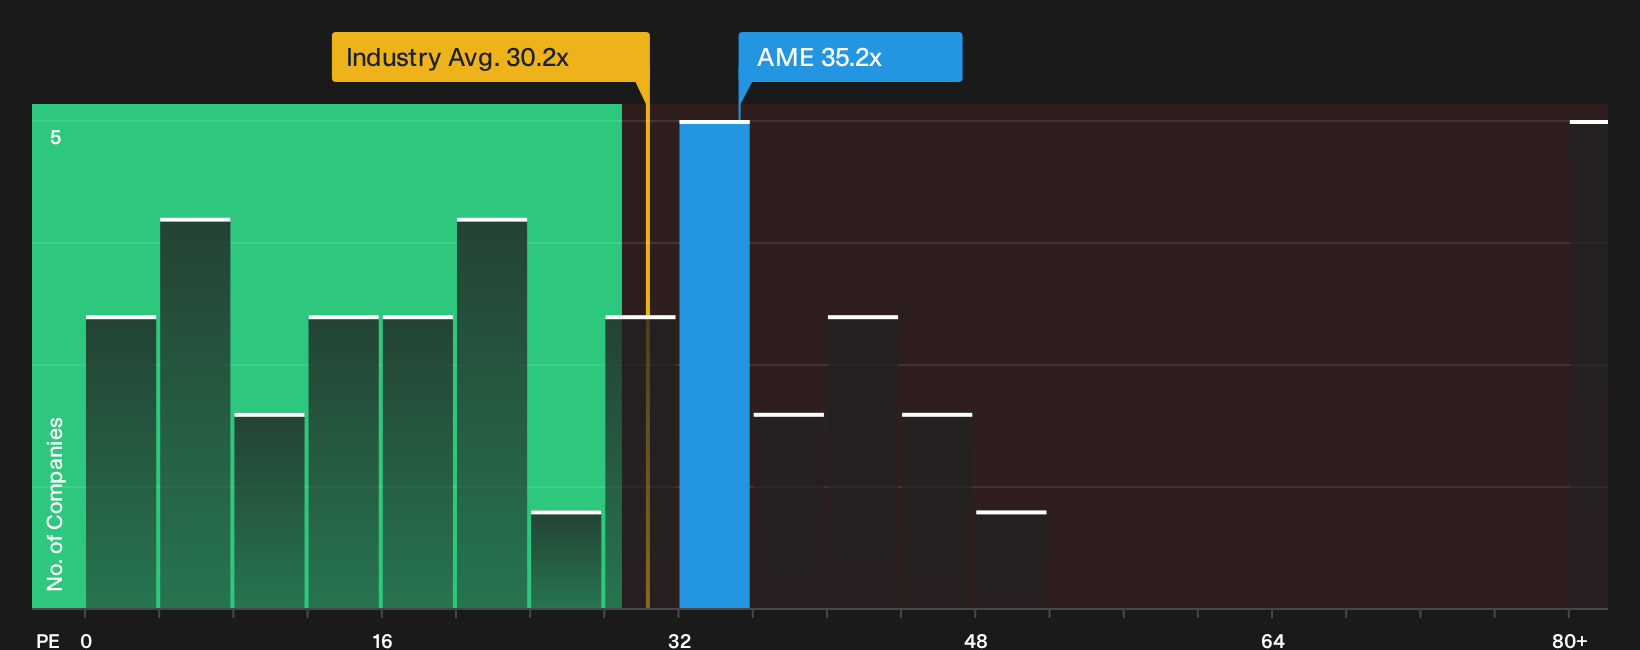
That 13% “undervalued” fair value story looks very different once you consider AMETEK through its P/E. The shares trade on 35.2x earnings compared with 30.2x for the US Electrical industry and an estimated fair ratio of 26.3x. That wide gap points more toward valuation risk than a clear bargain, so the question is how comfortable you are paying up for this quality.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of optimism and valuation questions around AMETEK has you thinking, check the underlying drivers yourself and pressure test the 2 key rewards.
Looking for more AMETEK style investment ideas?
If AMETEK has sharpened your focus on quality and value, broaden your watchlist now so you do not miss the next opportunity hiding in plain sight.
- Target stronger upside potential by scanning for companies flagged as 19 high quality undiscovered gems before the crowd catches on.
- Prioritise capital resilience by reviewing a curated 29 resilient stocks with low risk scores that can help steady your portfolio through different market conditions.
- Hunt for compelling entry points with a data driven 34 high quality undervalued stocks that highlights stocks trading below their assessed worth.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com