


EN
NVR (NVR) Earnings Reset Puts Its Valuation Debate Back In Focus
Earnings reset puts NVR’s recent returns in context
NVR (NVR) just posted third quarter results showing net income and earnings per share below last year, a shift that helps explain recent moves in the stock and its current valuation debate.
The earnings reset arrived just as momentum in NVR’s share price was starting to rebuild, with a 1-day share price return of 5.14% and a 7-day gain of 9.38%. However, the year-to-date share price return is down 13.93% and the 1-year total shareholder return has declined 11.41%, while the 5-year total shareholder return is up 23.14%. This combination signals fading medium-term enthusiasm but a still positive long-run record.
Scan how NVR compares with other potential opportunities by reviewing a hand picked 34 high quality undervalued stocks that pairs solid fundamentals with more attractive pricing signals.
NVR still looks like a high quality builder with meaningful earnings, yet the recent rebound follows a year where shareholders lost ground. Is that long term strength available at a sensible price today?
Most Popular Narrative: 67% Overvalued
NVR closed at $6,265.10, while the leading narrative fair value sits at $3,758. According to this view, the current share price is framed as rich relative to that anchor.
NVR converts the most capital-intensive, most cyclical, most balance-sheet-fragile activity in U.S. industrial business, residential land development, into a software-like compounder with 30% ROIC and net-cash balance sheets. The mechanism is the Lot Purchase Agreement (LPA) model: NVR pays non-refundable deposits of approximately 10% of finished lot value to third-party developers for the right to take down lots on a quarter-by-quarter basis. The capital that peers tie up in raw land, NVR redeploys into share buybacks. The risk that peers absorb in housing downturns, NVR walks away from by forfeiting deposits.
See why 6 investors see NVR as 67% overvalued.
Result: Fair Value of $3,758 (OVERVALUED)
Still, the NVR narrative could be tested if the Lot Purchase Agreement model faces tighter developer terms, or if weaker housing demand leaves deposits at greater risk.
Find out about the key risks to this NVR narrative.
Another View on NVR’s Valuation
NVR’s most popular community narrative flags the stock as rich versus a $3,758 fair value, yet the SWS DCF model points the other way. On that framework, NVR at $6,265.10 sits below an estimated future cash flow value of $7,768.71, indicating undervaluation instead of excess.
This clash between narrative pricing and cash flow analysis raises a simple question. Which do you view as more informative: crowd caution around entry price, or a cash flow model that suggests the current level leaves potential upside on the table.
Look into how the SWS DCF model arrives at its fair value.
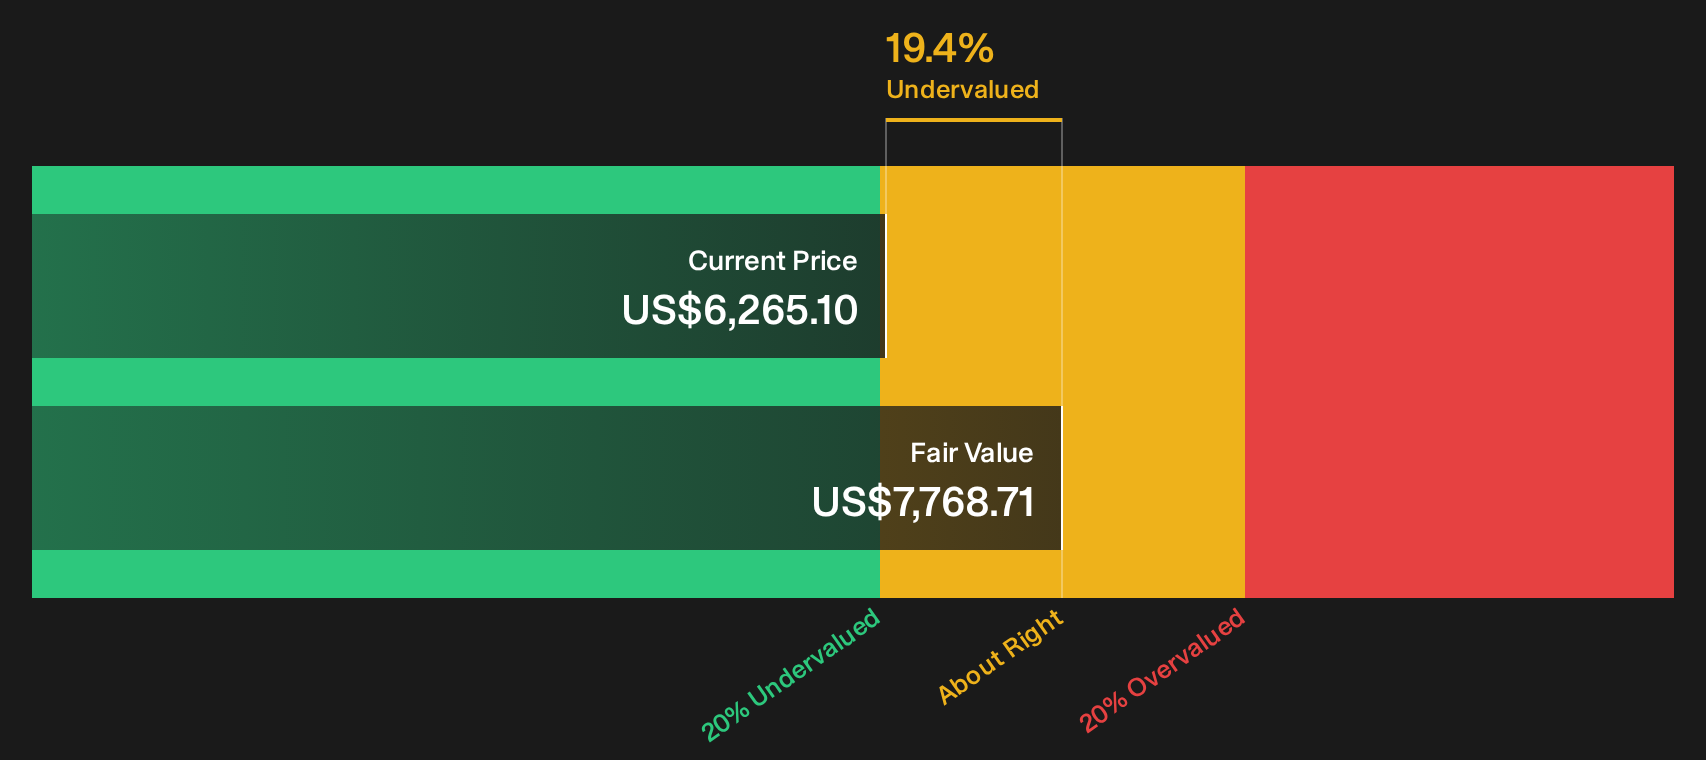
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out NVR for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 34 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the mixed signals around NVR leave you torn, move quickly to inspect the underlying data, pressure test the narratives, and weigh the 1 key reward.
Looking for more NVR investment ideas?
Do not stop your work with NVR alone. Broaden your watchlist using focused screens that surface clearer opportunities before the crowd pays attention.
- Target resilient cash flows by scanning a 4 dividend fortresses designed for investors who want income without ignoring balance sheet strength.
- Hunt for quality at a discount through a 19 high quality undiscovered gems that highlights businesses with solid fundamentals yet limited market attention.
- Reduce portfolio stress by filtering for a 29 resilient stocks with low risk scores so you focus on companies with sturdier financial profiles and fewer red flags.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com