


EN
Why Now Could Be the Right Time to Buy SoFi Stock
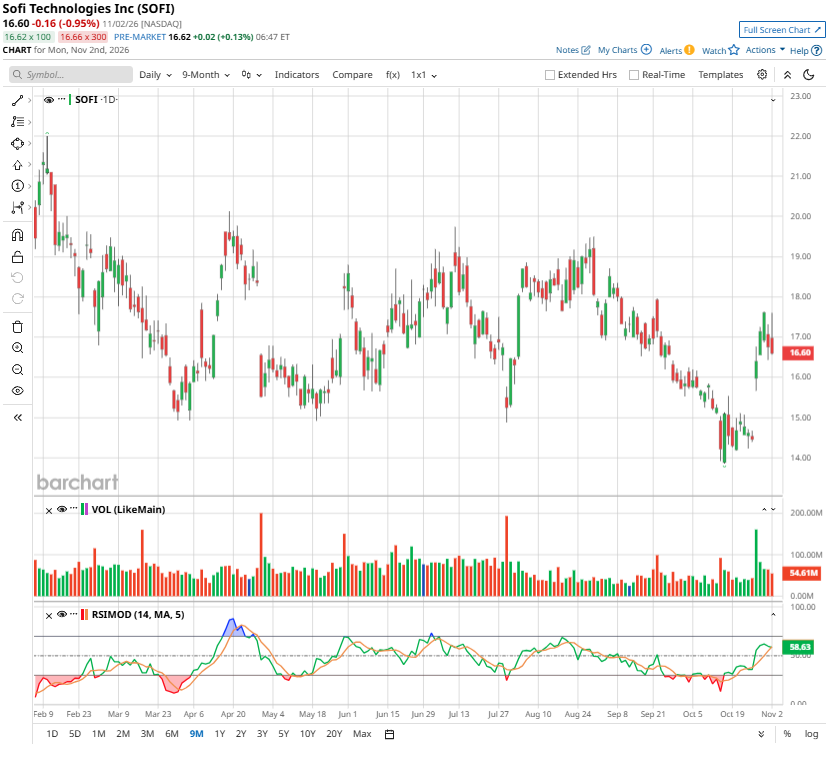
SoFi's (SOFI) stock has struggled over the past year, falling 45% and significantly underperforming the broader market. However, the significant decline in its share price has improved its risk-reward profile, especially as the financial technology company's fundamentals remain strong.
SoFi has continued to deliver solid quarterly results and has raised its full-year outlook, signaling solid growth ahead. Its expanding member base, increasing adoption of multiple products by existing customers, and growing contribution from non-lending businesses are all helping strengthen its business model and diversify revenue streams.
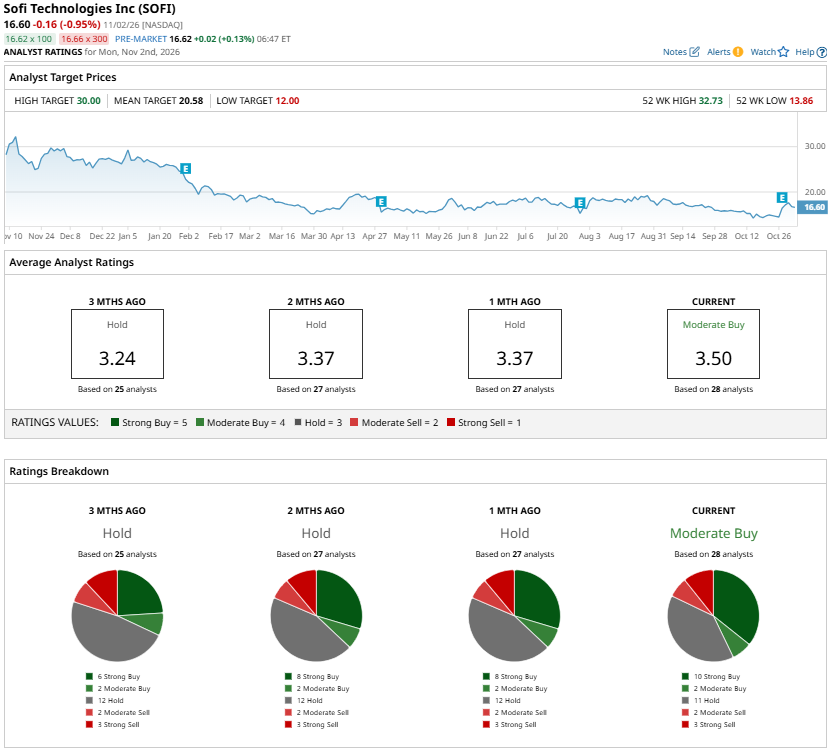
Adding to the positive outlook, analyst sentiment toward SOFI stock has also improved over the past month, making it attractive.
Multiple Growth Drivers Strengthen Outlook
SoFi is demonstrating strong operating momentum, with growth coming from several areas of its business. The company is attracting new members, encouraging existing customers to use more of its products, and generating higher revenue from its expanding financial services platform. This is helping SoFi to diversify its top line and deliver profitable growth in the quarters ahead.
SoFi’s customer acquisition and engagement metrics remain solid, supporting its growth. Members increased 35% year-over-year (YoY) to 17.1 million, while total products grew about 44% to 26.7 million. Notably, 51% of new products came from existing members, highlighting the company’s ability to deepen customer relationships. Products per member also increased to approximately 1.56 from 1.47 a year earlier, pointing to stronger engagement and effective cross-selling.
SoFi’s profitability is improving alongside solid top-line growth. Adjusted EBITDA was $470 million, up 70% YoY, while the EBITDA margin expanded. Adjusted net income increased 74%, and adjusted EPS jumped 64% from the previous year.
Revenue diversification represents another important catalyst for SOFI stock. Fee-based revenue reached $571 million in Q3, accounting for 42% of total revenue, compared with 39% in the preceding quarter. This progress moves SoFi closer to its long-term objective of generating half of its revenue from fee-based activities.
Meanwhile, the Lending segment continues to perform well. Loan growth, favorable cash interest collections, lower-than-anticipated credit losses, and a deposit-funded balance sheet continue to support lending economics.
Importantly, SoFi is also becoming less dependent on lending. Financial services offerings now account for approximately 87% of its products. The company has eight scaled businesses generating more than $100 million in annualized revenue, with most growing above 30%. These include businesses generating more than $2 billion and $1 billion in annualized revenue, alongside six others exceeding $100 million. Newer initiatives, including cryptocurrency, SoFi Plus, small and medium-sized business lending, commercial banking, and SoFiUSD, provide additional avenues for future expansion.
Management’s preliminary 2027 outlook points to continued growth. SoFi expects adjusted net revenue of $6.4 billion, up 27%, and adjusted EBITDA of approximately $2.24 billion, compared with $1.66 billion expected in 2026. Adjusted EPS is projected to reach $0.90, approximately 48% above the 2026 estimate of $0.61.
Overall, SoFi has multiple catalysts supporting its growth. Its growing member base, stronger monetization, rising fee-based revenue, and improving profitability will support its stock. Further, benefits from newer initiatives will likely accelerate its growth.
Analysts’ Sentiment Has Improved for SOFI Stock
Analyst sentiment toward SOFI stock has strengthened over the past month, indicating a gradual improvement in Wall Street’s outlook. Of the 28 analysts covering the company, 10 currently rate it a “Strong Buy,” up from eight a month earlier. This shift has also lifted SoFi’s overall consensus recommendation from “Hold” to “Moderate Buy,” suggesting analyst expectations are becoming more positive.
SOFI Stock Poised for a Solid Recovery
SoFi’s fundamentals remain solid. Strong member growth, higher customer engagement, expanding fee-based revenue, and improving profitability indicate sustained growth ahead. Moreover, management’s optimistic 2027 outlook and improving analyst sentiment strengthen the company’s long-term prospects.
While SoFi is expected to deliver solid growth, the significant decline in its share price offers an attractive entry point.
On the date of publication, Sneha Nahata did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.