


EN
Why Did Cheniere Energy Partners (CQP) Move Today?
Why Cheniere Energy Partners Is Back On Investor Radars
Cheniere Energy Partners (CQP) has just paired stronger third quarter financial results with a higher floor on its 2026 cash distribution guidance, putting its income profile in sharper focus for yield driven investors.
Recent trading has cooled a little, with the share price down 3.15% over the last day and 2.66% over the past week, even after a 5.22% 1 month gain and a 19.46% year to date share price return from Cheniere Energy Partners. That softer short term move sits against a much stronger income driven picture, with total shareholder return of 33.29% over one year and 107.09% over five years, as investors react to higher earnings, firmer 2026 distribution guidance and the planned Sabine Pass liquefaction expansion.
Scan beyond Cheniere Energy Partners and compare its income story with other high distribution players using our curated 4 dividend fortresses for yield focused ideas.
After a strong income run and a recent price pause, is Cheniere Energy Partners still offering meaningful upside, or has the bulk of the return already arrived before you even look at valuation?
Price-to-Earnings of 11.3x: Is It Justified For Cheniere Energy Partners?
On valuation, Cheniere Energy Partners is trading on a P/E of 11.3x and recent data points to that level representing value compared to both its own fair ratio and sector peers.
The P/E ratio compares the current share price to earnings per unit and gives a quick sense of how much investors are paying for each dollar of profit. For a capital intensive LNG exporter with long lived assets and contracts, earnings carry a lot of weight because they reflect how well those assets are being monetized.
Here, the picture suggests CQP may be trading at a relatively low valuation. The units are described as good value versus the US Oil and Gas peer average P/E of 17.6x, which is a sizeable gap. The units also trade below an estimated fair P/E of 15x, so there is a spread between what the market currently pays and a level that regression based work indicates as fair value based on recent relationships.
That relative discount is accompanied by a few quality markers in the recent record. Earnings grew 49% over the past year, compared with the wider Oil and Gas industry at 39.4%. Profit margins are currently 23.7%, higher than 18% a year ago, and earnings have risen by 10% per year over the past 5 years. In addition, the units are trading 6.3% below an internal fair value estimate based on future cash flows, with the SWS DCF model indicating a value of $68.84 against a last close of $64.51. Together, those pieces suggest that the market is currently pricing Cheniere Energy Partners below both its recent earnings performance and a modeled view of its cash generation.
Explore the SWS fair ratio for Cheniere Energy Partners.
Result: Price-to-Earnings of 11.3x (UNDERVALUED)
Still, the Cheniere Energy Partners story faces pressure points, including annual net income contraction of 4.6% and revenue growth of only 4.2%, which could challenge the valuation case.
Find out about the key risks to this Cheniere Energy Partners narrative.
Another View On Cheniere Energy Partners’ Valuation
The first pass using earnings multiples paints Cheniere Energy Partners as inexpensive. A second look through the SWS DCF model reaches a similar destination, with the units trading around $64.51 versus an estimated future cash flow value of $68.84, which leans toward underpriced rather than stretched. The real question is whether you trust the cash flow assumptions more than the current market mood.
Look into how the SWS DCF model arrives at its fair value.
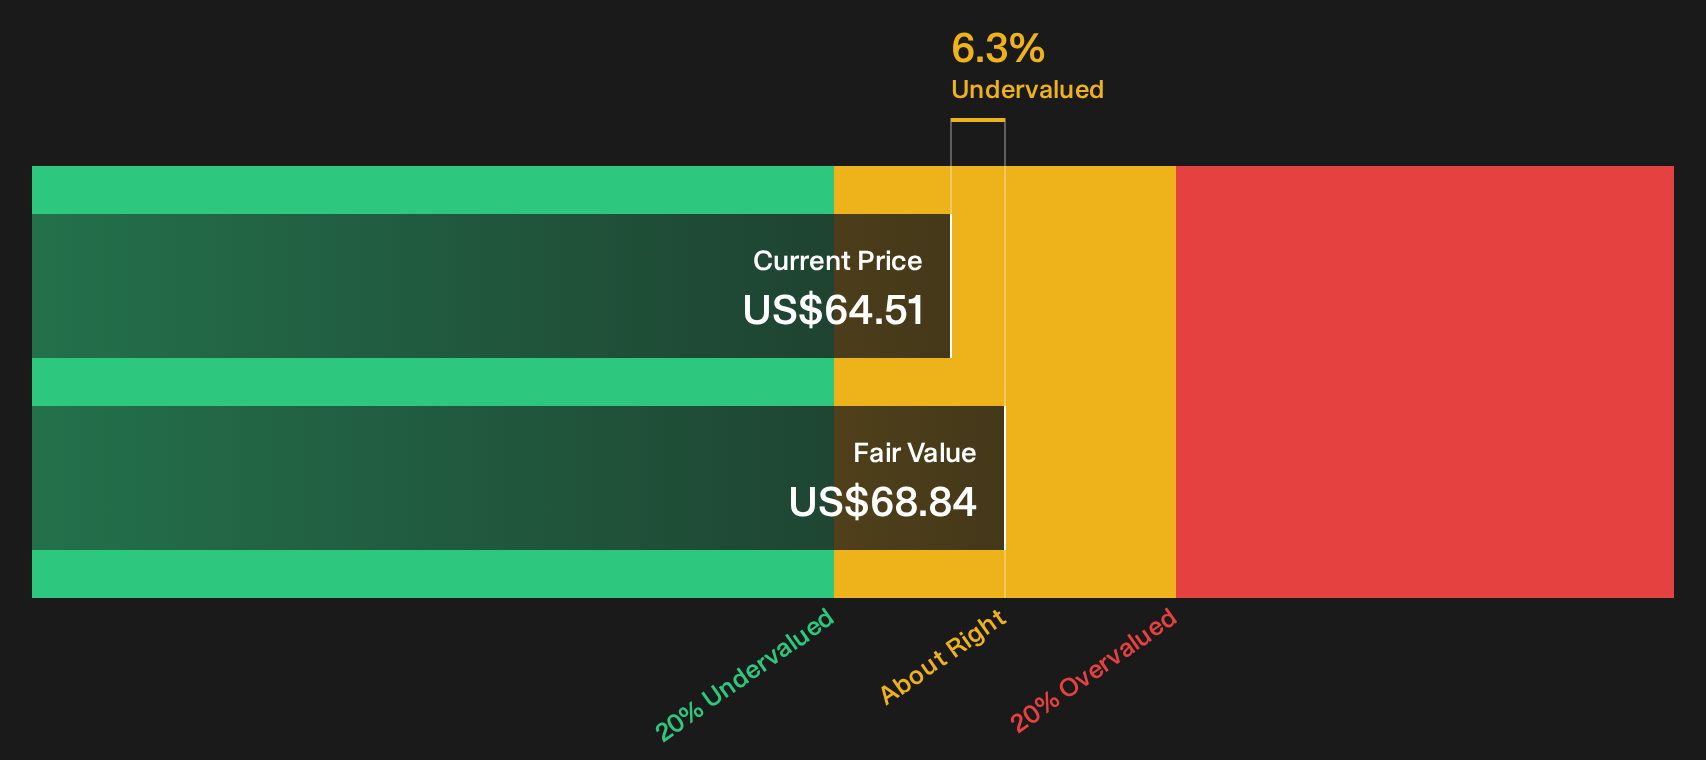
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Cheniere Energy Partners for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 34 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Cheniere Energy Partners so far. If you want to move quickly and own your view, consider both sides of the story, then tap into the 3 key rewards and 3 important warning signs
Looking For More Investment Ideas Beyond Cheniere Energy Partners?
Do not stop with Cheniere Energy Partners. Broaden your watchlist with fresh ideas sourced from Simply Wall Street screeners that focus on income, quality and resilience.
- Target resilient businesses that aim to protect your downside by scanning a 29 resilient stocks with low risk scores that filters for sturdier balance sheets and steadier fundamentals.
- Hunt for value opportunities by checking a 34 high quality undervalued stocks that highlights companies combining stronger cash generation with share prices that lag underlying metrics.
- Prioritise balance sheet strength by running through a list of solid balance sheet and fundamentals (24 results) that surfaces firms with healthier leverage and more robust financial cushions.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com