


EN
3 Canadian Insider Owned Growth Stocks To Own In November 2026
The Reserve Bank of Australia just lifted interest rates to 4.85%, the highest cash rate since 2008. Higher borrowing costs tend to punish weaker businesses and reward companies that can still grow from their own momentum. That is where fast growing Canadian firms with significant insider skin in the game become interesting. This article walks through three such high growth, high ownership stocks from our screener.
The three stocks highlighted here offer a compelling starting point if you want exposure to fast growing businesses where insiders and analysts are broadly aligned on the outlook. However, if you want the names that matter most, these 9 high growth high conviction stocks are the strongest companies we've found.
Tenaz Energy (TSX:TNZ)
Overview: Tenaz Energy is a Calgary based oil and gas producer focused on natural gas development in the Dutch North Sea and Canadian assets.
Operations: Tenaz Energy generates about CA$497 million from petroleum and natural gas sales, with roughly CA$460 million sourced from the Netherlands and CA$38 million from Canada.
Market Cap: CA$2.52b
Tenaz Energy fits this fast growth, high insider ownership theme through its push into European natural gas, where near term volume and cash flow potential rely heavily on how efficiently it scales Dutch North Sea production.
"The build out of high quality Netherlands gas production, supported by multiple rigs across TEN operated, ONE Dyas operated and ENI operated wells, increases exposure to European gas pricing and can support higher revenue as more volumes move into the sales mix."
The real swing factor is how one pressure on future European gas pricing ultimately feeds through to Tenaz Energy’s margins and growth trajectory.
That pricing pressure is exactly what the full narrative for Tenaz Energy unpacks in detail, including how Tenaz Energy could respond if European gas and project timelines decouple.

Colliers International Group (TSX:CIGI)
Overview: Colliers International Group is a Toronto based firm that helps investors and occupiers manage, finance, and engineer commercial real estate globally.
Operations: The business generates about US$3.5b from commercial real estate services, US$1.9b from engineering projects, and US$0.6b from investment management activities.
Market Cap: CA$6.9b
Colliers International Group fits this fast growing, high insider ownership theme through its capital markets and investment management arm. In that segment, fee income and assets under management tend to scale when real estate activity and investor appetite for long dated vehicles improve.
"The growing interest from institutional and private wealth channels in alternative asset classes such as data centers, student housing, infrastructure, and credit solutions is driving segment diversification and AUM growth in the investment management business, supporting future recurring fee revenue and higher net margins."
The open question is how one pressure on funding costs and leverage eventually feeds through to those margin ambitions investors care about most.
That funding squeeze is exactly where the full narrative for Colliers International Group shows whether Colliers International Group has an accelerating fee engine or just fragile leverage in disguise.

Cascades (TSX:CAS)
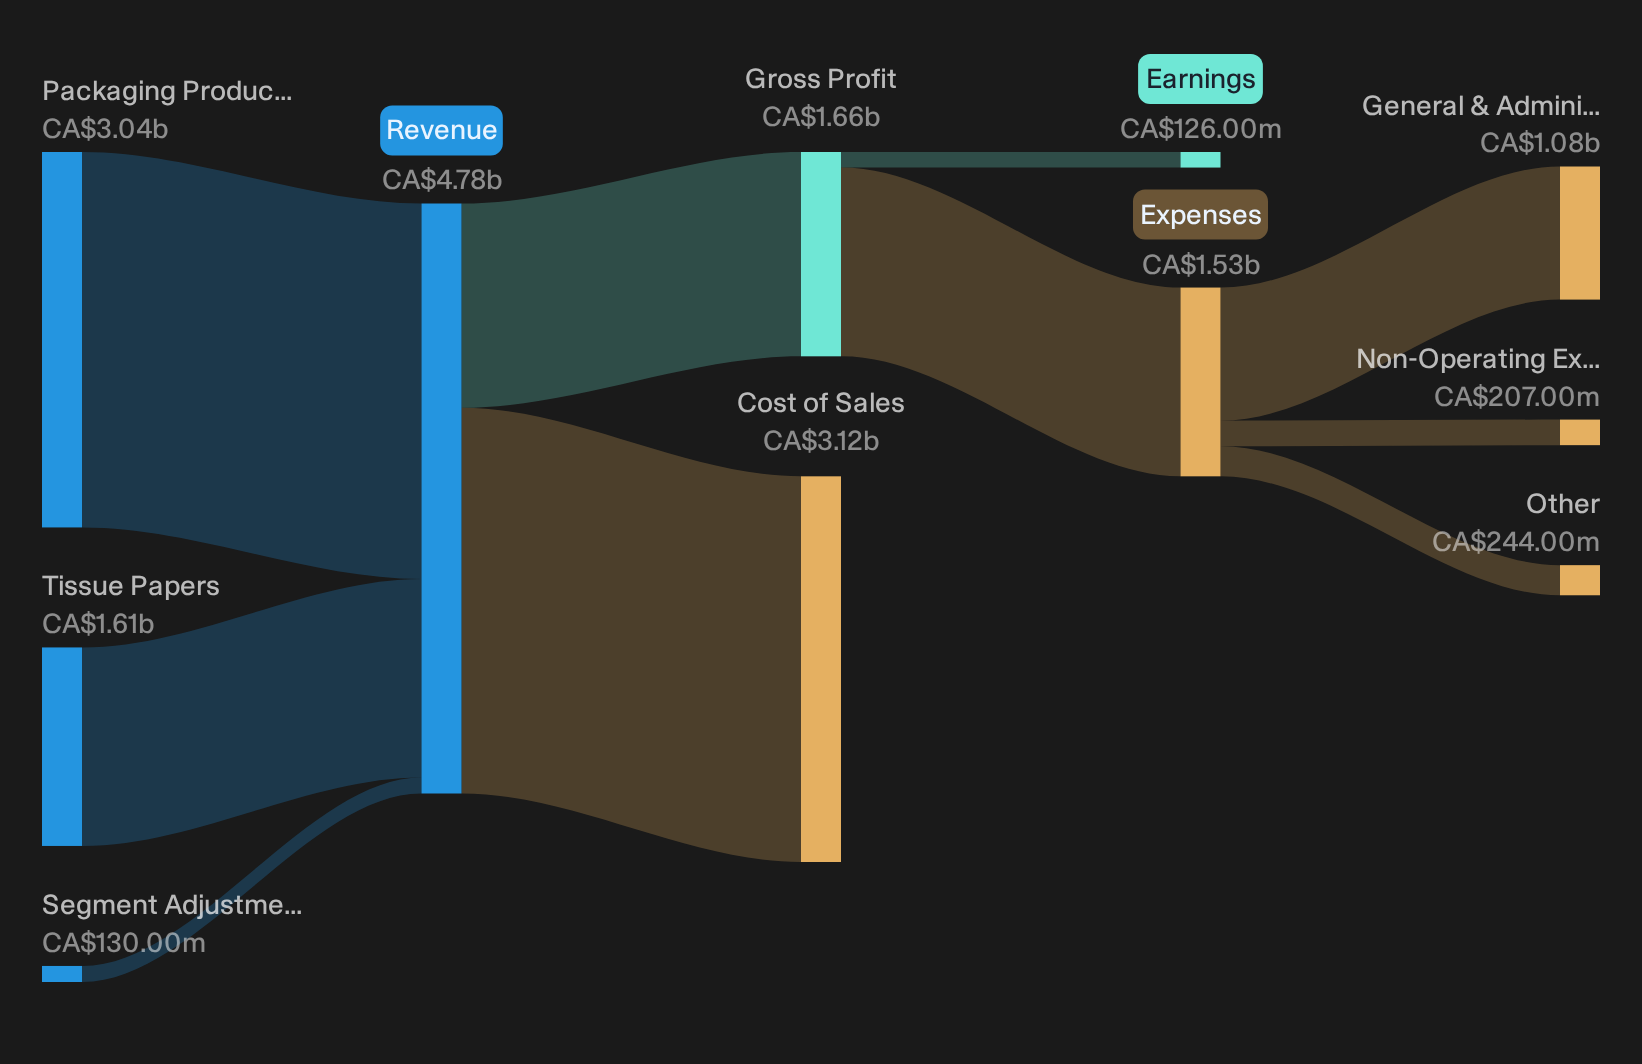
Overview: Cascades is a Canadian packaging and tissue producer, with high growth e-commerce and sustainable packaging solutions complementing its tissue and recycling operations.
Operations: Cascades generates about CA$3.0b from Packaging Products and CA$1.6b from Tissue Papers, with revenue split broadly between Canada and the United States.
Market Cap: CA$1.76b
Cascades gives this screener a clear real economy angle, since its e-commerce ready boxes and sustainable packaging speak directly to how goods actually move to customers.
"Continued ramp up at the Bear Island mill toward Greenpac level efficiencies, combined with targeted reductions in chemical and material usage, should lift Packaging segment productivity and support structurally higher EBITDA margins."
What really matters now is how one shifting cost and pricing equation ultimately shapes Cascades future profitability and growth runway.
That cost and pricing reset is exactly what the full narrative for Cascades lays out, separating short term noise from where Cascades earnings power could be accelerating next.
Seeking Fresh Alternatives Before They Fly
Markets move fast and the best breakout ideas rarely stay under the radar for long. Spot fresh momentum while it matters, before prices get away from you and act while the opportunity is still available.
- Target resilient compounders by scanning a curated 9 resilient stocks with low risk scores that aims to keep you invested when volatility spikes and weaker stories start dropping away.
- Focus on powerful secular themes with a 53 AI infrastructure stocks built around businesses supplying the hardware and backbone behind rapidly expanding AI demand.
- Stay attentive to commodity cycles with a hand picked 34 elite gold producer stocks designed to track producers that may benefit if bullion interest increases.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com