


EN
Nicolet Bankshares (NIC), What Is Behind The Fresh Attention?
Nicolet Bankshares earnings event and why it matters for the stock
Nicolet Bankshares (NIC) just posted a sharp step up in third quarter performance, with net interest income at US$142.23 million and net income at US$63.73 million, alongside a US$0.36 quarterly dividend announcement.
The latest results and dividend move come after a powerful run in Nicolet Bankshares, with a roughly 45% year-to-date share price return and a 46.1% total shareholder return over the past year. This builds on triple-digit total shareholder gains over three and five years and reflects how the market is reassessing the bank’s earnings power and risk profile.
Compare Nicolet Bankshares’ latest surge in earnings and dividend with other banks showing strong balance sheets and solid fundamentals using the curated list of solid balance sheet and fundamentals (24 results).
The recent jump in Nicolet Bankshares raises a simple tension. Are investors finally catching up to what the business is already delivering, or has sentiment sprinted ahead of the fundamentals that support the current price tag?
Price-to-earnings of 20.6x for Nicolet Bankshares: Is it justified?
Nicolet Bankshares closed at $174.74 while trading on a P/E of 20.6x, which is richer than both peers and the wider US Banks industry based on the data given.
The P/E ratio compares what investors pay for each dollar of current earnings. For a regional lender like Nicolet Bankshares that operates across Wisconsin, Michigan, and Minnesota, this measure is a quick way of seeing how much of a premium or discount the market places on its profit stream relative to other banks.
Here, that premium is clear. The stock changes hands at 20.6x earnings compared with a peer average of 11.3x and the same 11.3x figure for the broader US Banks industry. The estimated fair P/E of 15.2x is also well below where the market currently values the business, which signals that expectations built into the price are materially higher than the level the fair ratio suggests the market could move toward if sentiment cools.
Explore the SWS fair ratio for Nicolet Bankshares.
Result: Price-to-earnings of 20.6x (OVERVALUED)
Still, the story can change quickly if loan performance weakens or if Nicolet Bankshares faces tougher competition that pressures pricing and fee income.
Find out about the key risks to this Nicolet Bankshares narrative.
Another view on Nicolet Bankshares valuation
The P/E looks rich, yet the SWS DCF model points the other way. At $174.74, Nicolet Bankshares is described as trading below an estimated future cash flow value of $275.41. This frames the stock as undervalued on that measure. When one tool says expensive and another says cheap, which signal do you trust more?
Look into how the SWS DCF model arrives at its fair value.
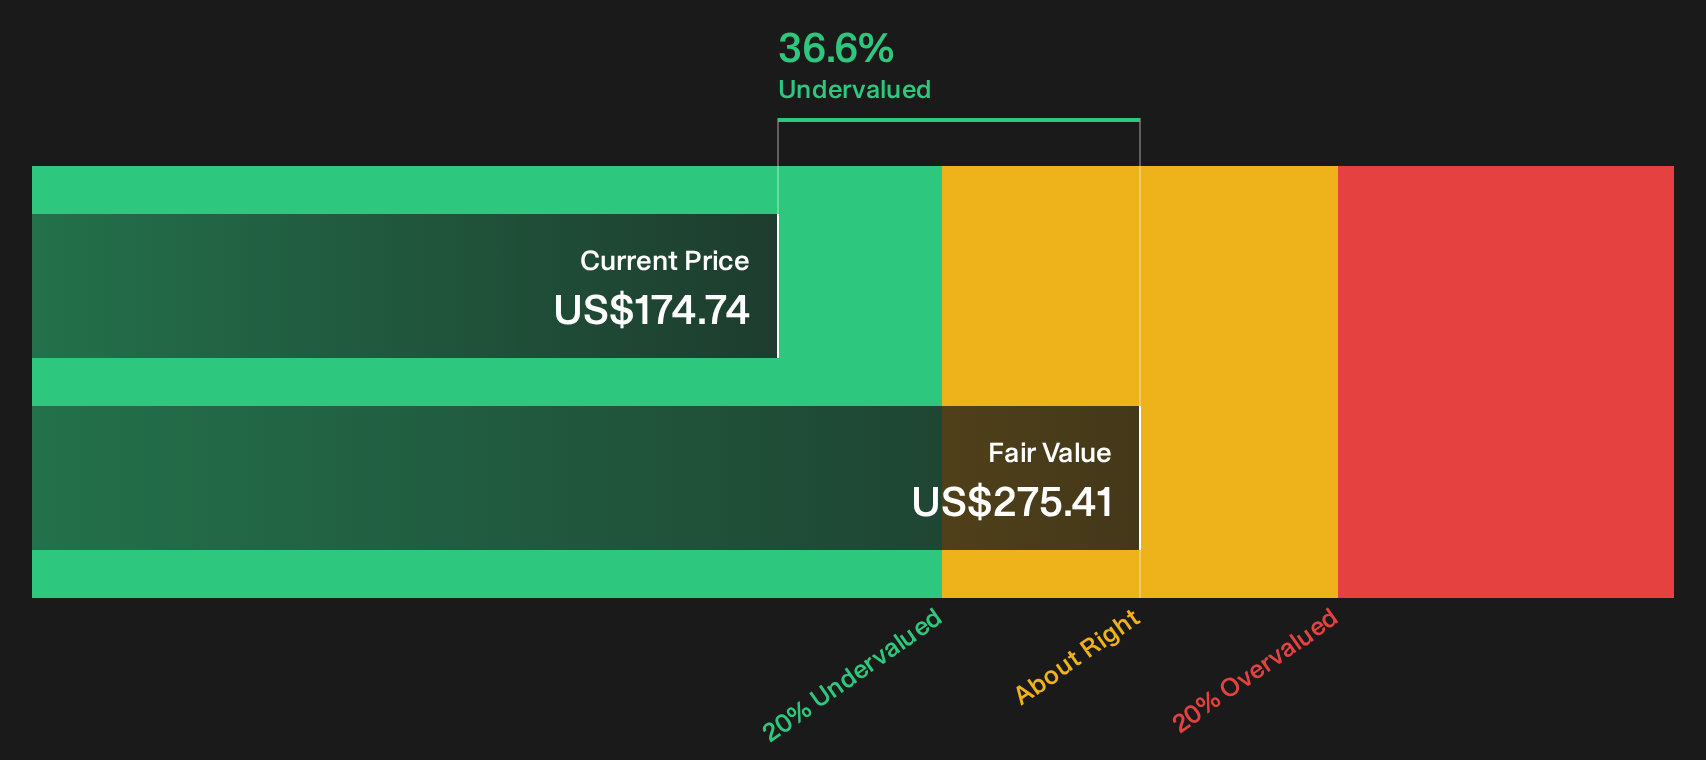
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Nicolet Bankshares for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 34 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the mixed signals around Nicolet Bankshares leave you unsure, act while the data is fresh and pressure test the story yourself with 3 key rewards and 2 important warning signs.
Looking for more Nicolet Bankshares sized ideas?
If Nicolet Bankshares has sharpened your focus, do not stop with one ticker. Use structured screeners to surface fresh ideas before the crowd gets there.
- Target resilience first and stress test your watchlist with a 29 resilient stocks with low risk scores that filters for businesses aiming to keep risk scores in check.
- Pursue value with discipline and scan a 34 high quality undervalued stocks that blends quality fundamentals with pricing that may still leave room on the table.
- Hunt for potential early movers by reviewing a 8 elite penny stocks with strong financials focused on smaller stocks that pair lower prices with stronger financial profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com