


EN
Calix (CALX), What Is Behind The Attention Now?
How Calix’s latest earnings put the stock in focus
Calix (CALX) just reported third quarter 2026 results that paired record revenue of about US$302 million with lower quarterly net income, a mix that gives you several moving pieces to weigh.
The headline number on sales came in alongside basic earnings per share of US$0.16 from continuing operations for the quarter and US$0.60 for the first nine months of 2026. This helps frame how the business is converting its broadband platform model into profit.
The mixed reaction to these results is showing up in the chart. Calix’s share price has fallen about 33% year to date and the 1 year total shareholder return is down roughly 46%. The past month delivered a modest 4% share price rebound that tempers, but does not reverse, the weaker 3 month share price performance.
Spot opportunities that are similar to Calix’s story by scanning a curated set of 53 AI infrastructure stocks tied to growing demand for broadband, cloud platforms, and AI-heavy communications workloads.So is Calix’s steep share price reset really tracking weaker earnings power, or has sentiment simply swung harder than the latest numbers justify as you weigh what the current valuation implies?
Most Popular Narrative: 42% Undervalued
The most followed narrative on Calix pegs fair value at about $62.33 per share, well above the latest close around $36.13. The gap between price and that thesis is wide enough that the underlying drivers matter.
The shift to a cloud and software centric model is now visible in record quarterly software and services revenue of $50 million and an 810 basis point sequential improvement in software and services gross margin. Together, these developments suggest Calix can keep lifting recurring revenue mix and earnings quality.
See why 20 investors see Calix as 42% undervalued.
Result: Fair Value of $62.33 (UNDERVALUED)
Still, this narrative can crack if elevated memory costs keep compressing appliance margins, or if ongoing shareholder investigations translate into heavier governance and legal overhangs.
Find out about the key risks to this Calix narrative.
Another View on Calix’s Valuation
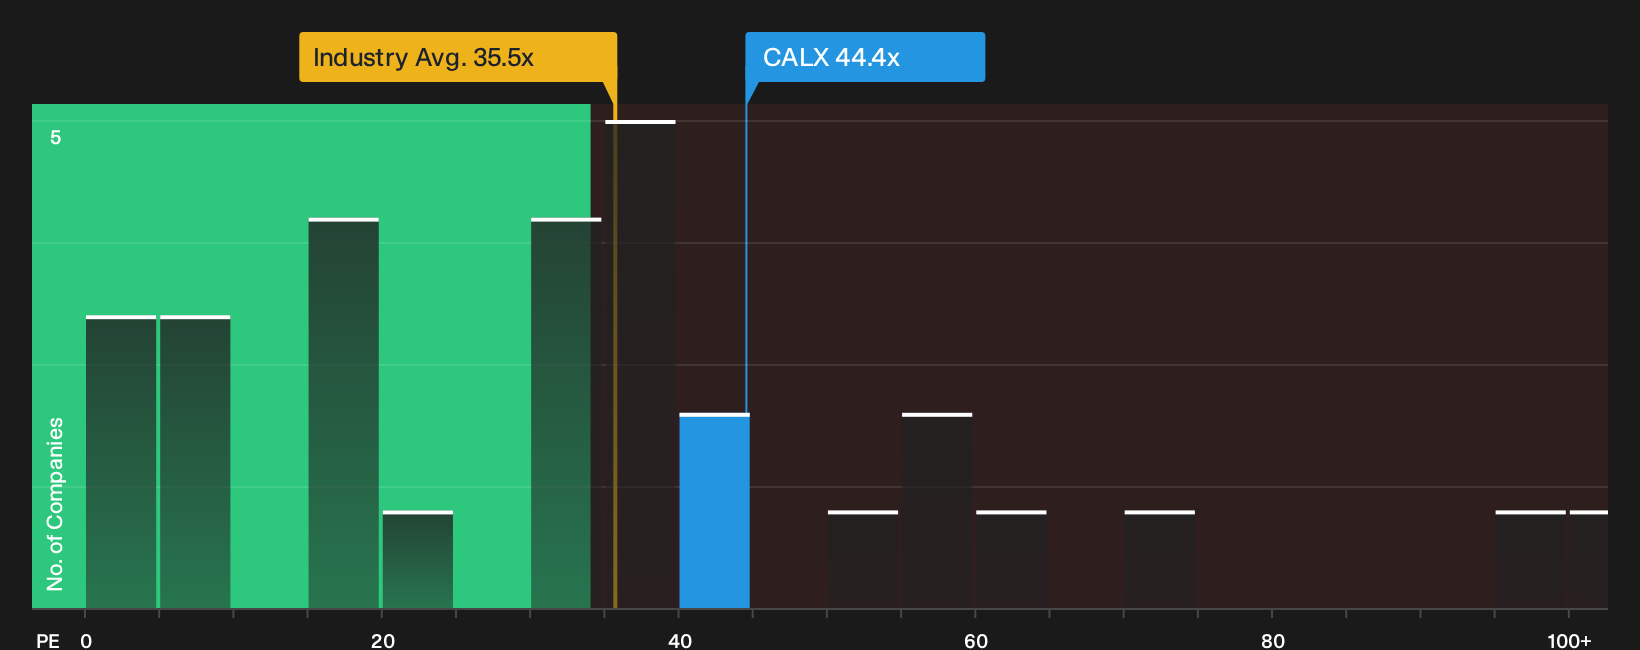
That 42% undervalued fair value narrative sits awkwardly beside how the market is actually pricing Calix today. The stock trades on a P/E of 44.4x compared with a fair ratio of 39.5x, the US Communications industry at 35.5x, and peer average at 37.6x. This signals richer pricing and adds valuation risk if expectations slip.
It leaves a simple question for you as an investor. Is this premium a reasonable price for the growth story? Or does it narrow the margin for error enough that you would want extra evidence before leaning on it as your main thesis?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of weak recent returns and an upbeat valuation story around Calix feels conflicted, treat it as a prompt to move quickly and review the underlying drivers yourself. Then weigh those signals against the 3 key rewards.
Looking for more Calix-sized investment ideas?
Do not stop with Calix. Broaden your watchlist now, because the strongest opportunities tend to emerge before most investors are even paying attention.
- Target resilient balance sheets that can handle shocks by screening for a list of solid balance sheet and fundamentals (24 results).
- Pursue potential mispricings by running a focused search across a 19 high quality undiscovered gems.
- Prioritize quality at a reasonable entry point through a curated set of 34 high quality undervalued stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com