


EN
Will Strong Quarterly Earnings Change Bank of Hawaii Stock Narrative
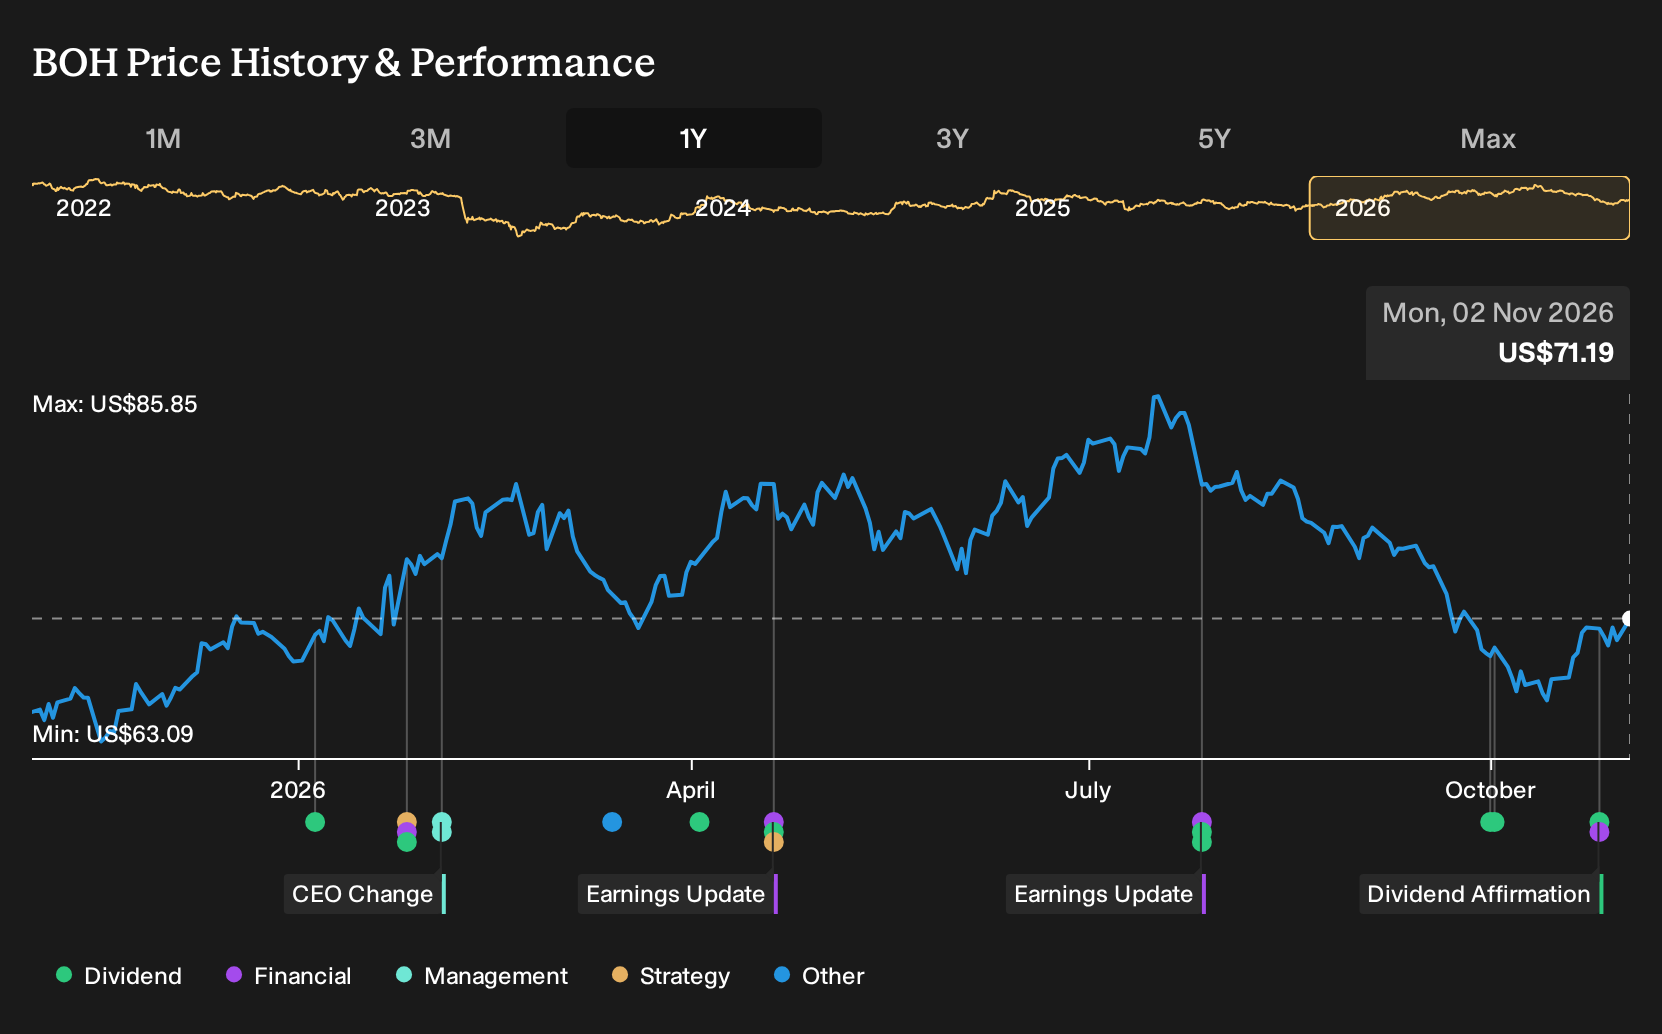
- Bank of Hawaii reported third quarter 2026 net interest income of US$156.05 million and net income of US$64.26 million, alongside a US$0.70 per share dividend and ongoing buybacks, with these events now in the past as of November 2, 2026.
- The combination of higher earnings, a maintained cash dividend, and the completion of a long running repurchase program highlights management’s focus on returning capital while running a relatively concentrated Hawaii centric banking model.
- We will look at how Bank of Hawaii's higher quarterly net income fits into the existing investment narrative around earnings quality.
Scan beyond Bank of Hawaii and compare its income and dividend profile with a curated 4 dividend fortresses that combine ongoing cash payouts with sizeable underlying businesses.
Bank of Hawaii Investment Narrative Recap
To own Bank of Hawaii, you need to be comfortable with a relatively concentrated, Hawaii-heavy lender that leans on relationship deposits, conservative credit and measured loan growth rather than rapid expansion. The latest quarter, with higher net interest income and net income than a year ago, supports that earnings quality story more than it changes it.
The near term swing factor remains how net interest margin and funding costs evolve as higher cost public deposits run off and CDs reprice. The main risk is still a shock to the local Hawaii economy that weakens asset quality, which would matter more than this single quarter’s earnings beat.
The most relevant update for that thesis is the third quarter 2026 earnings release. Net interest income of US$156.05 million and net income of US$64.26 million, both above the prior year period, feed directly into the view that Bank of Hawaii can support earnings while it works toward its net interest margin goals.
Basic EPS from continuing operations of US$1.50 for the quarter and US$4.30 for the first nine months shows how that income translates for shareholders, especially when combined with conservative credit and fee income efforts. For anyone focused on catalysts, execution on margin targets and maintaining asset quality still matter more than short term share price moves.
Bank of Hawaii Earnings Assumptions and Valuation Bridge
Analysts are effectively asking you to think about Bank of Hawaii through a longer lens, not just a single quarter. Their model ties together revenue growth, margin shifts and capital return into one earnings path and a future P/E multiple that they use to anchor a fair value estimate.
On the top line, the consensus view works off revenue growing at 8.2% a year over the next three years. That pace underpins a forecast that revenues reach US$950.8 million by 2029, paired with profit margins that move from 28.5% today to 31.6% in roughly three years. The mix of higher projected revenue and slightly wider margins is what underlies the long term earnings build in these forecasts.
On the bottom line, earnings today are put at US$214.4 million and analysts expect that figure to reach US$300.8 million by around 2029. That implies an earnings increase of about US$86 million over the period, helped by both the assumed margin lift and an expectation that the share count declines by about 0.84% a year for the next three years. In other words, the model assumes both a bigger profit pool and fewer shares splitting it.
Valuation work in the consensus report then layers a multiple on top of those earnings. The analysis points to a 2029 P/E of 12.8x on the US$300.8 million earnings forecast, versus a reported multiple of 12.7x today and an industry figure of 11.5x for US banks. The gap between those numbers does not look extreme, but it still assumes Bank of Hawaii trades at a modest premium to the broader group while delivering on its revenue and margin plans.
Bank of Hawaii's narrative projects US$950.8 million revenue and US$300.8 million earnings by 2029. That rests on 8.2% yearly revenue growth and an earnings increase of about US$86 million from US$214.4 million today.
Uncover why Bank of Hawaii's fair value indicates a 14% potential upside to its current price. This gap could narrow quickly if sentiment improves.
Exploring Other Perspectives
Fair value views on Bank of Hawaii from 2 private investors in the Simply Wall St Community range from about US$81 to over US$106,000 a share, which signals wildly different expectations. Set that against the recent earnings release, dividend affirmation and completed buyback, and you see how sharply opinions can diverge. Explore those alternative viewpoints before deciding how these risks and catalysts matter for you.
Explore another Bank of Hawaii fair value estimate, including one that suggests it could be worth just $81.17.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Bank of Hawaii research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Bank of Hawaii. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Bank of Hawaii's overall financial health at a glance.
Looking for More Investment Ideas Beyond Bank of Hawaii?
Once you have a view on Bank of Hawaii, it helps to see how it stacks up against other opportunities with different risk, income and quality profiles. The Simply Wall St Screener lets you quickly filter for companies that better match your own preferences on income, balance sheet strength or potential mispricing.
- If you are hunting for resilient businesses and want to keep risk in check, start with a 29 resilient stocks with low risk scores that already clear a tougher quality bar.
- For investors who prefer financial strength and cleaner balance sheets, scan through a list of solid balance sheet and fundamentals (24 results) and see which companies line up with your tolerance for debt and cash flow.
- If you are searching for opportunities the market might be underappreciating, broaden your watchlist with a 19 high quality undiscovered gems that combine solid fundamentals with less attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com