


EN
Did Third Quarter Earnings Just Shift HNI (HNI) Investment Narrative?
- HNI Corporation reported third quarter sales of US$1,592.9 million and net income of US$90 million, with basic and diluted EPS from continuing operations at US$1.23, compared with lower figures a year earlier.
- Across the first nine months, HNI generated US$4,412.9 million in sales while net income stayed close to last year. As a result, the stronger third quarter profit per share stands out against softer year to date EPS.
- Next, the focus turns to how this sharp third quarter sales and earnings performance might influence HNI Corporation's broader investment narrative.
Scan how HNI's earnings story compares with other established operators by reviewing a hand picked list of solid balance sheet and fundamentals (24 results) that may offer similar resilience through different cycles.
HNI Investment Narrative Recap
To own HNI, you need to believe the business can turn a strong office cycle and building products platform into steadier earnings, not just one strong quarter. The third quarter result, with higher sales and profit than a year earlier, helps the case that pricing, product refreshes and workplace demand are supporting the operating story in the short term.
The key near term catalyst is still execution on efficiency programs and integration benefits that can support margins while net income for the nine months remains close to last year. The biggest risk remains any renewed pressure on office furniture volumes or housing related activity, which could expose HNI's reliance on pricing and cost savings.
Recent commentary around expanded efficiency programs, including Steelcase related savings and broader network optimization with cumulative benefits expected to exceed US$150 million when mature, links directly to this earnings release. The latest quarter gives you a fresh reference point to judge whether cost actions are flowing through to profit rather than just offsetting earlier headwinds and one off items.
For HNI, that efficiency plan also ties into balance sheet goals, since management expects free cash flow to help reduce net debt and move leverage back toward pre acquisition levels over a period of roughly 18 to 24 months. Progress here matters for shareholders because current risks highlight that debt is not well covered by operating cash flow, and dividend coverage is tight, so consistent execution on savings and cash generation remains central to the catalyst story.
HNI's current analyst storyline points to revenues of US$7.3b and earnings of US$561.2 million by 2029, built on an assumed 18.3% yearly revenue growth rate and an earnings increase of roughly US$557 million from US$4.2 million today.
Uncover why HNI's fair value indicates a 43% potential upside to its current price, which could close sooner than many investors expect.
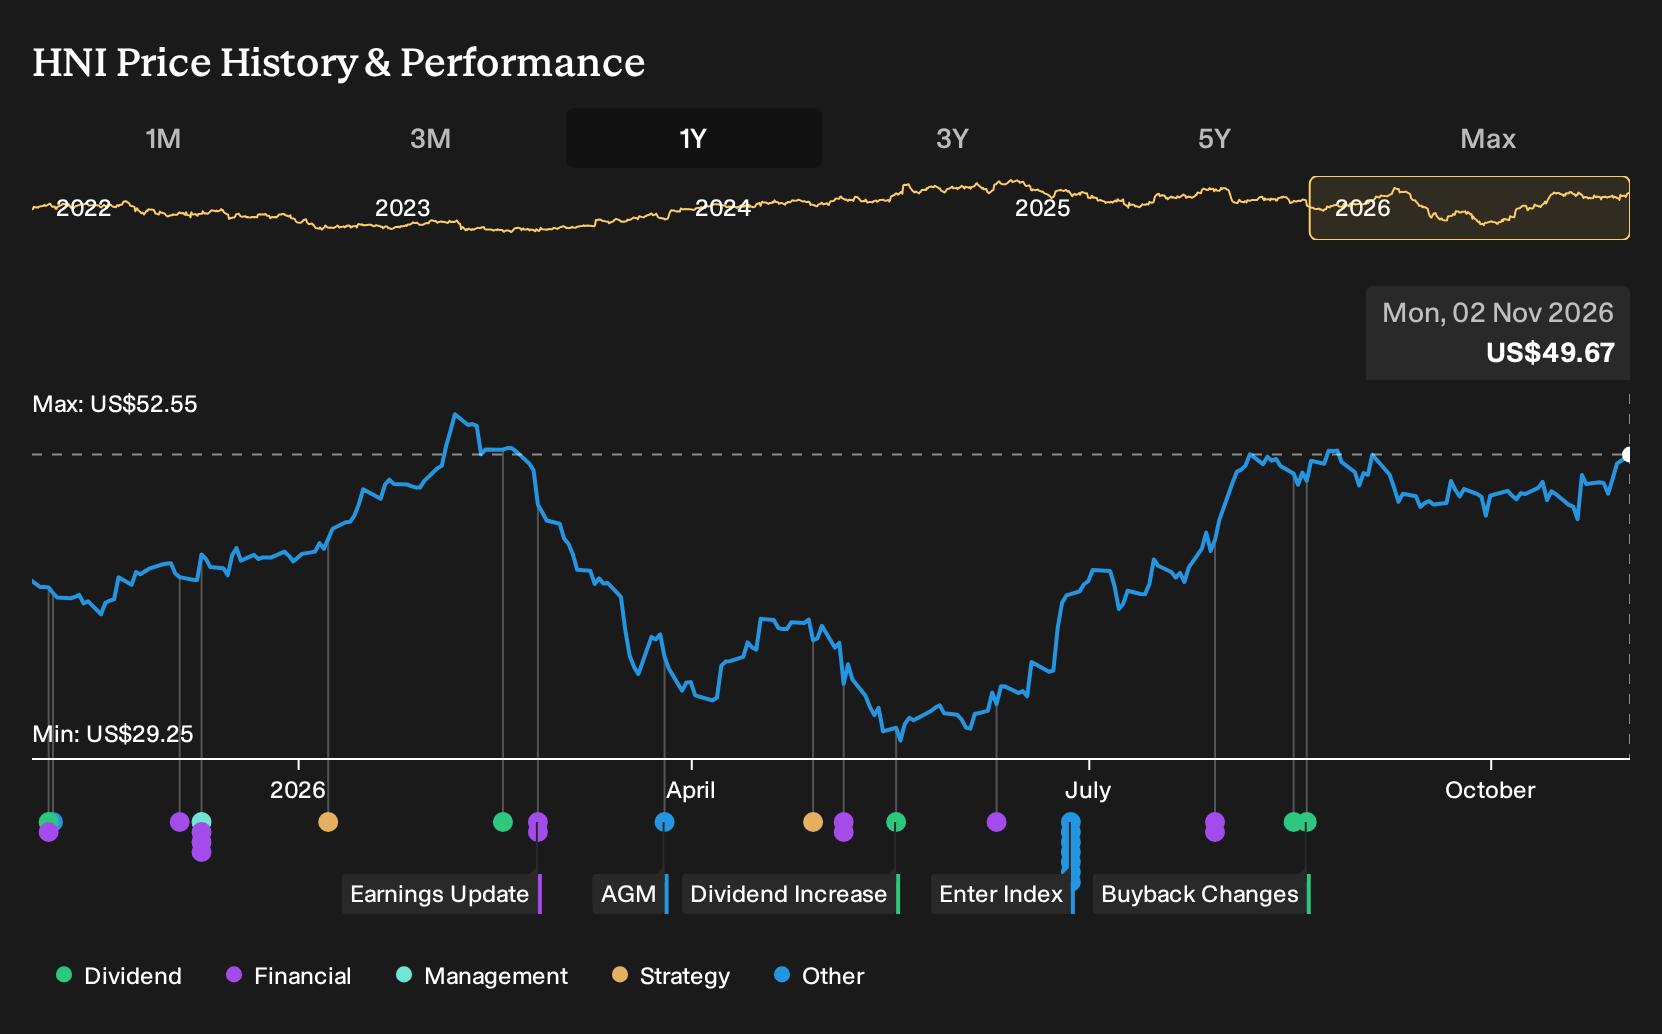
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community span roughly US$71 to almost US$193 per share, which already shows how far opinions on HNI Corporation can stretch. Before the latest earnings release, some members leaned on efficiency catalysts and balance sheet repair, while others focused on long term office and housing demand risks. Consider that spread a prompt to compare several viewpoints, not just one headline narrative.
Explore 2 other HNI fair value estimates, including one that suggests as much as 288% upside from the current price!
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your HNI research is our analysis highlighting 4 key rewards and 5 important warning signs that could impact your investment decision.
- See our latest analysis for HNI. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate HNI's overall financial health at a glance.
Looking For More Ideas Beyond HNI?
If HNI has sharpened your interest in resilient business models, broaden the watchlist by scanning other companies that line up with the kind of balance sheet strength, income potential, or value profile you want to focus on.
- For investors hunting for income resilience, review 4 dividend fortresses to help you zero in on higher yielding opportunities with staying power.
- If capital preservation sits higher on your priority list, filter for 29 resilient stocks with low risk scores that score well on financial robustness and stability metrics.
- When you want quality at a reasonable entry point, sort through 34 high quality undervalued stocks that combine solid fundamentals with more modest pricing.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com