


EN
Is Wall Street Bullish or Bearish on JPMorgan Chase Stock?
Valued at a market cap of $905.3 billion, JPMorgan Chase & Co. (JPM) is one of the world’s largest financial services firms. The New York-based company operates globally through Consumer & Community Banking, Commercial & Investment Bank, and Asset & Wealth Management segments, offering a full suite of banking, payments, lending, and investment solutions.
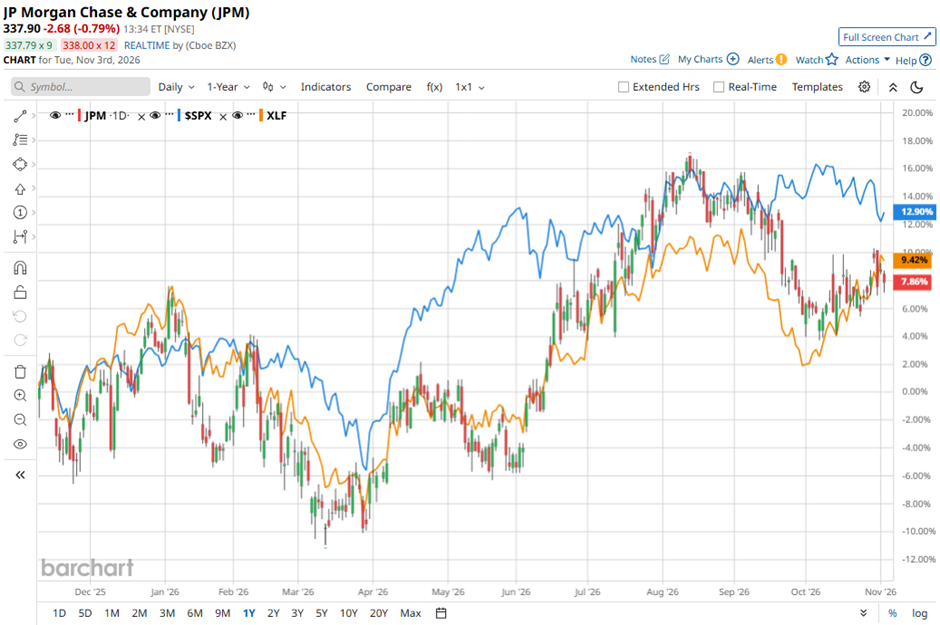
Shares of the New York-based company have lagged behind the broader market over the past 52 weeks. JPM stock has risen 8.9% over this time frame, while the broader S&P 500 Index ($SPX) has returned 10.6%. Moreover, shares of the company are up 4.6% on a YTD basis, compared to SPX’s 10.7% gain.
Focusing more closely, shares of JPMorgan Chase have underperformed the State Street Financial Select Sector SPDR ETF’s (XLF) 9.7% return over the past 52 weeks.
JPMorgan Chase shares fell marginally on Oct. 13 after the bank reported Q3 2026 EPS of $5.57, missing the analyst estimate and marking its first quarterly profit miss since Q4 2023, as weaker dealmaking and bond trading weighed on results. Investment banking fees declined 8% sequentially, and fixed-income trading revenue fell 4% year-over-year, reflecting slower IPO activity, market volatility, elevated interest rates and economic uncertainty, despite equity trading revenue surging 49% and overall markets revenue increasing 15%.
The shortfall was compounded by annual adjusted expense guidance rising to $108.6 billion, although net interest income excluding markets grew 6% to $24.7 billion, prompting the bank to raise its full-year net interest income forecast to $106.2 billion.
For the fiscal year ending in December 2026, analysts expect JPMorgan Chase’s EPS to grow 17.8% year-over-year to $23.95. The company’s earnings surprise history is mixed. It beat the consensus estimates in three of the last four quarters while missing on another occasion.
Among the 27 analysts covering the stock, the consensus rating is a “Moderate Buy.” That’s based on 12 “Strong Buy” ratings, three “Moderate Buy,” and 12 “Holds.”
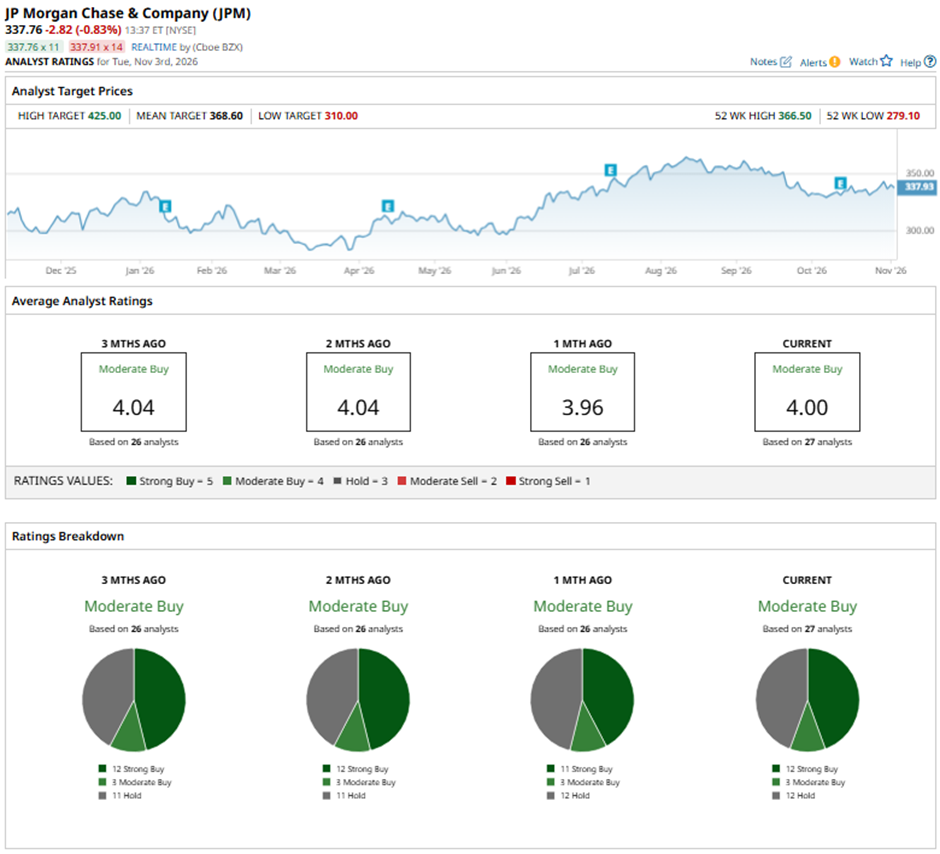
This configuration has remained unchanged over the past three months.
On Oct. 15, Wells Fargo analyst Mike Mayo assigned JPMorgan Chase a “Buy” rating with a $390 price target.
The mean price target of $368.60 represents a 9.1% premium to JPM’s current price levels. The Street-high price target of $425 suggests a 25.8% potential upside.
On the date of publication, Sohini Mondal did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.