


EN
Is WPP (LSE:WPP) Fairly Valued As Media Growth Returns And Client Wins Build?
Why WPP stock is back in focus
WPP (LSE:WPP) has moved back onto investor watchlists after its media arm returned to growth for the first time in two years, while retaining Coca-Cola globally and landing a global DoorDash partnership.
Recent wins have fed directly into the tape, with WPP’s share price delivering a 33.81% 90 day gain and a 20.89% year to date share price return. Total shareholder return over the past year is 55.79%, but remains down over three and five years.
The combination of media segment growth, the Coca-Cola renewal, a new DoorDash mandate and fresh senior hires has shifted attention back to the Elevate28 plan. It has also helped reframe sentiment around the advertising group’s risk and recovery profile at a £4.08 share price.
Scan how investors are pricing media turnarounds like WPP by comparing it with 5 high quality undiscovered gems that are already showing strong fundamentals but have yet to hit many radars.
Bulls see WPP’s recent Coca-Cola renewal, DoorDash win and media uptick as proof the reset is working. Bears point to a £4.08 share price after years of weak returns. Do the numbers justify this rerating?
Most Popular Narrative: 5% Overvalued
At a £4.08 share price against a narrative fair value of £3.89, WPP is framed as slightly expensive, with the thesis hanging on whether restructuring and AI heavy production actually convert into better earnings.
The Elevate28 programme, which targets £500 million of gross annualized cost savings with £100 million in 2026 and a £250 million run rate by year end 2026, together with early margin improvement in H1 2026, points to ongoing cost discipline that could help rebuild operating margin and support earnings as revenue pressure eases.
See why 44 investors see WPP as 5% overvalued.
Result: Fair Value of £3.89 (OVERVALUED)
Still, the narrative can break if organic net sales keep sliding and if Elevate28 cost savings fail to offset pressure in a shrinking production market.
Find out about the key risks to this WPP narrative.
Another View: What WPP’s P/S Gap Is Telling You
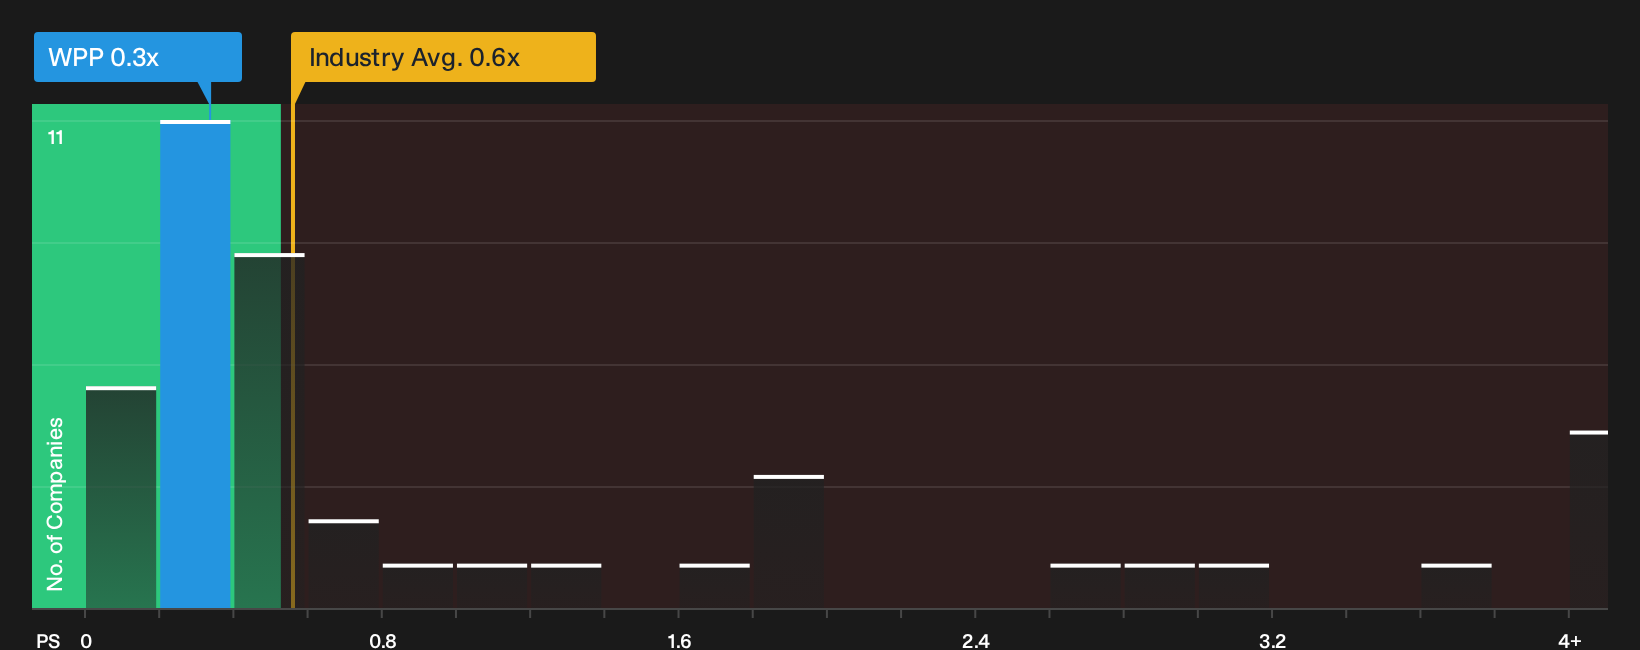
On the flip side of that fair value narrative, WPP looks inexpensive on its P/S ratio. It trades around 0.3x sales versus 0.6x for the UK Media industry, 1.4x peers and a fair ratio of 1x. That gap raises a simple question: Is it a safety cushion or a warning about future revenue pressure?
See what the numbers say about this price, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the data can be useful. Use the current mood around WPP as a starting point, then move fast and test the narrative against the hard numbers and the balance of 2 key rewards and 3 important warning signs.
Ready for more investment ideas beyond WPP?
Do not stop with one turnaround story. Broaden your watchlist with other opportunities that match your style, from potential bargains to resilience first portfolios.
- Hunt for quality at a discount by scanning a focused 13 high quality undervalued stocks that already clear strict fundamental checks.
- Build a portfolio that works harder for income by zeroing in on a curated set of 4 dividend fortresses with robust yields.
- Prioritise sleep at night capital by filtering for 5 resilient stocks with low risk scores that screen well on resilience and downside protection.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com