


EN
Is Franco-Nevada (TSX:FNV) Still Below Fair Value On Gold Price Optimism?
Why Franco-Nevada Is Back In Focus
Franco-Nevada (TSX:FNV) is back on investor watchlists after fresh commentary linked the stock to shifting gold price expectations and renewed interest in its royalty and streaming approach to precious metals exposure.
Recent trading has been choppy, with a 1-day share price return of 2.08% compared with a 30-day share price return that is down 5.81%. At the same time, the 1-year total shareholder return of 22.27% and 3-year total shareholder return of 93.93% point to momentum that has built over time as investors reassess Franco-Nevada’s gold linked royalty model and risk profile.
Scan beyond Franco-Nevada and line up other precious metals opportunities with the curated 34 elite gold producer stocks that share similar royalty, streaming, or gold price leverage stories.
Share price gains over the past year and a recent pullback leave Franco-Nevada in an interesting spot. Does that mix of momentum and volatility still tilt the risk reward in favour of new buyers, or has the easy upside already been priced in?
Most Popular Franco-Nevada Narrative: 19% Undervalued
Franco-Nevada last closed at CA$320.94, while the most followed narrative pegs fair value at CA$396.29. That story frames the stock as trading at a meaningful discount and leans heavily on what higher gold prices and portfolio breadth could mean for future cash flows.
Robust, record-level gold prices combined with ongoing global inflation concerns and monetary debasement are driving record royalty revenues and expanding margins for Franco-Nevada. This strengthens top-line revenue growth and leads to higher operating and net margins.
See why 52 investors see Franco-Nevada as 19% undervalued.
The narrative uses a 7.83% discount rate and assumes revenue growth of about 8.9% a year with profit margins around 66.3%, which is higher than recent levels. It also leans on the idea that a diversified royalty mix across precious metals, energy, and other mining assets can smooth earnings while still giving investors exposure to gold price moves.
To line up with that CA$396.29 view, you would need to be comfortable with earnings reaching about US$2.0b by 2029 and the market assigning a P/E multiple of roughly 34.7x to those profits. That is above the 15.2x level cited for the US Metals and Mining sector in the same narrative, so it assumes Franco-Nevada continues to justify a premium through higher margins and perceived resilience.
Supportive points in the story include high reported profit margins above 60%, earnings growth of 88.3% over the last year compared with a 6.6% per year run-rate over five years, and management and board tenure that is described as experienced. The royalty model, with CA$2,020.8m of revenue from precious metals out of CA$2,300.8m total, is framed as a key reason for that profitability profile.
Risks sit on the other side of the ledger. The same narrative highlights heavy dependence on gold prices, concentration in a few major assets such as Candelaria and Cobre Panama, competition pushing up royalty acquisition costs, and permitting or ESG hurdles that could slow contribution from development projects.
Analyst price targets in that framework cluster around the CA$396.29 consensus but span from CA$269.14 to CA$478.85. This leaves a wide band of possible outcomes even among specialists following Franco-Nevada closely. The internal fair value estimate has also moved modestly lower from CA$404.97 to CA$396.29 as growth and margin assumptions were trimmed, while the applied future earnings multiple nudged higher.
For investors weighing all of this, the key judgement call is whether Franco-Nevada’s premium valuation and royalty model, combined with gold exposure, are enough to justify paying close to 30x current earnings when the fair P/E from one model is 16.6x, and whether the narrative’s assumptions around growth, margins, and discount rate still feel reasonable today.
Result: Fair Value of CA$396.29 (UNDERVALUED)
Still, the whole Franco-Nevada story can look fragile if gold prices soften or if concentrated holdings like Cobre Panama and Candelaria experience new operational setbacks.
Find out about the key risks to this Franco-Nevada narrative.
Another Look At Franco-Nevada’s Valuation
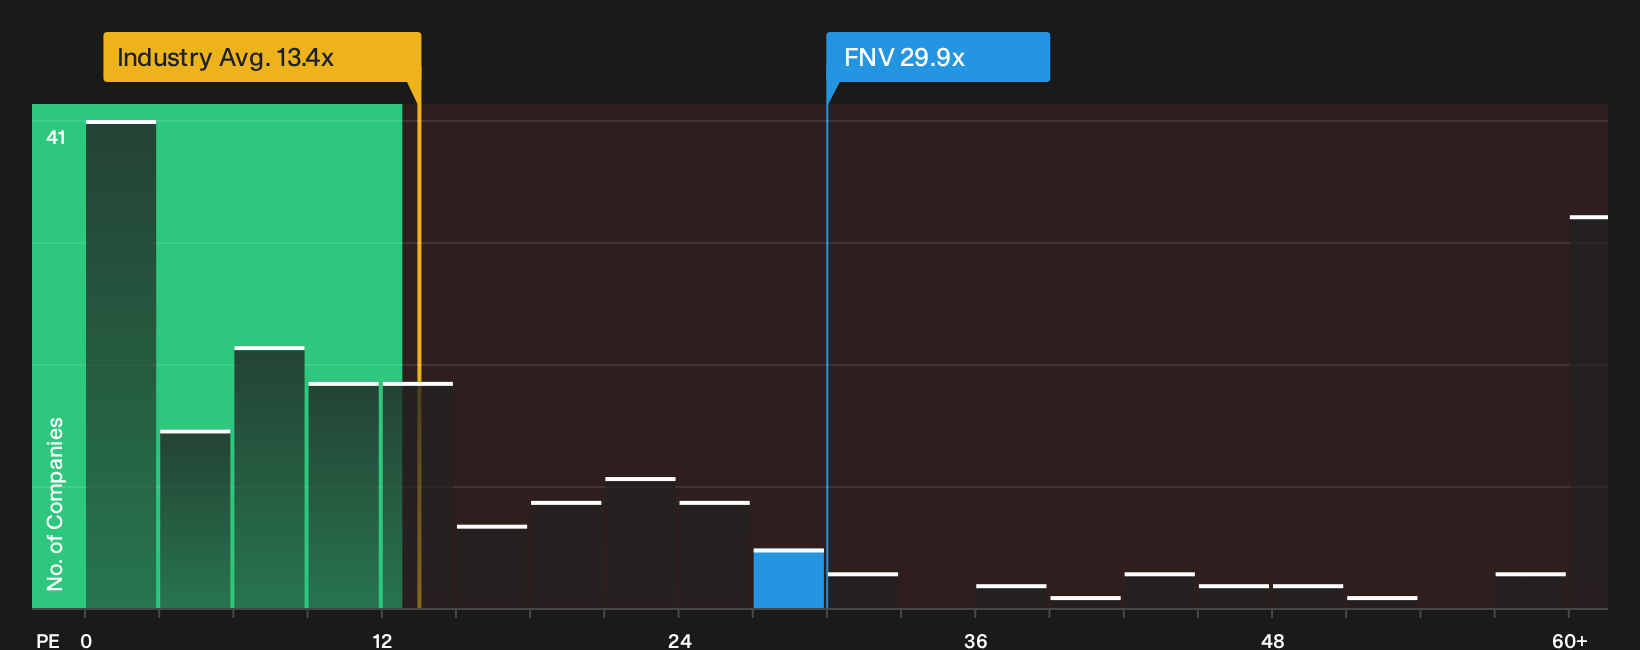
The story around Franco-Nevada shifts when the focus moves from analyst targets to the current P/E of 29.9x. That level is more than double the Canadian Metals and Mining industry at 13.4x and well above a fair ratio of 16.6x, which points to meaningful valuation risk if sentiment cools.
Investors weighing that premium may want to stress test what would need to go right for the market to keep paying such a rich multiple for Franco-Nevada, rather than drifting closer to the fair ratio over time, and whether that trade off still suits their portfolio.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Unconvinced by how bullish or cautious this all sounds for Franco-Nevada? Act promptly, review the underlying metrics yourself, and weigh those 3 key rewards
Looking For More Investment Ideas Beyond Franco-Nevada?
If Franco-Nevada has sharpened your focus, do not stop here. The right watchlist often starts with one stock and quickly widens into better options.
- Target potential mispricing by scanning a curated set of companies that screen as attractively valued using the 5 high quality undervalued stocks.
- Strengthen portfolio resilience by filtering for businesses with robust finances through the list of solid balance sheet and fundamentals (6 results).
- Get ahead of the crowd by reviewing a focused pool of under-followed opportunities using the 8 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com