


EN
Jabil (JBL) Stock Could Trade At A Discount To Fair Value
Jabil has logged a powerful multi year share price run, yet the recent pullback leaves a clear question hanging over the stock. Is the current price still supported by what the company earns today and what its earnings power may justify over time?
- Over the past 5 years Jabil has delivered a total return of 321.1%, which puts real weight on whether the present valuation can be grounded in its earnings profile.
- The business model leans on large scale manufacturing and engineering services. Any change in margins, capital intensity or contract mix can reshape how much of its revenue ultimately turns into earnings for shareholders.
- The analysts covering Jabil have run their own numbers. See what analysts think Jabil's shares could be worth.
The issue now is whether Jabil's current share price can be explained by its earnings when viewed through this earnings focused lens.
If you want to stress test this same earnings question beyond Jabil, compare it with a wider group of 34 high quality undervalued stocks.
Does Jabil Look Undervalued on Earnings?
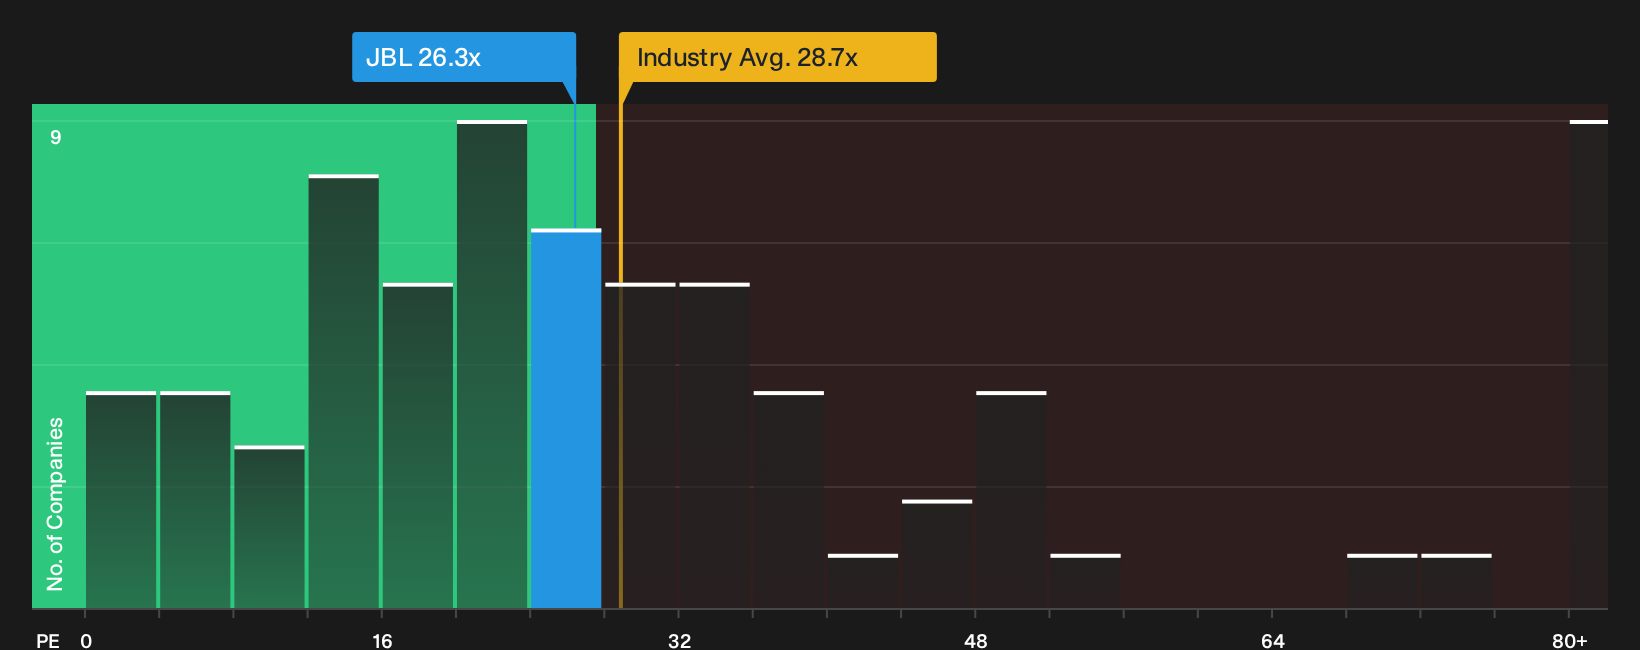
The P/E ratio suits Jabil because earnings remain the clearest anchor for a business that leans on contracts and utilisation rather than heavy branding. Jabil trades on a P/E of 26.3x, which is slightly above the peer group average of 25.2x yet below the wider electronic industry level of 28.7x. That leaves the multiple sitting in a band where the market is neither paying a bargain price nor assigning an extreme premium purely on this simple earnings yardstick.
The Fair Ratio, which reflects what investors might expect to pay given Jabil's margins, growth profile, scale and risks, sits above the current 26.3x level. That gap implies the stock screens undervalued on this tailored earnings framework, even though it does not look obviously cheap against sector references. For anyone weighing the recent share price pullback, the P/E suggests the market is applying a moderate earnings multiple to Jabil. Explore the numbers behind Jabil's P/E valuation.
The Jabil Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the valuation puzzle for Jabil leaves off by spelling out which paths for growth, margins and earnings would need to hold for the stock to be worth materially more or less than today's price. Each scenario links a fair value estimate to a specific storyline about Jabil's potential catalysts and key risks, so you can watch over time which version seems to be unfolding on the Community page.
One of the top community narratives on Jabil: 37% undervalued
The numbers on AI related revenue growth, segment guidance, free cash flow generation and large ongoing buybacks together imply that the current share price treats Jabil as undervalued...
Discover why this Narrative puts Jabil at 37% undervalued.
Jabil's price is only one question, the underlying checks are another
Share price and earnings only tell part of the story for Jabil, because the broader fundamental checks have also flagged issues that deserve your attention before you commit fresh capital. Take a closer look at 1 warning sign before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com