


EN
HUB24 (ASX:HUB) Following The Binance Hack Is This Regulated Crypto Play Already Priced In
The recent Binance hack has pushed many crypto users to reassess platform risk, drawing fresh attention to HUB24 (ASX:HUB) and its regulated access to crypto-linked investment and superannuation products.
HUB24 has been back on traders’ screens, with the share price at A$76.5 after a 4.84% 1 day share price return and a 17.67% 30 day share price return, even though the stock is still down 14.07% on a 90 day share price basis and the 1 year total shareholder return has declined 32.49%. Longer term holders have seen total shareholder returns of around 137% over three years and 175% over five years, which points to strong long run momentum that has recently cooled, then begun to rebuild after the Binance hack refocused attention on regulated crypto access platforms like HUB24.
Scan beyond HUB24 and the Binance fallout by reviewing 6 resilient stocks with low risk scores, which have been hand picked for investors who care about regulated platforms and balance sheet resilience.
HUB24 looks like a solid franchise with regulated exposure to a big superannuation pool, yet the share price has snapped back hard after recent weakness. Are you now paying up for that quality or not?
Most Popular Narrative: 32% Undervalued
On the numbers, HUB24's most followed narrative pegs fair value at A$113.04, well above the last close of A$76.50. This frames today’s Binance driven rebound against a longer term valuation gap based on superannuation flows and platform scale.
The updated FY28 funds under administration target range of A$186b to A$200b, lifted from an earlier A$160b to A$170b ambition, opens room for HUB24 to surprise on fee revenue and scale driven operating leverage if flows linked to long term superannuation and retirement demand track above the base case baked into that target.
See why 1 investors see HUB24 as 32% undervalued.
That narrative builds its A$113.04 fair value on a discount rate of 7.79%, forecast revenue growth of 16.72%, and an expected profit margin of 30.37%. Together, these inputs imply a richer earnings profile than HUB24’s current A$120.2m net income suggests. The same framework also leans on the idea that adviser adoption, AI assisted tools and higher margin tech solutions can support this earnings mix over time.
Result: Fair Value of A$113.04 (UNDERVALUED)
Still, the bullish HUB24 story runs into trouble if custody fee margins compress faster than expected, or if operating expenses grow ahead of platform revenue.
Find out about the key risks to this HUB24 narrative.
Another View: What HUB24’s P/E Is Telling You
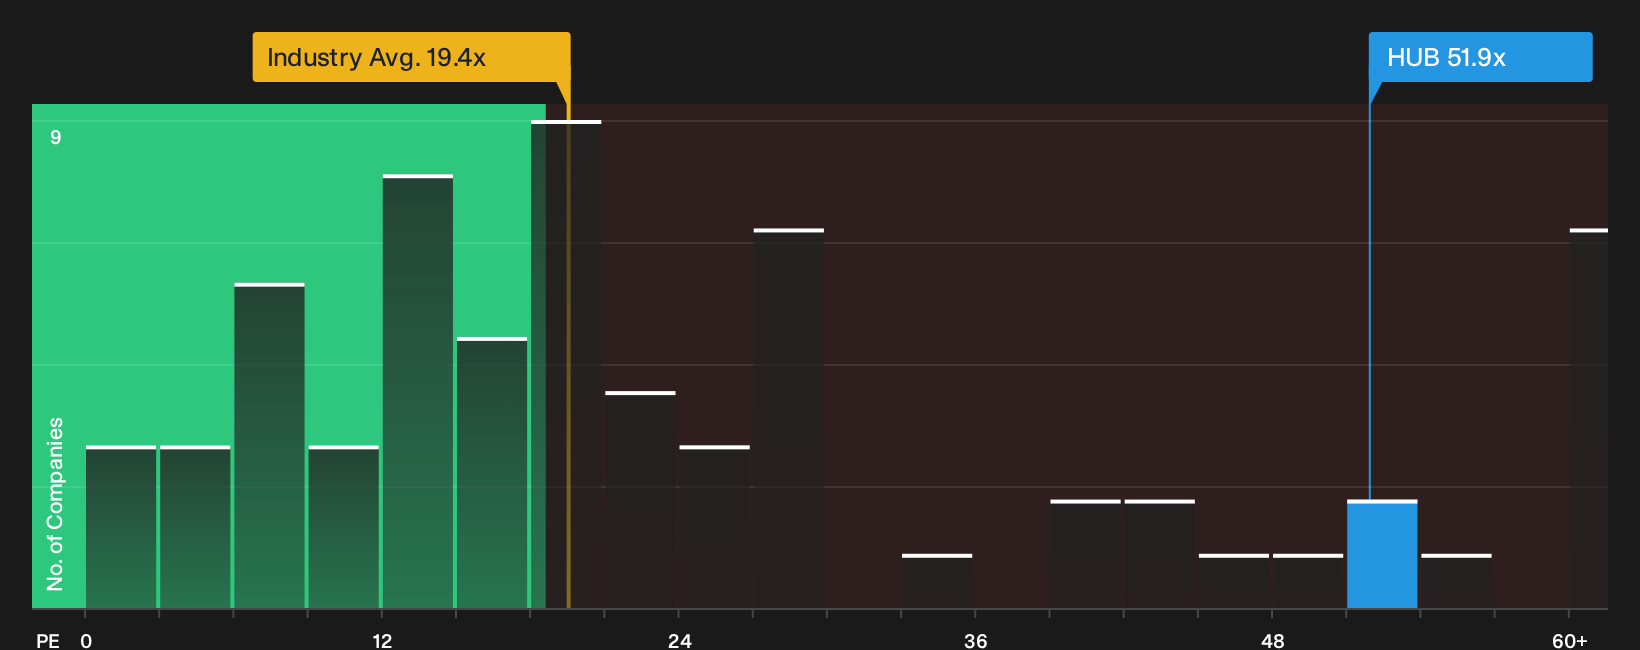
The bullish A$113.04 fair value leans on growth and margins, yet the P/E picture for HUB24 is much harsher. The stock trades on 51.9x earnings, compared with 19.4x for the Australian Capital Markets group and a fair ratio of 21.1x. That gap signals real valuation risk if sentiment cools.
For a closer look at how those earnings multiples stack up against industry peers and where the ratio could drift over time, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
If this mix of caution and optimism around HUB24 has you curious, check the numbers yourself now and come to an informed view using the 2 key rewards.
Looking for more investment ideas beyond HUB24?
If HUB24 has sharpened your thinking, do not stop here. The broad market still holds plenty of opportunities that may better match your goals and risk tolerance.
- Target higher income potential by scanning companies we classify as yield workhorses through the 5 dividend fortresses.
- Hunt for quality at a discount by reviewing the 3 high quality undervalued stocks that combine stronger fundamentals with more modest pricing.
- Prioritise resilience by checking the list of solid balance sheet and fundamentals (12 results) so you are not relying on hope when conditions get tougher.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com