


EN
How Investors May Respond To Royal Caribbean Stock After Raised Earnings Guidance
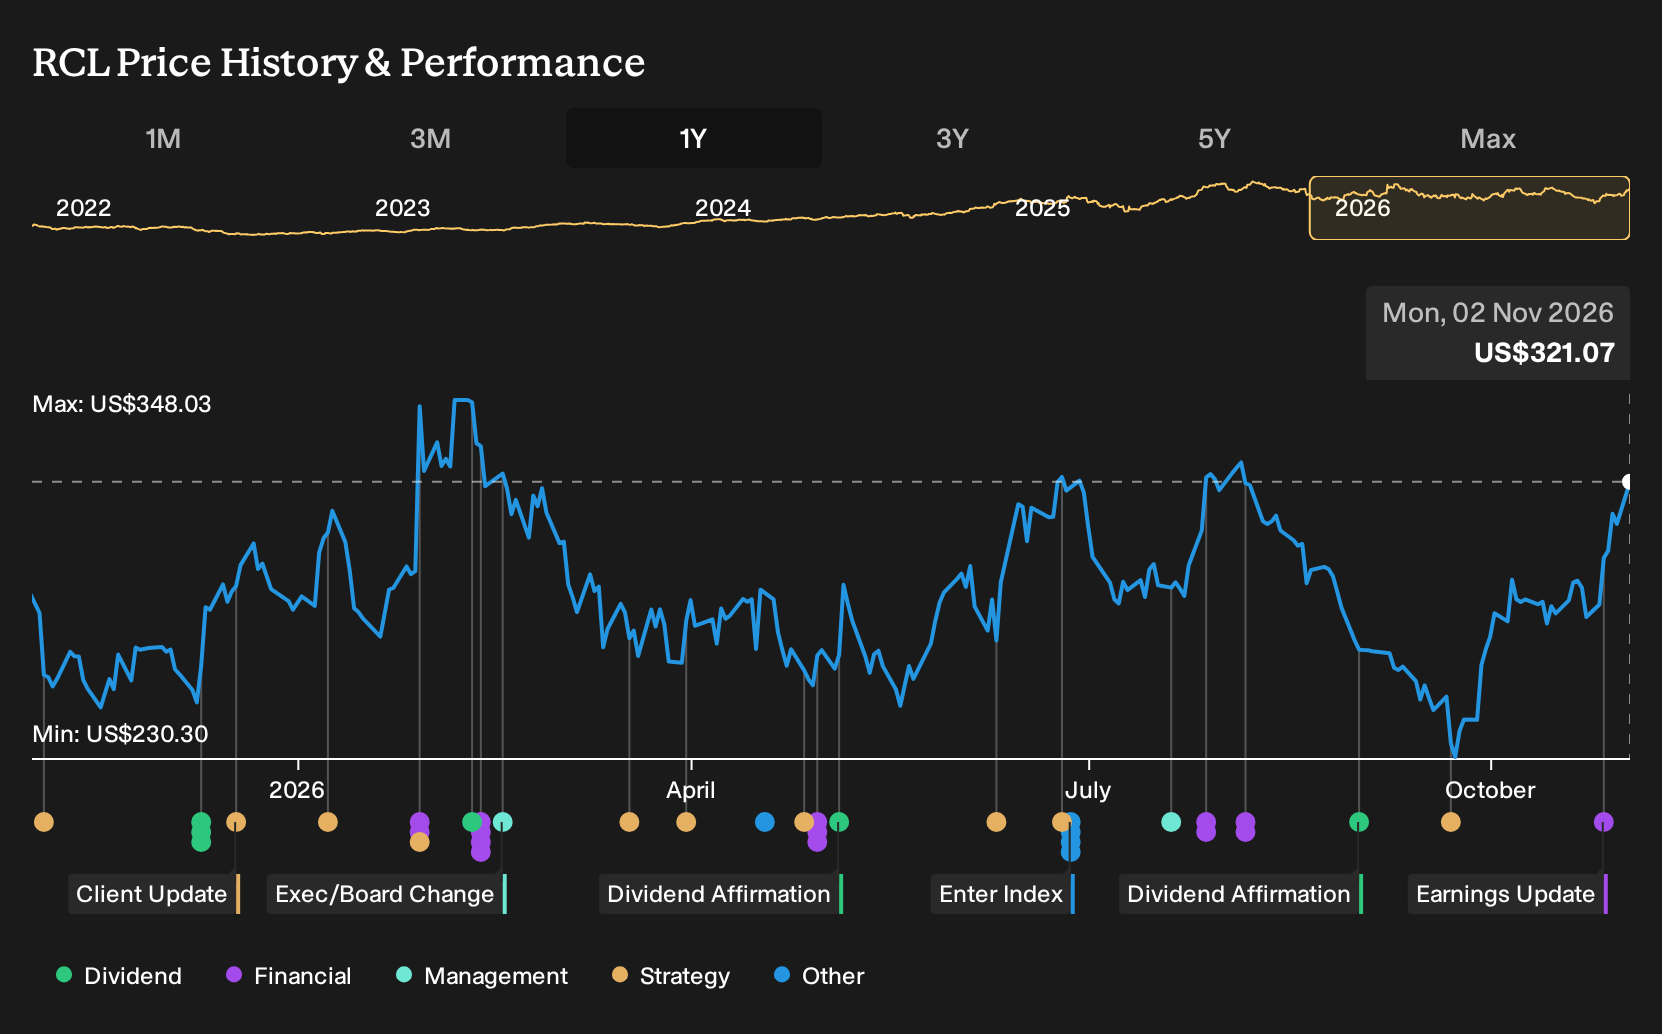
- Royal Caribbean Cruises reported third quarter 2026 basic EPS from continuing operations of US$6.46 and diluted EPS of US$6.45, with nine-month basic EPS of US$14.15. The company also raised its full year earnings guidance after results that were described as ahead of expectations.
- The business is leaning heavily on strong demand and higher onboard spending, while also committing US$3b of new debt for a 50% stake in Sandals and Beaches Resorts and expanding the Celebrity fleet with the future Celebrity Xcite to broaden its vacation platform.
- The focus now is on how Royal Caribbean Cruises' raised full year earnings guidance shapes the existing investment narrative and risk balance.
Royal Caribbean Cruises Investment Narrative Recap
To own Royal Caribbean Cruises you need to be comfortable with a story built on high guest spending, disciplined capacity additions and a still meaningful debt load. The latest quarter shows earnings power at the current booking and pricing backdrop, so the raised full year guidance ties the near term narrative closely to whether that demand and onboard spend can hold.
The biggest near term swing factor is yield resilience as new ships come in and fuel costs remain a live wildcard. Softer Mediterranean commentary and macro worries keep pricing risk on the table, although this quarter’s outperformance does not materially change the core risk profile investors were already debating.
The most relevant update here is the decision to take on about US$3b of new debt for a 50% stake in Sandals and Beaches Resorts. This shifts Royal Caribbean Cruises further toward an integrated vacation platform, which could matter for how consistently it can fill cabins and cross sell higher spending guests across land and sea products.
That step also raises execution risk and leverage at a time when fuel costs and booking trends are already key variables. For you as a shareholder, the question is whether the combined cruise and all inclusive resort footprint, alongside newbuilds and private destinations, can offset those financial and operational pressures and support the catalysts management is pointing to.
Royal Caribbean Cruises' narrative projects US$24.3b revenue and US$6.4b earnings by 2029. That path assumes 9.1% yearly revenue growth and about US$2b earnings increase from US$4.4b today.
Uncover how Royal Caribbean Cruises' fair value indicates a 9% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
The lowest Royal Caribbean Cruises analysts focus on yield pressure rather than new ships as the key swing factor. Before this earnings beat, they were modelling about US$23.6b in 2029 revenue and US$6.2b in earnings, with a lower 14.6x P/E. That more cautious story may shift when you compare it with today’s stronger headline results.
Explore 5 other Royal Caribbean Cruises fair value estimates, including one that suggests as much as 11% downside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Royal Caribbean Cruises research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Royal Caribbean Cruises. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Royal Caribbean Cruises' overall financial health at a glance.
Looking For More Investment Ideas Beyond Royal Caribbean Cruises?
If the Royal Caribbean Cruises story has you thinking about where else earnings surprises and resilient balance sheets might be hiding, the Simply Wall St Screener can help you quickly filter the wider market into a shortlist that matches your preferences.
- If you want potential mispricing with quality fundamentals, start with a curated set of 34 high quality undervalued stocks that already combine balance sheet strength with positive cash generation.
- For investors who put capital preservation first, narrow your search to a hand picked universe of 29 resilient stocks with low risk scores and see which ones match your risk tolerance.
- If reliable financial footing matters most, focus your research on a list of solid balance sheet and fundamentals (24 results) and see which businesses line up with your return goals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com