


EN
How Lower China Output Will Impact Magna International (TSX:MG) Investors
- Magna International updated its full year 2026 outlook, trimming expected sales to a range of US$41.2b to US$42.0b, citing lower anticipated vehicle production in China and an unfavorable program mix.
- The revised guidance highlights how Magna International’s exposure to Chinese auto volumes and product mix can directly pressure revenue planning and near term operating decisions.
- This development raises questions about how Magna International’s investment narrative may be influenced by the guidance cut tied to weaker Chinese auto production.
What Is Magna International's Investment Narrative?
To own Magna International, you need to be comfortable with a capital intensive auto supplier that lives or dies by execution on large, multi year programs. The latest quarter shows sales of US$10,059 million with net income of US$383 million, alongside slightly trimmed 2026 sales guidance tied to weaker China production and program mix. That guidance tweak keeps the near term story anchored in vehicle build schedules, pricing on content per vehicle, and how cleanly Magna can run its factories rather than any big shift in direction.
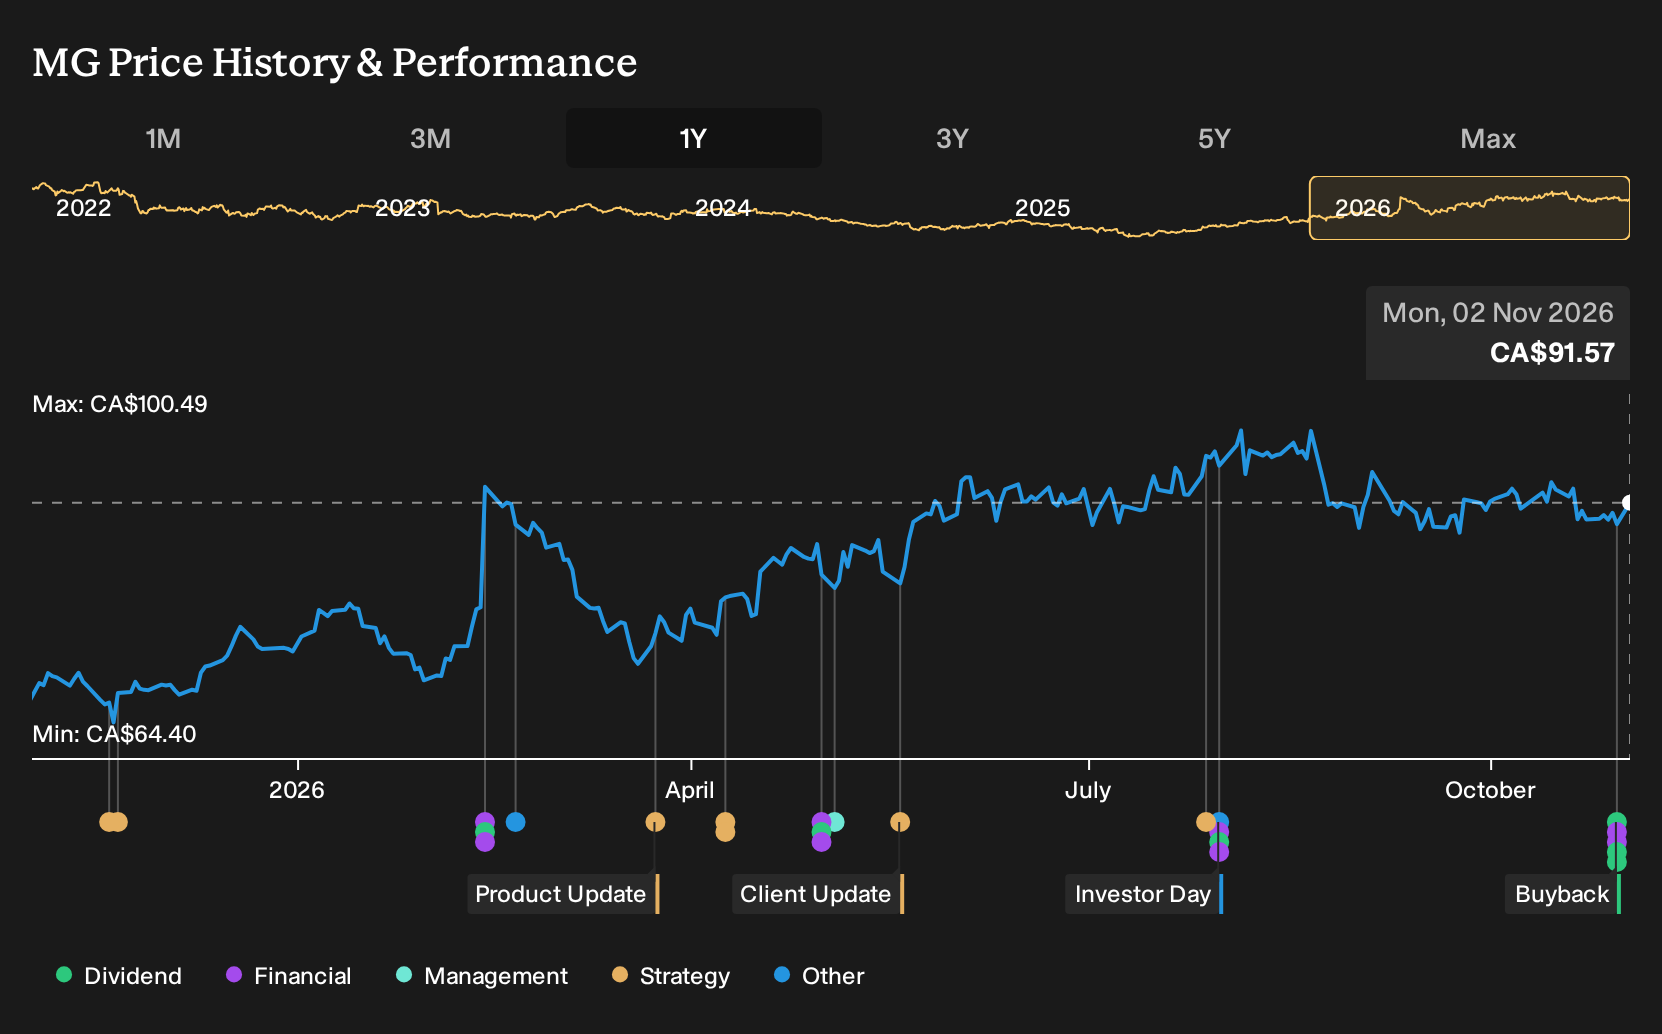
On top of that operational grind, capital allocation is now a visible part of the thesis. Management has completed a US$1,485 million buyback since late 2025 and authorized a new plan for up to 25,800,000 shares, while also affirming a US$0.495 quarterly dividend. Those moves suggest confidence, but they also sit against a high P/E versus peers, meaningful debt levels, and earnings that have been shaped by one off items, so you want to be sure you are comfortable with...
There's only one way to know the right time to buy, sell or hold Magna International. Head to Simply Wall St's company report for the latest analysis of Magna International's Fair Value.
Exploring Other Perspectives
Risk focused analysts see China as the pressure point for Magna International. Before this guidance cut, the most optimistic group still only penciled in revenue of about US$44.8b and earnings of roughly US$2.6b by 2029. That can be read as a stretch. These forecasts may shift, so explore a range of views before deciding.
Explore 3 other Magna International fair value estimates, including one that suggests potential upside of as much as 203% from the current price.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Magna International research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Magna International. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Magna International's overall financial health at a glance.
Looking For More Ideas Beyond Magna International?
Once you have formed a view on Magna International, it can help to broaden your watchlist with a few contrasting opportunities that fit different risk and income profiles. The Simply Wall St Screener offers several focused sets of companies that you can review side by side and pressure test against your own criteria.
- If you want potential value combined with quality fundamentals, start with a 5 high quality undervalued stocks that already clear basic financial strength checks.
- For investors who care most about income resilience, review a hand picked group of yields in the 3 dividend fortresses that may suit a more cash flow focused approach.
- When capital preservation matters more than anything else, filter for stability first with a 9 resilient stocks with low risk scores and only then layer in your return targets.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com