


EN
Did Earnings Beat Just Shift Chevron (CVX) Investment Narrative?
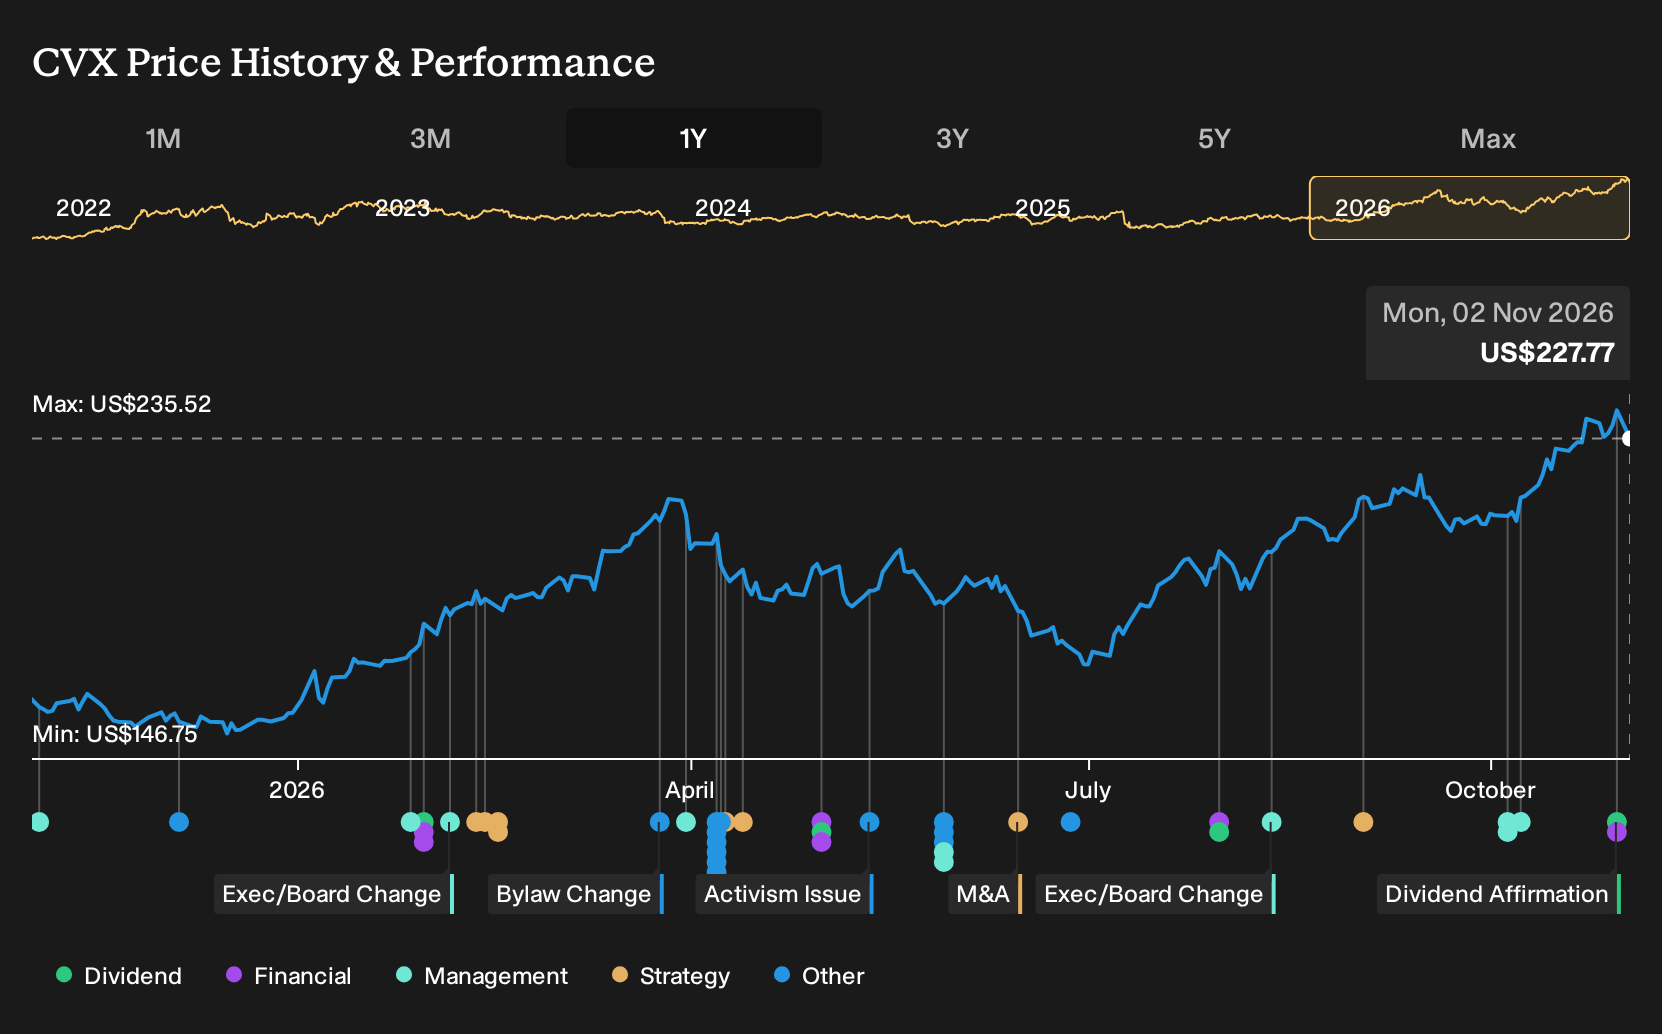
- Chevron reported strong third quarter 2026 results, with revenue of US$67.8b, net income of US$9.9b and record refining profit of US$4.93b, supported by high refinery utilization and global diesel shortages.
- The board backed this cash generation with a US$1.78 quarterly dividend declaration and a plan to invest US$7b in Venezuelan joint ventures. ETFs and dividend funds actively adjusted their Chevron exposure around the news.
- We will look at how Chevron's investment narrative intersects with record refining profits to reshape the risk and cash flow profile.
Compare Chevron's surge in cash generation and ETF flow with other large energy plays by scanning a hand picked set of 43 power grid technology and infrastructure stocks tied to the same fuel and infrastructure story.
Chevron Investment Narrative Recap
To own Chevron here, you need to be comfortable with a business that leans on large, long life oil and gas projects, a disciplined dividend and heavy exposure to refining cycles. The short term swing factor is whether record refining profitability and Venezuela production plans can offset any soft spots in upstream volumes and future demand questions for hydrocarbons.
The biggest risk right now is simple. If energy demand shifts faster than Chevron reshapes its project mix, the firm could feel pressure on revenue and margins even with strong current cash generation. Recent Q3 strength and ETF flows update that debate but do not fundamentally change it.
The governance announcement around Siva Barnwell Adams becoming corporate secretary and chief governance officer matters more than it might seem at first glance. Chevron is committing billions to Venezuela, expanding exploration across several regions and integrating prior deals, so board level oversight and legal discipline sit directly on the critical execution path.
Barnwell Adams brings long experience inside Chevron across major transactions, joint ventures and corporate matters, while Mary Francis will remain as senior advisor into 2027. For you as a shareholder, that combination points to continuity around how large projects are structured, how governance risk is managed and how the board evaluates future catalysts and downside scenarios.
What The Current Chevron Forecasts Actually Assume
Cronk through the analyst model and Chevron suddenly looks less like a pure refinery story and more like a long run earnings puzzle. Consensus expects revenue to edge lower by 1.2% per year over the next three years, even as profit margins are projected to shift from 9.8% today to 12.6% in the same window.
On the earnings line, forecasts point to net income of US$25.5b by 2029 compared with US$20.6b today. That is an increase of about US$4.9b in profit, with earnings per share expected to reach US$13.83. Behind those headline numbers sits a wide spread of views, from US$18.7b at the cautious end of the range to US$33.1b at the most optimistic.
Chevron's narrative projects US$202.0b revenue and US$25.5b earnings by 2029. This aligns with expectations for revenue to decline by 1.2% per year and implies an earnings increase of about US$4.9b from US$20.6b today.
Analysts then link those outcomes to a P/E of 20.8x on the 2029 earnings, compared with 21.7x today and above the 12.6x level quoted for the broader US oil and gas group. That setup assumes investors keep paying a premium multiple for Chevron, even though the top line is modeled to contract modestly while profitability does more of the heavy lifting.
Uncover why Chevron's fair value appears to be generally consistent with its current price.
Exploring Other Perspectives
The Simply Wall St Community contributes three Chevron fair value views, stretching from US$232.50 up to about US$369.69, so some members see limited upside while others model far richer outcomes. When you set that next to the risks around long term hydrocarbon demand and premium P/E assumptions, it becomes clear why opinions diverge. Use those contrasting takes as a prompt to review several alternative viewpoints rather than anchoring on any single number.
Explore 2 other Chevron fair value estimates, including one that suggests as much as 62% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Chevron research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Chevron. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Chevron's overall financial health at a glance.
Looking for more Chevron-like investment ideas?
If this Chevron breakdown helped clarify your thinking, you can widen the lens and scan other companies with very different risk and return profiles using the Simply Wall St Screener.
- For investors who want financial resilience front and center, start with a list of solid balance sheet and fundamentals (24 results) that can handle tougher conditions without stretching the balance sheet.
- If your priority is cushioning volatility with income, focus on businesses in the 4 dividend fortresses that combine sizeable yields with the fundamentals to keep paying them.
- When you are hunting for mispriced opportunities backed by strong fundamentals, cast a wider net across a curated 19 high quality undiscovered gems that the broader market may not be paying close attention to yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com