


EN
Krystal Biotech (KRYS) Stock Looks Above Fair Value On Current Earnings
Krystal Biotech has delivered a very large 5 year share price gain, yet the stock recently pulled back and now trades near US$295.9, which raises a simple question for you as an investor. Do the company’s current earnings make that kind of long term return look supported at today’s valuation, or has enthusiasm moved ahead of the underlying profit base?
- The stock has climbed roughly 7x over the past 5 years. As a result, even small changes in the earnings outlook can have an outsized effect on whether this level proves sensible.
- A new US$400m share repurchase program and expectations around products like VYJUVEK and KB407 can influence how much of each dollar of earnings the market is prepared to pay for and how predictable those profits appear.
- Your read on Krystal Biotech is one view; the desks covering it have another. See what analysts think Krystal Biotech's shares could be worth.
The issue now is whether Krystal Biotech’s current share price is adequately supported by the earnings that investors are paying for today.
If you want to test the same earnings question you are asking of Krystal Biotech across a wider set of companies, take a look at 34 high quality undervalued stocks.
Is Krystal Biotech Getting Expensive on Earnings?
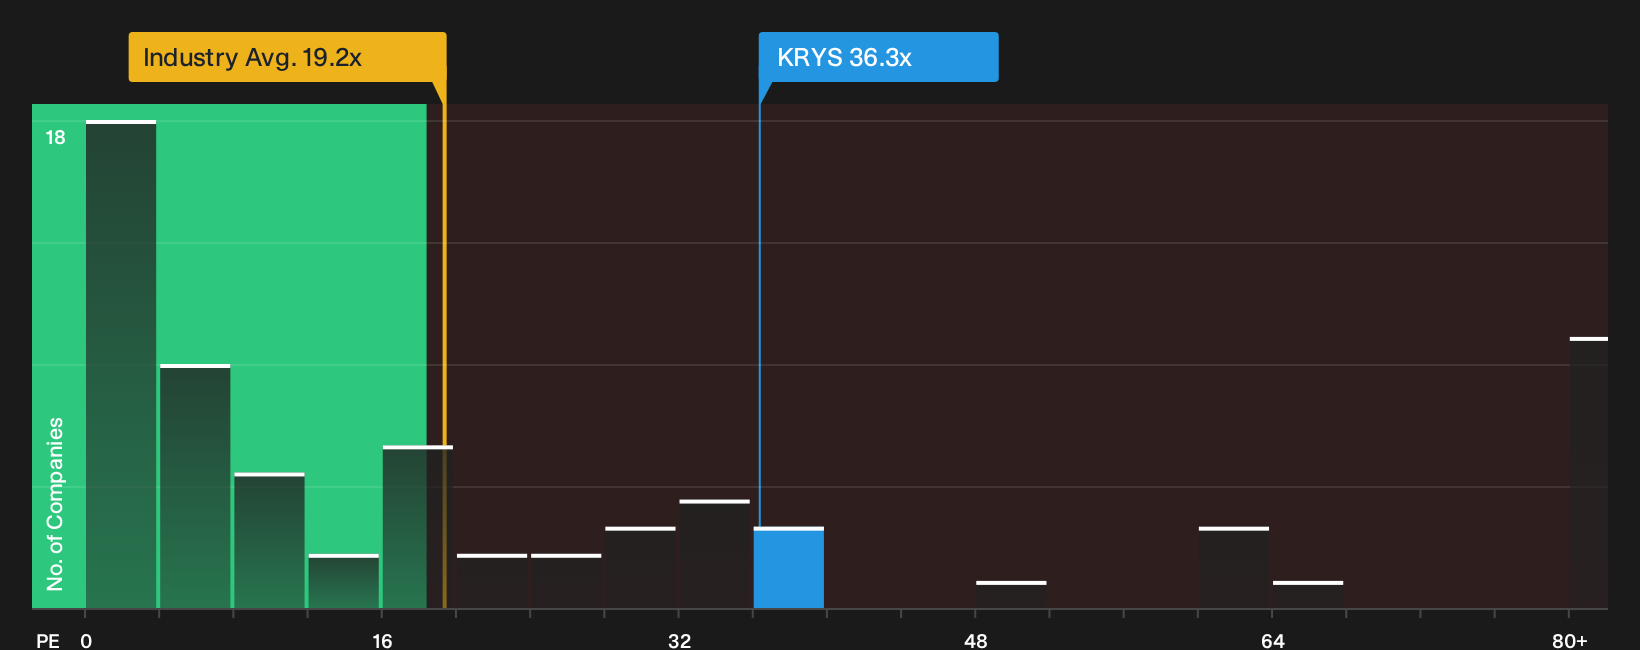
P/E is the cleanest way to compare what you are paying for Krystal Biotech today with the profits it is generating. On this lens, the stock trades around 36.3x earnings, which is above the broader biotech sector on roughly 19.2x and below the peer group closer to 60.5x. That range indicates the market already prices Krystal Biotech as a higher quality or more established operator than the average biotech, but not at the most aggressive end of its direct peers.
The model based fair P/E, which blends factors like growth prospects, margins, business risk and size, points to a lower level than where Krystal Biotech changes hands, so the shares screen as overvalued on this metric. Because management has announced a US$400m share repurchase program alongside recent VYJUVEK revenue updates, the current valuation also reflects expectations that this earnings base will remain robust enough to support both reinvestment and buybacks. Explore the numbers behind Krystal Biotech's P/E valuation.
The Krystal Biotech Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Krystal Biotech pick up where this valuation puzzle leaves off and explain which paths for growth, margins and earnings would need to occur for the share price to appear meaningfully higher or lower than it is today. Each scenario links a fair value estimate to a specific storyline about Krystal Biotech's potential catalysts and key risks, allowing you to track over time which version of events is closest to reality.
Community views on Krystal Biotech split between those who see more upside left and those who think expectations already bake in a lot.
Bull case: 25% undervalued
"Advancement of Krystal Biotech toward a multiproduct genetic medicines company through late stage programs such as KB803, KB801, KB407, KB111, KB707 and KB408, supported by HSV 1 platform technology designations, could broaden the revenue base beyond Vyjuvek and spread fixed costs across multiple products..."
Discover why this Narrative puts Krystal Biotech at 25% undervalued.
Bear case: roughly fairly valued
"HSV 1 platform expansion into ophthalmology, respiratory and oncology programs, including registrational and near registrational studies across KB803, KB801, KB407, KB111 and KB707, demands sustained R&D and commercial investment..."
Explore why this Narrative puts Krystal Biotech at roughly fairly valued.
Before acting on Krystal Biotech's valuation, look at who is steering it
Price, profits and products only tell part of the story, because the people directing Krystal Biotech and the way their pay is structured can pull decisions in very different directions. See who runs Krystal Biotech and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com