


EN
Will Strong Q3 Earnings Change Teck Resources Stock Narrative
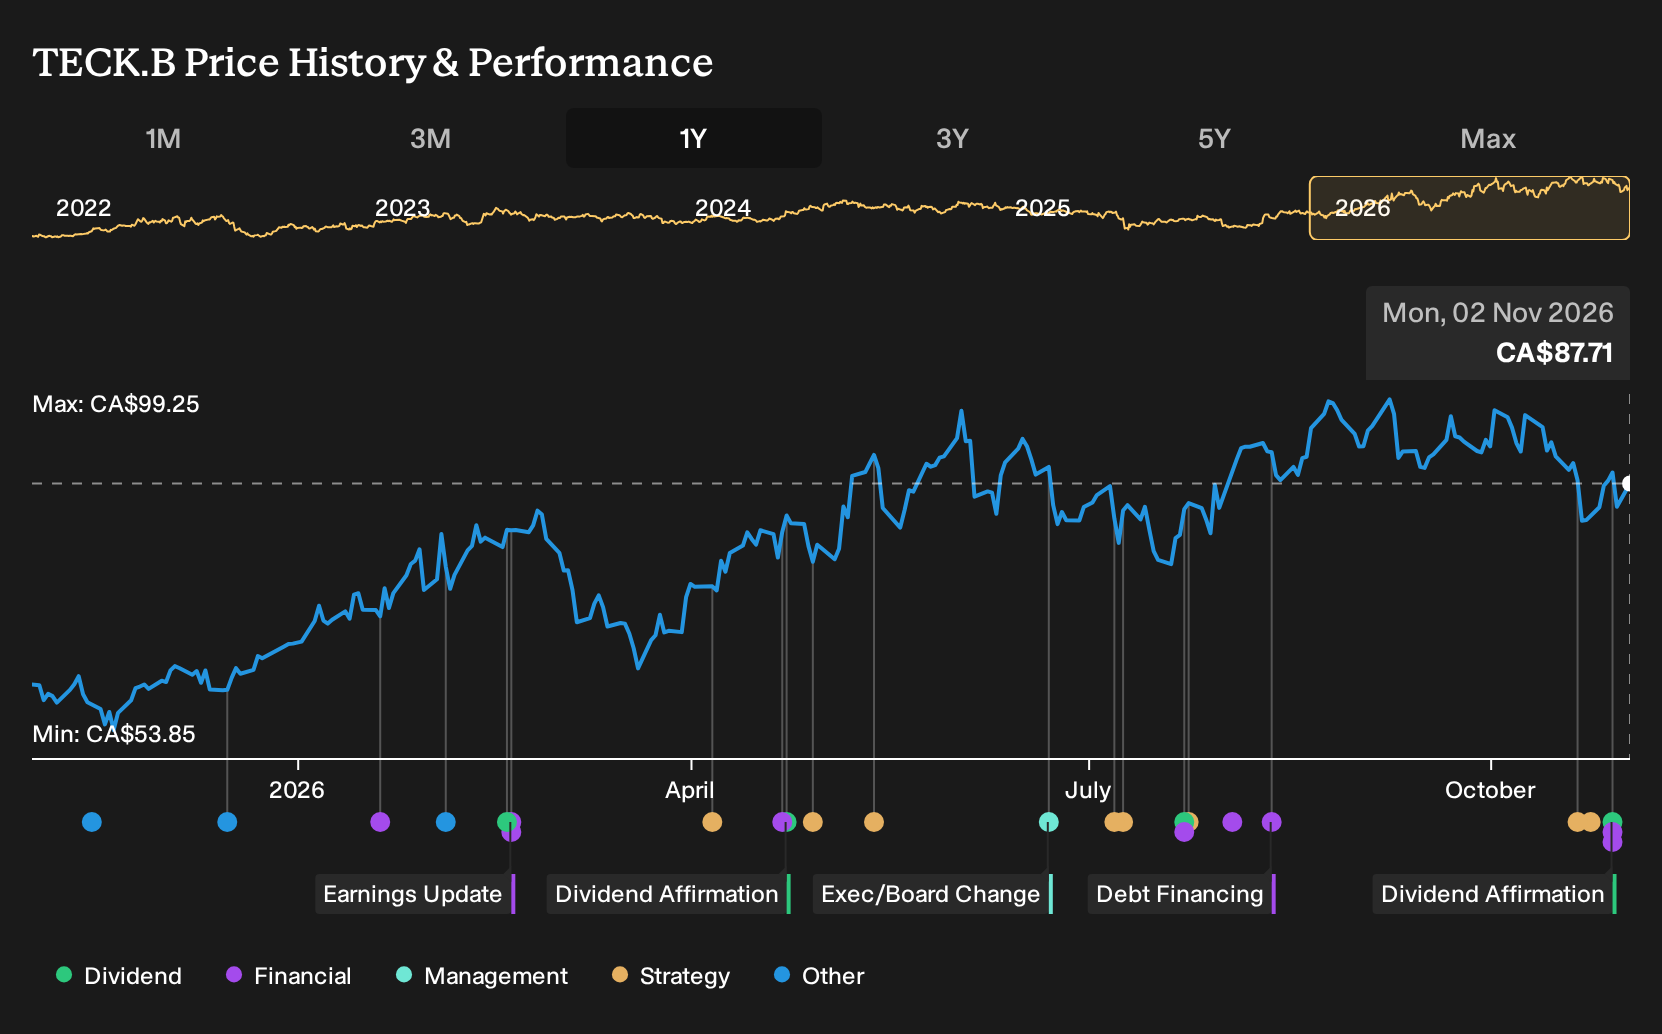
- Teck Resources reported third quarter 2026 sales of C$4,517 million and net income of C$1,592 million, alongside higher copper production. The company also confirmed a C$0.125 per share dividend to be paid on December 31, 2026 on Class A and Class B shares.
- The miner lifted copper output to 115,700 tonnes in the quarter despite extreme weather at Carmen de Andacollo and a strike that has since begun at Highland Valley Copper. This underscores how concentrated labour and climate pressures are for its key copper assets.
- The focus now turns to how Teck Resources' stronger third quarter earnings may influence the existing investment narrative built around copper growth.
Analyze how Teck Resources fits into the copper story by comparing it with 16 top copper producer stocks that could be positioned for the next stage of the cycle.
Teck Resources Investment Narrative Recap
To own Teck Resources, you have to believe the copper growth projects can keep running efficiently enough to justify heavy investment and offset weaker parts of the portfolio such as zinc. The recent jump in quarterly net income to C$1,592 million shows what strong operating quarters can look like when volumes and costs line up.
For the near term, the key swing factor is how reliably Teck Resources can run Quebrada Blanca and Highland Valley while capex remains elevated. The Highland Valley Copper strike and extreme weather at Carmen de Andacollo highlight the main risk: operational disruption that could undermine cash generation just as spending peaks.
The third quarter production update is the most relevant announcement for this copper story. Copper output reached 115,700 tonnes, with Quebrada Blanca contributing 47,200 tonnes despite severe weather. That kind of resilience matters if you are watching whether Teck Resources can support the planned life extension at Highland Valley and other growth work.
This production print also feeds directly into the main catalysts that analysts focus on: improving copper volumes and lower net cash unit costs from stronger byproduct credits. Execution on Quebrada Blanca upgrades and Highland Valley life extension remains central, while the labour action at Highland Valley reminds you that even technically ready projects still depend on stable, on-the-ground conditions.
Teck Resources' current analyst narrative points to forecast revenue of CA$15.9b and projected earnings of CA$2.2b by 2029, based on an assumed 1.8% yearly increase in revenue and an earnings decline of CA$1.6b from CA$3.8b today.
Uncover why Teck Resources' fair value indicates a 9% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts treat the Anglo Teck merger as the real swing factor for Teck Resources rather than the latest dividend or quarterly copper beat. Before this news, they were pencilling in revenue of about CA$17.3b and earnings of CA$3.2b by 2029. You can use these higher targets as one reference point, then decide whether the fresh Q3 results and the C$0.125 dividend affirmation push your own expectations closer to that more optimistic view or to a more cautious stance.
Explore 4 other Teck Resources fair value estimates, including one that suggests as much as 43% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Teck Resources research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Teck Resources. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Teck Resources' overall financial health at a glance.
Looking for more investment ideas beyond Teck Resources?
Once you have formed a view on Teck Resources, it can help to cross check that thesis against other opportunities that share similar quality traits or risk profiles. The Simply Wall St Screener lets you scan the market quickly so you can put Teck in context and avoid anchoring on a single stock.
- If you care most about quality at a sensible entry point, use our list of 5 high quality undervalued stocks that combine stronger fundamentals with more appealing pricing.
- For portfolio stability and capital protection, filter for 9 resilient stocks with low risk scores that may better match a more cautious approach.
- If you want to broaden your watchlist beyond well known blue chips, hunt through 8 high quality undiscovered gems that might not yet be widely followed.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com