


EN
Albemarle (ALB) Secured A New Credit Facility, Is The Stock 43% Undervalued?
Why Albemarle’s New Credit Facility Matters Now
Albemarle (ALB) just locked in a new unsecured revolving credit facility of up to US$1.5b that runs to 2031, replacing an agreement that was set to mature in 2028. Investors are weighing what this extra liquidity means.
Recent trading tells a different story to Albemarle’s fresh liquidity. The share price is down 13.4% over the past month and 37.1% year to date, while the 5 year total shareholder return has declined 65.4%, signalling pressure rather than building momentum.
That weaker trend sits alongside several fresh developments, including the new US$1.5b revolving credit line, a reaffirmed quarterly dividend of US$0.41 per share, updated bylaws that make shareholder called meetings easier, and an income focused ETF adding to its position as Albemarle heads into its upcoming third quarter 2026 results.
Spot opportunities that echo Albemarle’s mix of pressure and potential in our hand picked list of 34 high quality undervalued stocks.Albemarle still runs a globally important energy storage and specialty chemicals business, yet the share price reset and fresh credit line tell a tougher story. So is this now a strong franchise trading on a fair tag, or not?
Most Popular Narrative: 43% Undervalued
Albemarle closed at $90.56, while the most followed narrative pegs fair value nearer $158.73, a wide gap that puts expectations for its cash generation and lithium positioning under the microscope.
The company is executing aggressive cost reduction and productivity initiatives (achieving a $400M annual run-rate in savings, 6 months ahead of plan), ramping low-cost asset expansions, and optimizing its conversion network, which is likely to structurally reduce operating costs and increase net margins in a lower price environment.
See why 195 investors see Albemarle as 43% undervalued.
Result: Fair Value of $158.73 (UNDERVALUED)
Still, the narrative can crack if lithium oversupply keeps prices weak for longer, or if resource nationalism and regulatory setbacks disrupt Albemarle’s key producing regions.
Find out about the key risks to this Albemarle narrative.
Another View: What Albemarle’s Sales Multiple Is Telling You
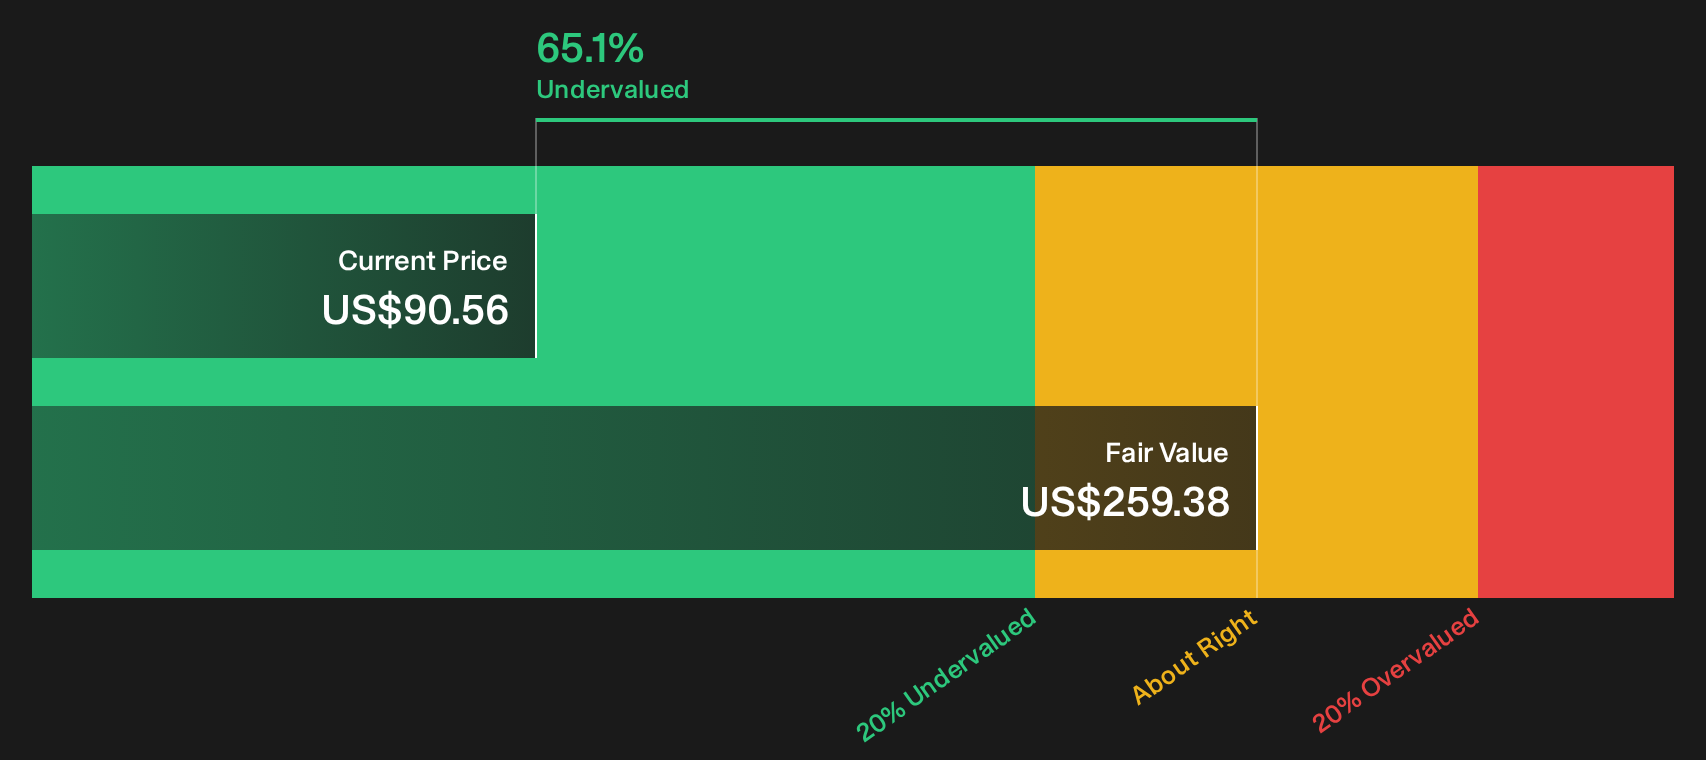
Albemarle may look inexpensive compared with a fair value estimate of $259.38 based on future cash flows. However, its P/S ratio of 1.8x is higher than both the US Chemicals industry at 1.2x and its own fair ratio of 1.4x. That suggests a higher valuation risk if sentiment changes, so which signal do you place more weight on?
To see how this cash flow based result is built, and how sensitive it is to the inputs, Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed messages on Albemarle can tempt you to lean on a single datapoint. Yet the faster you test the full picture yourself, the quicker you can anchor a view that matches your risk tolerance and time horizon. To weigh both the pressure points and the bright spots side by side, start with 3 key rewards and 2 important warning signs.
Looking for more Albemarle style investment ideas?
You have the Albemarle story. Now widen your lens and pressure test your thesis against other opportunities that match your risk appetite and income goals.
- Target sturdier balance sheets by scanning companies on our list of solid balance sheet and fundamentals (24 results) that pair financial resilience with fundamental strength.
- Hunt for potential mispricings and compare Albemarle with a curated 34 high quality undervalued stocks that screens for quality alongside value.
- Build a steadier income stream by reviewing a focused 4 dividend fortresses designed for investors who care about yield backed by fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com