


EN
Does Earnings Beat Change The Bull Case For Harmonic (HLIT)?
- Harmonic reported third quarter 2026 results with revenue of US$148.84 million, net income of US$14.64 million, and EPS of US$0.13, alongside updated full year guidance that frames expected revenue between US$545 million and US$555 million.
- The broadband specialist pointed to new customer wins across seven countries and growing adoption of its connectivity, intelligence, and edge AI compute products as key drivers supporting the stronger outlook.
- This article examines how Harmonic's raised full year revenue guidance may be reshaping the investment narrative built around broadband, software, and intelligence.
Compare Harmonic's broadband and edge AI momentum with a hand picked roster of infrastructure focused peers in the 53 AI infrastructure stocks to see how this earnings story stacks up.
Harmonic Investment Narrative Recap
To own Harmonic, you need to believe the broadband and intelligence portfolio can keep scaling while the customer base broadens beyond a few large operators. The Q3 print, with US$148.84 million of revenue and US$14.64 million of net income, supports that thesis in the near term by showing demand across connectivity, intelligence, and edge AI compute offerings.
The key short term swing factor remains execution on new deployments with large broadband clients while managing higher component and memory costs that have already pressured margins versus last year. Customer concentration and potential pricing pressure from top operators still look like the biggest operational risk despite the added nine customers across seven countries.
The most relevant fresh data point is Harmonic’s updated 2026 guidance, which now calls for full year GAAP revenue of US$545 million to US$555 million and net income of US$59 million to US$63 million. Q4 guidance, at US$141 million to US$151 million of revenue and US$0.13 to US$0.16 in EPS, frames how management currently sees demand and cost pressure playing out over the next few months.
For you as a shareholder, that guidance ties directly into the main catalyst. The story hinges on Harmonic converting broadband deployments into a higher mix of software, intelligence, and edge AI services while containing unrecovered memory expenses. Any sign in upcoming quarters that revenue concentration is easing and recurring software contribution is rising would speak directly to that thesis, while weaker margins or customer pushback would challenge it.
Harmonic's narrative reflects analyst expectations that revenue will reach US$630.9 million and earnings will be US$93.8 million by 2029. This outlook is based on an assumed 12.4% yearly revenue growth rate and an earnings increase of about 3.6 times from US$26.4 million today.
Uncover why Harmonic's fair value indicates a 58% potential upside to its current price that could narrow quickly.
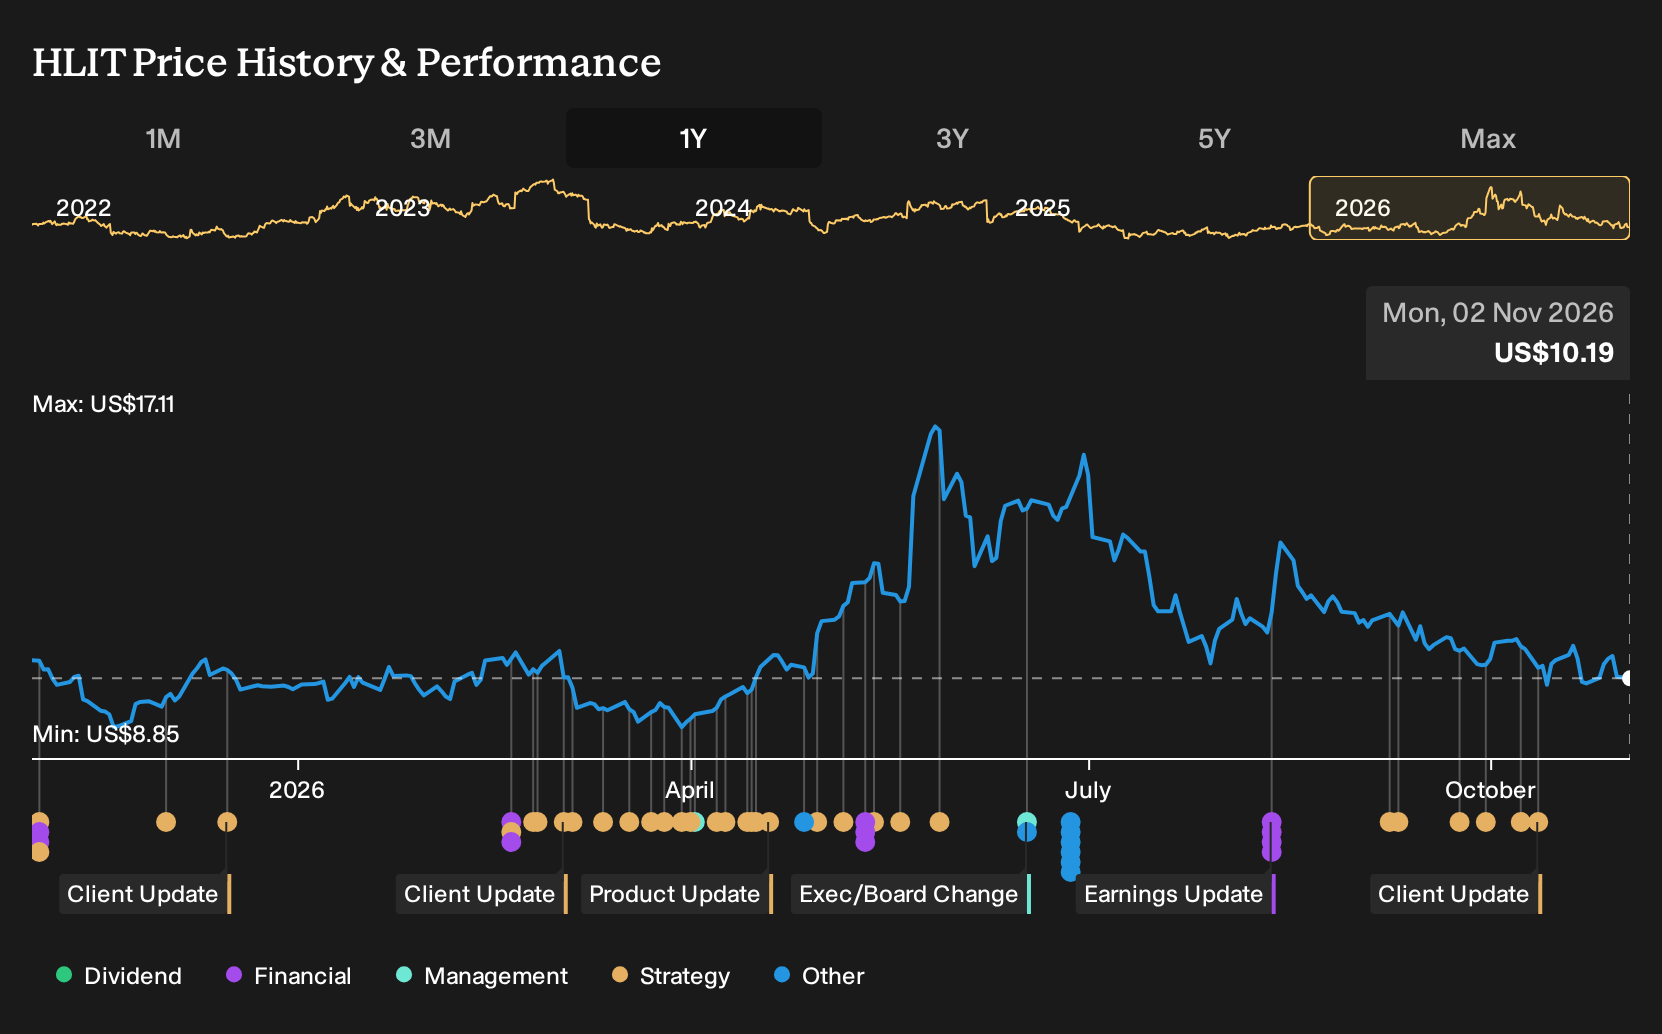
Exploring Other Perspectives
One alternate view focuses on margin risk rather than broadband or edge AI upside. The most cautious Harmonic analysts were only penciling in about US$571.0 million of revenue and US$80.0 million of earnings by 2029, which supports a lower P/E and price target. This more pessimistic path shows how widely opinions can differ, so it helps to compare several narratives before deciding what this earnings update might change for you.
Explore 3 other Harmonic fair value estimates, including one that suggests it could be worth just $15.96.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Harmonic research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Harmonic. The report includes a comprehensive fundamental analysis summarized in a single visual: the Snowflake, making it easy to evaluate Harmonic's overall financial health at a glance.
Looking For More Investment Ideas Beyond Harmonic?
If this Harmonic update has you rethinking your watchlist, it can help to step back and compare it with other businesses that match your preferred balance of quality, risk, and income. The Simply Wall St Screener lets you filter by fundamentals so you can build a list that fits how you want to invest, not just what is in the headlines today.
- If you are hunting for quality at a reasonable entry point, start with a focused group of 34 high quality undervalued stocks that currently combine stronger fundamentals with lower valuations.
- For investors who care most about financial resilience, narrow your research to a list of solid balance sheet and fundamentals (24 results) that can handle tougher conditions without relying heavily on fresh capital.
- If you prefer under-the-radar opportunities, scan a curated pool of 19 high quality undiscovered gems where underlying metrics may matter more than current headlines.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com