


EN
Western Digital (WDC) Stock Still Looks Cheap Despite Strong AI Demand News
Western Digital has delivered an extremely strong multi year share price run, yet the recent pullback and fresh earnings news put a sharper spotlight on whether its current valuation is adequately backed by the profits it is generating. With the stock now reacting to both sector swings and company specific headlines, the question for you is how far its earnings story goes in justifying today's price.
- Over the past 3 years, Western Digital has produced a very large share price gain of about 9x. This raises the stakes on whether its earnings power can support such a step change in market value.
- Recent earnings highlighted strong demand from cloud and AI related storage customers and an increase in the regular cash dividend. These developments can influence how investors think about the durability of the company's profit base and the timing of future cash flows.
- Your read on Western Digital is one view; the desks covering it have another. See what analysts think Western Digital's shares could be worth.
The issue now is whether Western Digital's current share price is justified by its earnings when set against the Fair Ratio benchmark.
If you are weighing whether Western Digital at US$338.59 already reflects its AI and cloud storage earnings story, it can help to compare that theme against 53 AI infrastructure stocks.
Is Western Digital Still Cheap on Earnings?
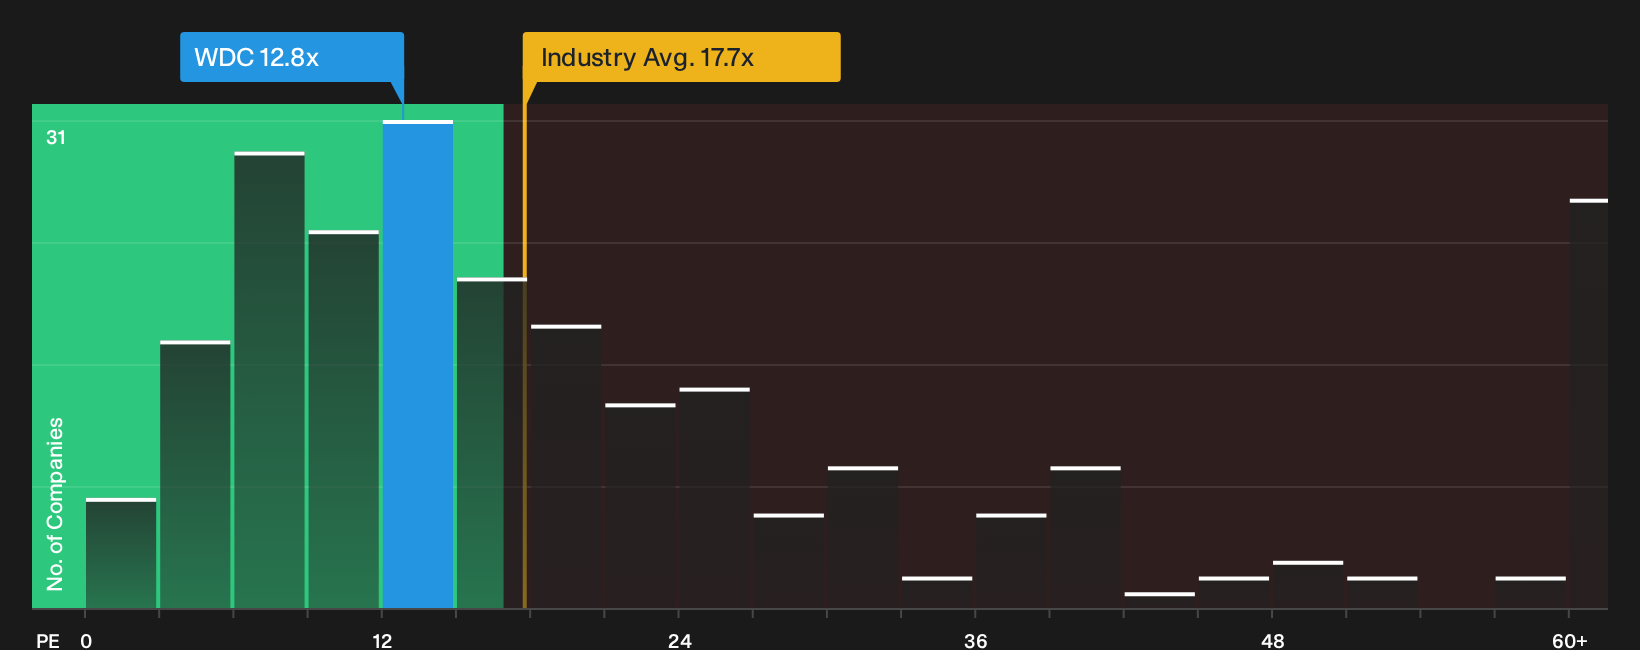
The P/E ratio fits Western Digital because earnings are currently the key lens investors are using to price its AI and cloud storage exposure. On this measure, the stock trades at about 12.8x earnings, which sits well below the broader tech sector average of roughly 17.7x and below peers around 21.6x. That sets Western Digital at a clear discount to the sector on raw earnings.
Because recent Q1 2027 results showed strong profitability and guidance without relying on speculative story alone, the Fair Ratio model, which folds in growth expectations, margins, size and risk, points to a higher P/E than where the shares currently change hands. Despite that upbeat earnings update and raised dividend lifting the quality of the profit stream, the market multiple still prices Western Digital below the level implied by this tailored benchmark, which suggests the earnings story is not fully reflected in the current tag. Explore the numbers behind Western Digital's P/E valuation.
The Western Digital Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Western Digital pick up where the P/E discussion stops and spell out the concrete earnings, margin and growth paths that would make the stock look materially cheaper or more expensive than it does today. Instead of one tidy number from a ratio or model, they lay out the future that number relies on so you can watch how Western Digital's actual results line up over time.
Investors circling Western Digital are largely split between those who see more upside left in the story and those who think expectations already run hot.
Bull case: 48% undervalued
"The explosive increase in unstructured data generated by AI applications, Agentic AI, and cloud-based services across industries is still driving unprecedented storage needs…"
Discover why this Narrative puts Western Digital at 48% undervalued.
Bear case: roughly fairly valued
"Record margins are not just the reward in this business, they are the invitation…"
Explore why this Narrative puts Western Digital at roughly fairly valued.
One more piece of the Western Digital story worth checking
Before leaning too hard on Western Digital’s earnings profile or dividend signals, it is worth knowing that separate checks have flagged specific areas of concern that could reshape the risk picture. Take a closer look at 2 warning signs (1 major) before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com