


EN
Earnings Beat Might Change The Case For Lindblad Expeditions Stock
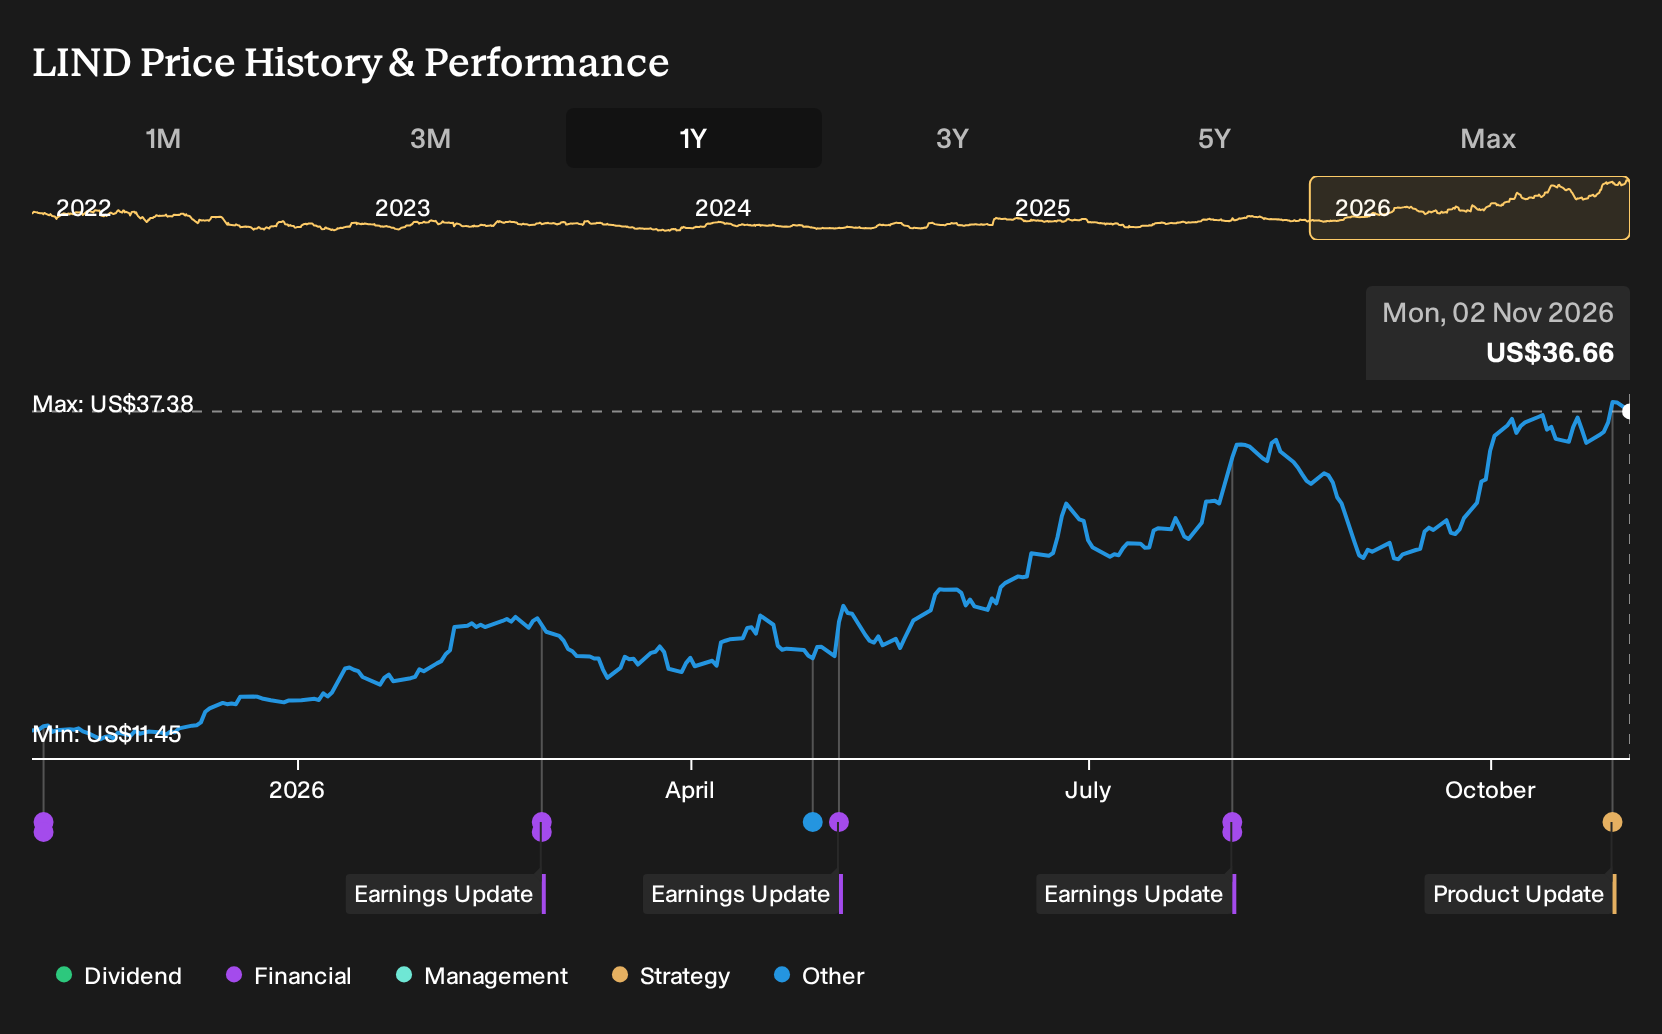
- Lindblad Expeditions Holdings reported third quarter 2026 sales of US$269.15 million and net income of US$24.24 million, with basic earnings per share from continuing operations of US$0.37.
- Across the first nine months of 2026, the business moved from a loss to net income of US$29.33 million, which gives investors fresh data on how its expedition model is converting demand for adventure travel into bottom line results.
- Attention now turns to how Lindblad Expeditions' shift to profitability may influence its longer term investment narrative.
Compare Lindblad Expeditions Holdings' shift to profitability with other travel and experience providers on our curated list of 19 high quality undiscovered gems.
Lindblad Expeditions Holdings Investment Narrative Recap
To own Lindblad Expeditions Holdings, you need to believe its expedition model can turn strong interest in adventure travel into durable earnings, not just a single profitable stretch. The latest quarter, with US$269.15 million in sales and US$24.24 million in net income, supports that case in the near term because it shows the fleet and itineraries are generating positive results.
The key short term catalyst is whether Lindblad Expeditions Holdings can keep filling high priced trips without letting marketing, royalty and operating costs run away. The biggest risk is that cost inflation, fleet constraints or weaker discretionary spending could erode margins just as the business has moved into the black. If that balance shifts, the impact on the story could be material.
The most relevant recent update alongside these earnings is the new 2028 to 2029 National Geographic Lindblad Expeditions voyage collection. It introduces additional itineraries across the Galápagos, Baja California, the Amazon, Costa Rica, Panama, Egypt and Peru, using both the core expedition fleet and chartered vessels to widen the range of trips on offer.
For you as an investor, that long dated deployment speaks directly to future occupancy and pricing power, which relate back to today’s profitability inflection. It also interacts with key risks. More complex itineraries and royalty bearing partnerships can increase revenue potential but may lock in higher fixed costs and capital needs, so execution on utilization and cost control remains central to the Lindblad Expeditions Holdings thesis.
Lindblad Expeditions Holdings' current analyst narrative points to revenues of US$987.9 million and earnings of US$65.8 million by 2029, based on an assumed 6.0% yearly revenue growth rate and a move from a loss of US$20.3 million in earnings today to that 2029 consensus figure, which is an increase of roughly US$86 million in profit over the period.
Uncover why Lindblad Expeditions Holdings' fair value indicates a 3% potential downside to its current price, a premium that may not be sustained.
Exploring Other Perspectives
Some of the lowest Lindblad Expeditions Holdings forecasts lean hard into fuel cost risk. Before this earnings release, those analysts were pencilling in about US$1.1b of revenue and US$81.4 million of earnings by 2029, yet still argued the stock looked stretched. That more cautious view might shift as the new results are absorbed. It may be helpful to explore both narratives before deciding what feels reasonable to you.
Explore 2 other Lindblad Expeditions Holdings fair value estimates, including one that suggests it could be worth just $35.60.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own research and judgment.
- A great starting point for your Lindblad Expeditions Holdings research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Lindblad Expeditions Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Lindblad Expeditions Holdings' overall financial health at a glance.
Looking For More Investment Ideas Beyond Lindblad Expeditions Holdings?
If Lindblad Expeditions Holdings has sharpened your interest in experience led businesses, it may be useful to widen the search and see how other listed companies stack up on quality, value and resilience using the Simply Wall St Screener.
- For investors who want quality at a discount, start with a curated pool of potentially mispriced opportunities through 34 high quality undervalued stocks.
- If capital preservation matters most to you, focus on businesses with steadier fundamentals and lower overall risk profiles using 29 resilient stocks with low risk scores.
- For those who care about balance sheet strength, filter for companies with cleaner debt profiles and healthier financial footing through list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com