


EN
Earnings Guidance Reset Might Change The Case For Investing In Sun Communities Stock (SUI)
- Sun Communities reported third quarter 2026 revenue of US$558.2 million and net income of US$120.7 million, updated its fourth quarter and full year 2026 EPS guidance, and confirmed interest income of US$25.5 million for the year, alongside completing a US$373.1 million buyback of 3.1 million shares.
- The contrast between a profitable third quarter and a projected full year loss of about US$6.6 per share is putting Sun Communities' earnings mix, non recurring items, and capital allocation choices under closer scrutiny for anyone focused on cash generation and balance sheet resilience.
- This raises the question of how Sun Communities' investment narrative is affected by strong quarterly EPS alongside guidance that signals a full year loss.
Compare Sun Communities' guidance against peers by reviewing a tight shortlist of income focused real estate players in our 4 dividend fortresses.
Sun Communities Investment Narrative Recap
To own Sun Communities, you need to be comfortable with a real estate platform where manufactured housing and RV sites are the core engine, while accounting noise and portfolio cleanup can make headline EPS volatile. The recent mix of a profitable quarter and a guided full year loss keeps the spotlight on how recurring site income, FFO and leverage trend from here.
The key near term swing factor remains execution on RV mix, technology rollouts and the shift toward a more focused North American footprint. The biggest risk right now is that heavy debt and one off items keep masking underlying cash generation, which could limit flexibility if funding conditions tighten or the U.K. portfolio sale timetable slips.
The fresh fourth quarter and full year 2026 EPS guidance is the clearest piece of news to work with. Management is signaling that a quarter with US$0.36 to US$0.44 in diluted EPS can coexist with a full year diluted loss of about US$6.6 per share. This implies sizable non recurring or below the line impacts outside the core property operations.
For you as a shareholder or potential buyer, this matters because catalysts like the Park Holidays sale, debt reduction and any RV recovery now sit on top of a guidance framework that already bakes in substantial losses for 2026. It raises the bar on execution, increases the importance of clean disclosure around one off items and keeps balance sheet management front and center in the near term story.
Sun Communities' current earnings are about US$136.5 million, with analysts expecting consensus earnings of US$483.0 million by 2029. That implies an earnings increase of roughly US$346.5 million on largely flat revenue assumptions, with forecast revenues around US$2.3b in 2029.
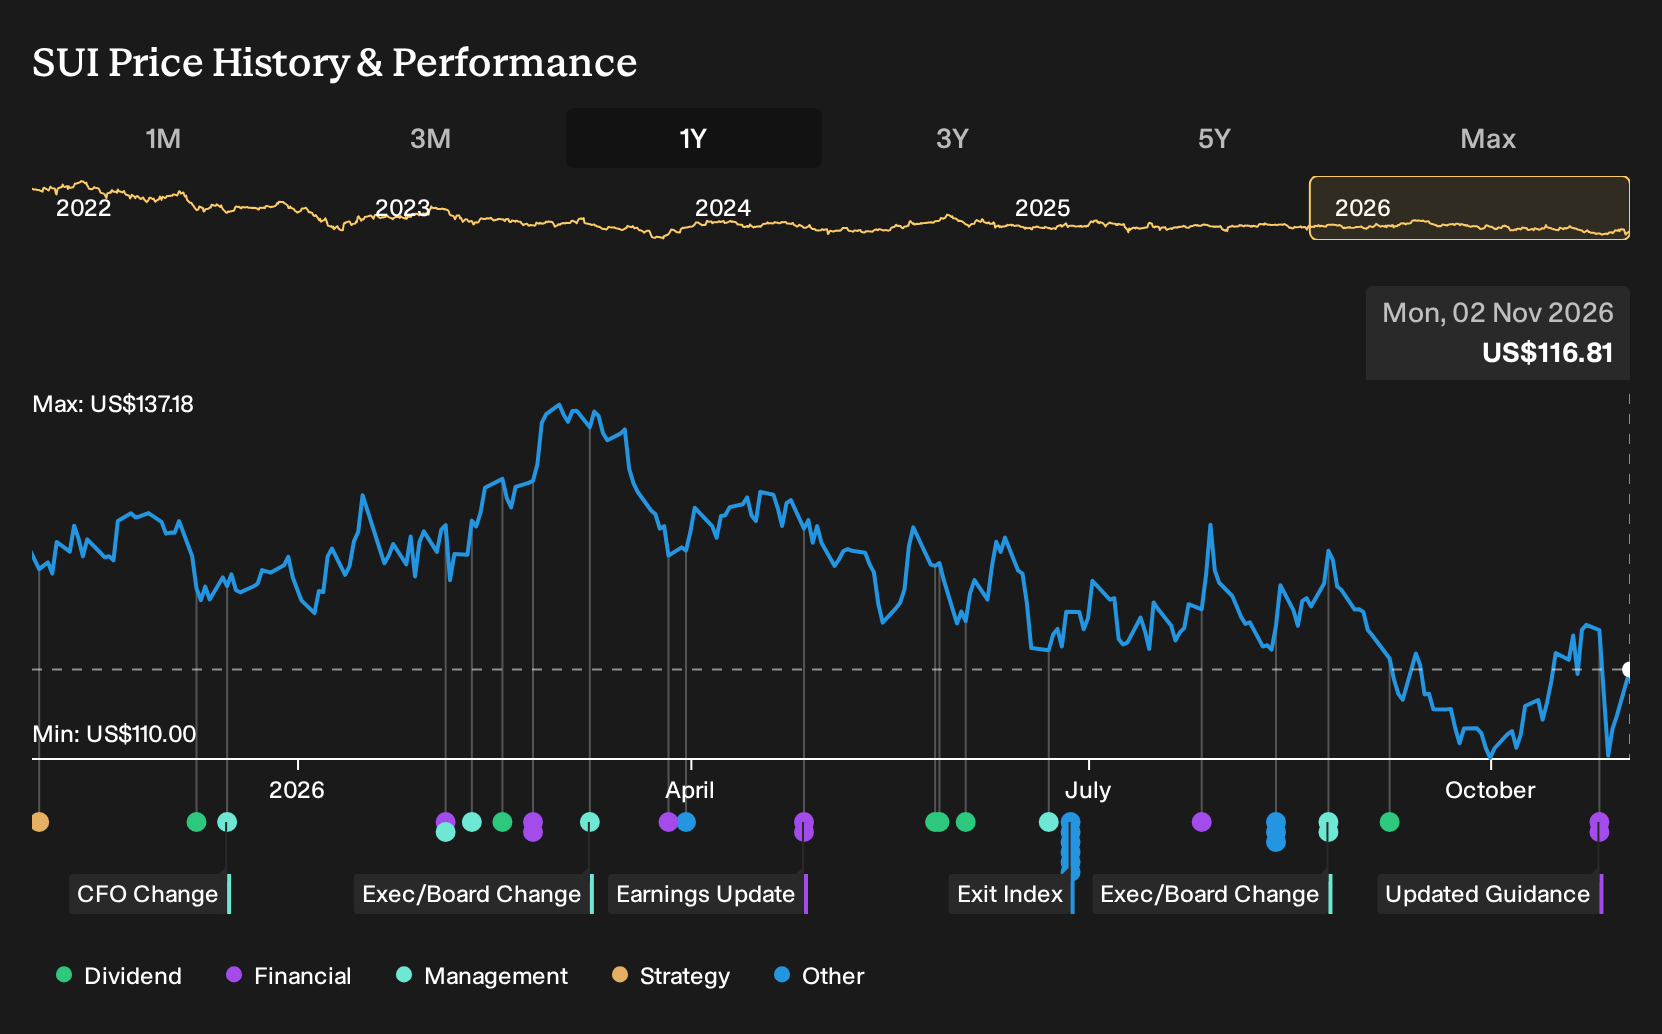
Uncover how Sun Communities' fair value indicates a 16% potential upside to its current price before that valuation gap closes.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span roughly US$136 to US$212 per share, so private investors are modeling very different futures for Sun Communities. You are weighing that spread against risks like RV mix pressure or a delayed Park Holidays close, which could meaningfully influence future earnings power.
Explore another Sun Communities fair value estimate, including one that suggests there could be as much as 82% upside from the current price.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Sun Communities research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Sun Communities. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sun Communities' overall financial health at a glance.
Looking for more investment ideas beyond Sun Communities?
Once you have a view on Sun Communities, it can help to cross check that thesis against other businesses with different balance sheets, earnings profiles, and dividend approaches using the Simply Wall St Screener.
- If capital preservation is high on your list, review a curated set of companies with resilient profiles through the 29 resilient stocks with low risk scores.
- If you want potential value on your side, scan for businesses that pair quality fundamentals with appealing valuation signals using the 34 high quality undervalued stocks.
- If reliable income matters most to you, compare payouts and balance sheet strength across a hand picked universe of higher yielding payers via the 4 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com