


EN
Can Napco Security Technologies (NSSC) Stay Below Fair Value After Its Selloff?
Napco Security Technologies has seen its share price slide in recent months after a sharp reaction to its latest results, which puts fresh focus on whether the cash the business is expected to generate can justify where the stock trades today.
- Over the past 3 years the stock has gained 46.6%, so a lot of value creation now hangs on how durable and sizable its future cash flows prove to be.
- Recent record revenue and high margin recurring service income, alongside softer equipment sales, can reshape expectations for how quickly Napco converts growth into steady cash generation.
- What if you looked at Napco Security Technologies through its earnings instead? See why Napco Security Technologies's 26.7x P/E tells a different valuation story.
The issue now is whether the current price fairly reflects Napco Security Technologies' intrinsic value when viewed through the lens of its cash flows.
If this earnings reaction has you rethinking where to focus fresh research, a targeted list such as 34 high quality undervalued stocks can be a useful starting point alongside your work on Napco Security Technologies.
Does Napco Security Technologies Look Undervalued on Cash Flow?
The Discounted Cash Flow (DCF) model here focuses on the cash Napco Security Technologies can return to shareholders over time. Latest twelve month free cash flow sits at about $59.2 million, and the projections assume growing free cash generation rather than a shrinking base.
Analysts see Napco’s free cash flow building from that level over the coming decade as the business leans further into recurring services alongside its hardware footprint. Record fiscal Q1 2027 revenue and high margin subscription income, despite the recent earnings miss and the share price drop to around $32.10, help explain why the DCF projections put Napco Security Technologies' estimated intrinsic value meaningfully above the current share price. Find out what Napco Security Technologies could be worth using our Discounted Cash Flow (DCF) estimate.
The Napco Security Technologies Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Napco Security Technologies sit between the valuation work above and the real world assumptions that need to hold on growth, margins and earnings for the stock to be worth materially more or less than today’s price. They are available on the Community page. Each scenario ties a specific fair value to a clear story about Napco Security Technologies' potential catalysts and key risks so you can track over time which version of events appears to be unfolding.
One of the top community narratives on Napco Security Technologies: 37% undervalued
"Persistent growth in high margin recurring service revenue, now at an annualized run rate of about US$103 million with gross margins around 90%, positions Napco Security Technologies to keep lifting overall margins and smoothing earnings over time as more of total revenue comes from these contracts…"
Discover why this Narrative puts Napco Security Technologies at 37% undervalued.
One more factor to weigh on Napco Security Technologies before you act
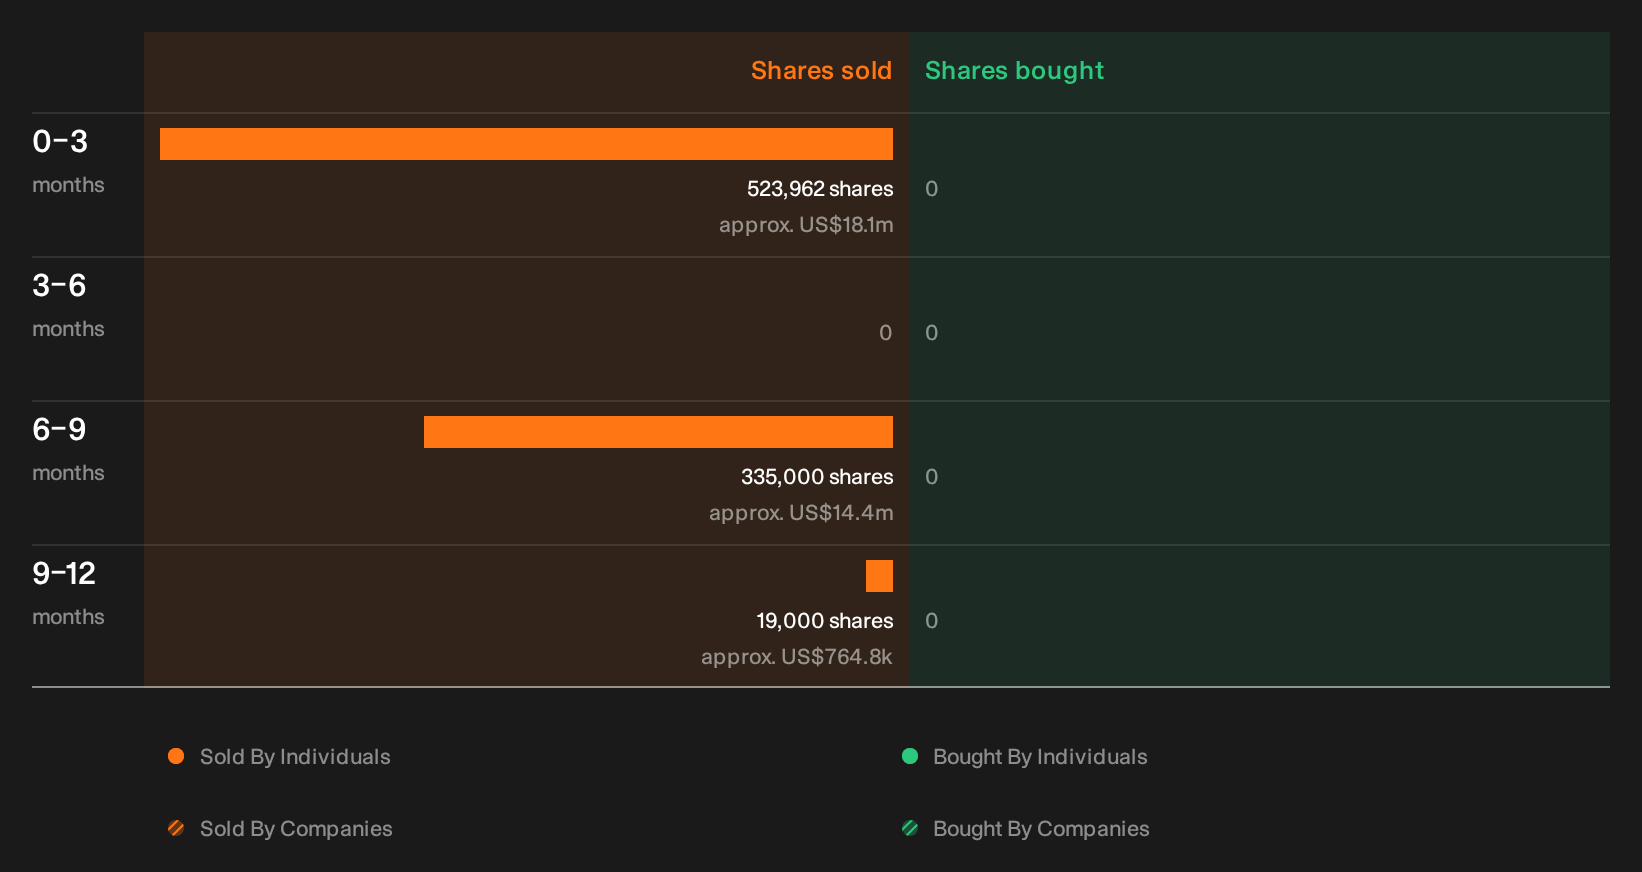
Before you lean too heavily on the numbers alone, the checks also point to recent selling by people inside the business, with who sold, how much, and what it might mean still for you to review. See the recent insider selling flagged for Napco Security Technologies.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com